Toronto’s condo crisis and the failure of economic forecasting
Toronto’s once-booming condo market has stalled abruptly, exposing the risks of speculative demand and outdated economic models – raising deeper questions about how markets price uncertainty and adapt to sudden shifts
Those familiar with the British sit-com The IT Crowd, which was about workers in the IT department of a firm, and premiered in 2006, will remember the catchphrase “Have you tried turning it off and on again?” which was their go-to response for any technical computing problem. A similar technique is currently being applied to the real estate sector in Canadian cities such as Toronto, especially for the market for new condominiums (or condos).
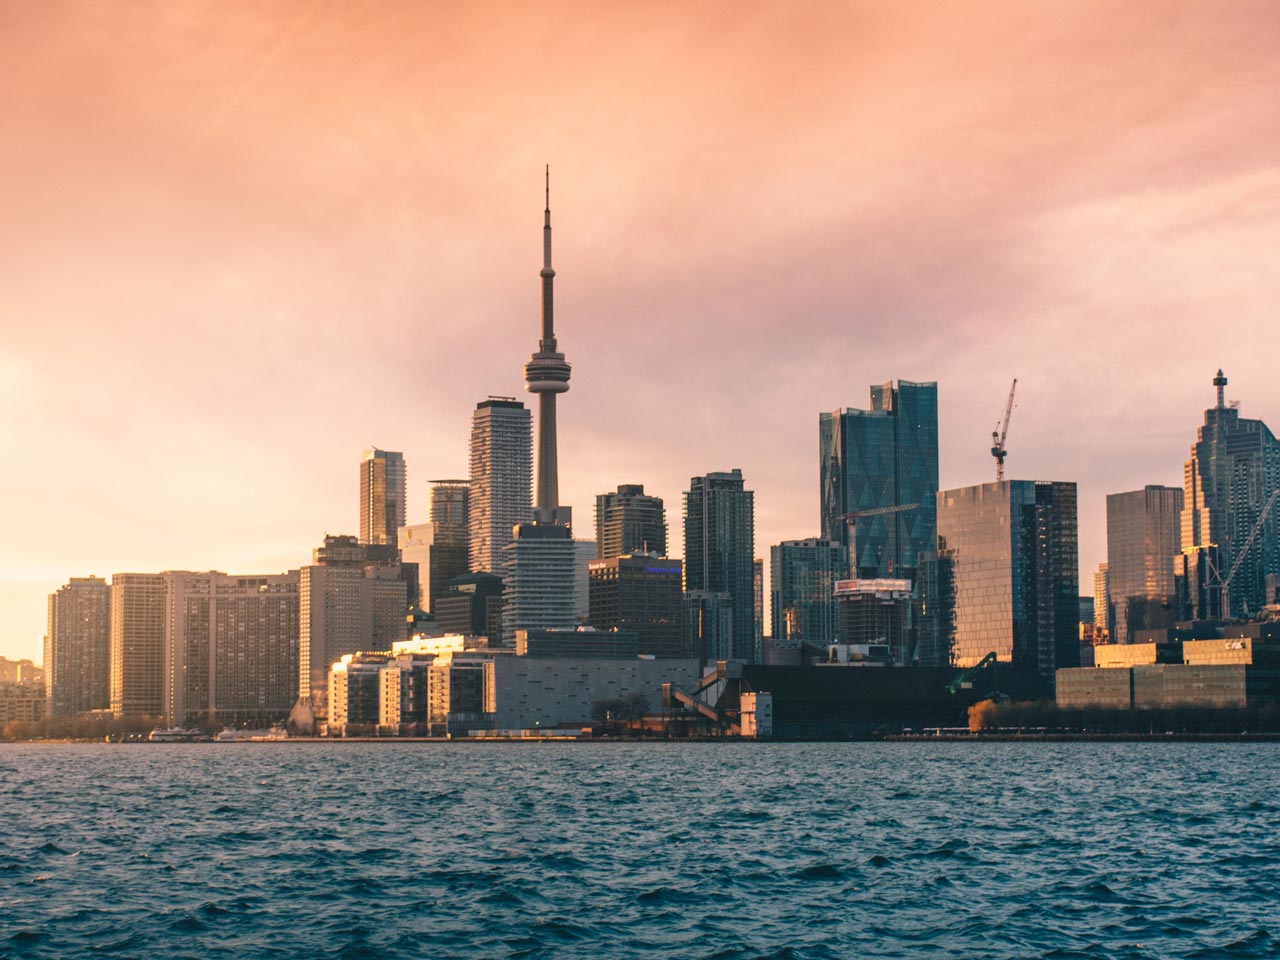
For the last decade and more, Toronto has been the construction hub of North America, its skyline studded with more cranes than any other city. Underlying all this activity was the unquestioned belief among investors that real estate was a safe investment. This was the case even during the Great Financial Crisis (GFC), which the Canadian economy endured quite well, in part because banks did not resort to the same complex financial derivatives as did their counterparts in the US. After the briefest of dips, house prices showed explosive growth, doubling over the next 12 years and almost tripling by the time they reached their glorious peak in 2022.
Usually this growth was attributed to demand from an expanding population, which fits with the traditional view that price rises are typically driven by excess demand. In reality, the number of houses being sold was fairly static. The only kind of property that was selling like hot cakes was the kind that didn’t actually exist: pre-construction condos.
Boxes in the sky
Often these were ‘shoebox’ apartments that were intended more as an investment than a place to live, and represented a kind of futures bet on the market. The majority were purchased by investors, who could put down a small deposit before construction began, and expect to sell at a profit just before completion to an end-user or another investor. Mainstream economists saw no problem with this because on the surface it seemed the economy was doing well. The central bank cut interest rates to the bone, since according to their metrics, which didn’t account for house prices, inflation was quiescent.
The deterministic models of the past are giving way to new approaches that embrace uncertainty
When official inflation jumped in the post-Covid years, interest rates bounced off their lows. Mortgages suddenly became more expensive. Population growth, which was almost entirely due to immigration, which peaked at around 3.2 percent in 2022, compared to an average 0.5 percent for G7 countries, was suddenly thrown into reverse, with Canada actually reporting a small decline in 2025 for the first time on record. The real estate market on the whole adjusted to these contortions with a decline in both sales and prices. But the market for pre-construction condos didn’t adjust – it just stopped.
In December 2025, only 87 pre-construction units were sold across the entire Greater Toronto Area, which has a population of about 7.8 million. That is the lowest single-month total in the 45 years that data has been tracked. Developer activity also ground to a halt, with just 10 new condo projects launching throughout the entire year, compared to the dozens typical in a healthy market. Remaining new home inventory hit a record high equivalent to over two years of sales. And in the first quarter of 2026, things really iced up, as zero new projects were launched. There is a sense though that this reset is about more than just pre-construction condos – it is about how we think about the economy.
Tail events
The GFC was a crisis not just for the economy, but also for the field of economics. Not in the sense that economists actually lost their jobs, but because their models failed. Economists had long assumed that probabilities could be described by a so-called normal distribution, or bell curve as it is sometimes known.
However, risk models based on this assumption quickly broke down when it turned out that so-called tail events had a much higher chance of occurring than the model suggested. And mainstream economics, which was based on the idea that the economy is a rational, efficient, self-stabilising system – which is immune to things like booms and busts – was thrown into a state of complete crisis along with the economy.
While the field of economics is famously resistant to change and new ideas, a couple of decades later, things do show signs of moving on, at least in some corners of the profession. In their recent book Adaptive Finance: Embracing Uncertainty and Complexity, economists Frank Fabozzi and Sergio Focardi write that “The need for models predicting tail events and market anomalies has become increasingly apparent after the GFC.
“Traditional models, which often rely on normal distributions and the assumption of efficient markets, could not predict the extreme events that characterised the crisis, such as the collapse of major financial institutions and the sudden freeze in credit markets.”
It is no surprise that in the “new paradigm in economics and finance” described by Fabozzi and Focardi, “the deterministic models of the past are giving way to new approaches that embrace uncertainty.” As another market freezes up in front of us, it is past time for economists to embrace these new insights. Instead of just saying, “Let’s try turning it off…”