The economic path to climate finance

As the world pursues decarbonisation, the concept of a ‘just transition’ has become ubiquitous, particularly when describing the shift away from fossil fuels in emerging and developing economies. Emissions targets at the global and national levels are viewed as the main drivers of the energy transition, and the climate policies developed to meet those targets must balance environmental and social objectives. But decarbonisation is not always the product of a planned emissions-reduction pathway. In fact, with the cost of renewables continuing to fall, many emerging and developing countries now see phasing out fossil fuels as a matter of economic survival and energy security. For example, in January 2024, Ethiopia banned the import of petrol and diesel vehicles with immediate effect. The move was striking precisely because it was framed not as a climate commitment, but as a way to reduce its annual fossil-fuel import bill of more than $5bn, which consumed a huge share of the country’s scarce foreign-currency reserves.

With the country constructing Africa’s largest hydroelectric dam, it made little economic sense to remain dependent on expensive fuel imports to power transport. Chinese electric vehicles (EVs) quickly filled the market gap created by the ban; the streets of Addis Ababa are now teeming with BYD cars. Tax exemptions and import duty waivers for EVs, coupled with the rising costs of second-hand internal-combustion-engine vehicles, have accelerated this shift in consumer behaviour. The Grand Ethiopian Renaissance Dam, which was officially opened in September 2025, produces enough surplus hydropower to run these EVs cheaply.

Swift update of solar power
Crucially, economic and energy-security concerns, not a formal emissions-reduction framework, were responsible for such rapid decarbonisation. A similar pattern seems to hold in Pakistan.

The country’s swift uptake of solar power reflected factors that created an opportunity for disruptive change, not green advocacy or a national climate plan. In 2022, a massive flood left roughly one-third of the country under water and caused more than $30bn in economic damage, straining government budgets, reducing household incomes, and undermining the state’s ability to operate public utilities. With energy costs rising, there was a clear need for an alternative to diesel generation.

Meanwhile, China had surplus solar-panel production, and the US had imposed import restrictions. Pakistan took advantage of China’s discounted solar panels to adopt renewable generation at a rapid clip. Between December 2021 and December 2025, the share of Pakistan’s electricity generated by solar increased five-fold. A late mover confronting unique energy-security challenges, Pakistan benefited from cost advantages created by global trade dynamics.

While South Africa has been following an emissions-reduction pathway for decades, an affordability crisis ultimately drove widespread decarbonisation. These countries are moving away from fossil fuels largely because of mounting economic and energy pressures, rather than a narrow focus on emissions reductions. But this does not mean that the question of justice disappears. Lower-income households account for a smaller share of the roughly eight gigawatts of rooftop solar installed in South Africa, reflecting high upfront costs. Crisis-driven decarbonisation still requires efforts to improve affordability and ensure that people from all walks of life can participate in the energy transition.

Systemic change is required
Policymakers have used the concept of a ‘just transition’ to make a morally and emotionally compelling case for decarbonisation. But they should be focusing on how to foster systemic change. Understanding that the primary drivers of solar uptake in South Africa and Pakistan or EV adoption in Ethiopia are structural and economic could help policymakers develop better tools and systems. This also has direct implications for how philanthropists and governments allocate resources. Channelling funding toward grid capacity, storage infrastructure, and affordable financing mechanisms will likely produce more durable results than funding for climate education and communication.

Investing in efforts that aim to improve people’s lives, from lower energy bills to unfettered electricity access, will do more to accelerate decarbonisation – and to change hearts and minds. To be sure, the world must reduce emissions to prevent the planet from overheating. To achieve that goal, it should focus on expanding energy access and ensuring affordability. That means recognising and adequately responding to the external pressures that can support decarbonisation pathways in emerging and developing economies. Ethiopia, Pakistan, and South Africa have shown that economic factors can provide better entry points for scaling green solutions and catalysing systemic change than top-down, morally driven transition plans.

Europe’s moment of supreme confidence

If there is one key takeaway from the recent Munich Security Conference, it is a message of trust and confidence in Europe. The EU is a technology, trade and industry powerhouse. Around Europe, the signs of this strength abound: off the northern coast of Poland, just beyond the horizon, 233 giant turbines – each almost as tall as the Eiffel Tower – are about to rise from the sea floor. With German rotors, foundations designed in Denmark, and cables from Poland and Greece, they will be towering symbols of European manufacturing excellence and industrial might. As the latest additions to an already vast Baltic fleet, they are creating thousands of jobs across the supply chain; and when they are operational, they will supply an additional 5.5 million households with clean energy.

Producing energy made in Europe, by Europe, for Europe, Poland’s offshore wind farms are as important strategically as they are economically. They add to a buildout of clean power that is happening across the continent from Italy in the South to Ireland and Lithuania in the North. Cables and interconnectors – enough to wrap the Earth many times over – are being laid to link the windy northern seas with the sunlit Mediterranean coastline, creating a superhighway for the age of electrons.

An investment revolution is underway
Meanwhile, cutting-edge fibre-optic sensors pioneered by Dutch innovators will be watching over the seabed to protect Europe’s critical infrastructure. New constellations of satellites developed in Belgium will offer enhanced surveillance capabilities from space, alongside cutting-edge radar systems from France and Spain. And all these systems will be connected by AI-powered 6G networks developed in Finland.

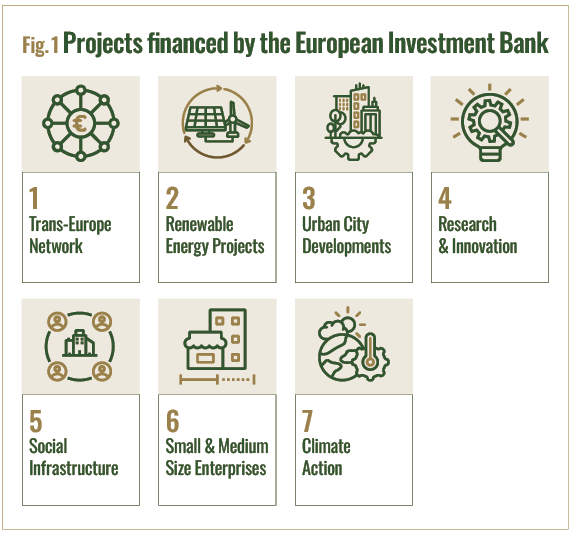
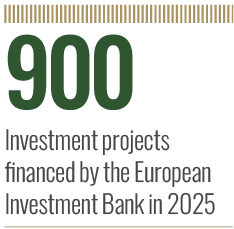
These are just a few of the nearly 900 investment projects financed by the European Investment Bank Group last year alone (see Fig 1). By leveraging EU budget guarantees to mobilise private investment, the EIB Group is powering the unfolding energy and technological revolutions. The transition into tomorrow’s world is already in full swing in Europe – a major development that remains overlooked amid rapid geopolitical change.

In fact, the overall investment in the EU’s energy transition reached a new record in 2025, approaching €400bn – from hydropower in Austria to new railways in Czechia, and from energy efficiency upgrades by small businesses in Croatia to clean technologies deployed by heavy industries in Portugal. Just in the past year, the combined market capitalisation of European renewables companies has risen by over 50 percent. Something that many thought impossible in the near term is already happening – Europe is irreversibly weaning itself off Russian gas.

European investments in defence are increasing even more rapidly. European defence stocks have tripled in value in the past three years. Europe’s industrial production capacity now exceeds even that of the US in critical areas, including artillery shells. Europe is moving by leaps and bounds into strategic sectors and technologies such as drones.

A new venture-capital ecosystem geared toward pioneering security and defence enterprises has emerged almost overnight and essentially from scratch.

A continent reshaped by disruption
We have seen a similar mobilisation before. In 2020, no one expected that a European biotech company would pioneer a vaccine against an unknown virus in a matter of months, helping the world defeat a once-in-a-century pandemic. Nor did anyone think that European leaders would launch a massive recovery and resilience programme financed by joint debt – an unprecedented show of solidarity and unity. When Russia’s full-scale invasion of Ukraine caused a massive spike in energy prices, everyone assumed that the European economy would buckle. Instead, the eurozone’s GDP grew faster than China and the US that year.

In the face of trade warfare, intense market volatility, and shifting traditional partnerships and alliances, European companies have proven resilient, not only diversifying their trade flows but also maintaining strong growth and investment. European stock markets ended up outperforming US exchanges in 2025, rewarding investors who put their trust in our economy. Unemployment is hovering near record lows, and growth is picking up – thanks to high-performing countries such as Spain and Poland. Europe has emerged as a beacon of stability in an uncertain world.

Time and again, the EU has adapted and reinvented itself in the face of crises, leaving it well prepared to navigate a tempestuous geopolitical environment. An export powerhouse, the EU is home to world-class universities and research centres, as well as a vibrant start-up ecosystem. Opinion polls show record levels of public support for the EU and the euro, and global surveys indicate that majorities around the world see the EU as a great power on an equal footing with the US and China.

European stock markets ended up outperforming US exchanges in 2025

They are right to do so. With a $22trn economy, a vast single market of nearly a half-billion people, and plans for another wave of enlargement, Europe’s weight in the world is undeniable. It may be a different kind of superpower, one that prizes values, rules, and multilateralism over sheer might. But its power lies in its commitment to principles and willingness to back its partners and allies, as demonstrated by its status as the biggest source of financial and military assistance to Ukraine.

Europe continues to build bridges in a world of walls. It is the world’s leading trade power, residing at the centre of a vast, ever-expanding network of free-trade agreements. It is also an investment superpower that promotes shared prosperity around the world. As the biggest source of humanitarian aid and development finance, Europe funds everything from global vaccination campaigns to projects to improve water supplies in Amman and Karachi.

We do so because we remain committed to the same values that brought us this far. European unification started nearly eight decades ago from the ashes of two world wars. Our parents and grandparents learned from the tragedies and mistakes of that dark era, and we can draw inspiration from their example to shape a better future for ourselves and others around the world. Ours is a society based on inclusion, equality of opportunity, intellectual freedom, peace, and the rule of law.

We know what needs to be done to preserve this way of life. We need even deeper integration, including our capital markets. We need even more large-scale investment in critical infrastructure and strategic capabilities. We need simplification to make the EU more agile and efficient. And we need more win-win partnerships and alliances to diversify our supply chains and open new markets for our goods. Momentum is building in all these areas. European leaders’ minds are focused, and we are determined to capitalise on Europe’s strengths as the world’s underappreciated superpower.

The mispricing of war

In the space of just a few weeks, the throttling of shipping traffic through the Strait of Hormuz has revealed the true nature of the US-Israeli war with Iran. This is no regional conflict, because the entire world is being invoiced. While the size of the bill remains to be determined, it is already obvious that the belligerents won’t be the only ones paying the tab. War is typically framed in terms of national security, territorial integrity, humanitarianism, or even civilisational struggle. But such rationales obscure an unsettling truth: war is one of the most mispriced of human activities. Those who initiate it rarely bear the full costs, which tend to be displaced across borders, markets and time. Beyond the physical destruction, war generates massive negative externalities. The price paid by the perpetrator reflects only a small fraction of the social cost.

Of course, the intuition that war imposes downstream costs on others is deeply embedded in the political-economy literature, running from Adam Smith and David Ricardo to John Maynard Keynes and Karl Polanyi. But globalisation has transformed the effect into a structural feature of the modern economy.

Economic growth diminishing
Consider the arithmetic of the current Iran conflict. Beyond the loss of life, direct US military spending may run into the tens or even hundreds of billions of dollars. Yet the broader economic cost – transmitted through energy, food and financial markets – runs far higher. The International Monetary Fund warns that the war is already diminishing many economies’ growth prospects, as energy shocks ripple outward and inflationary pressures intensify.

The transmission mechanism is brutally simple. When oil and gas prices rise, transportation and electricity become more expensive. When fertiliser costs increase, so do food prices. Central banks may respond by assuming a tighter monetary-policy stance. Ultimately, growth slows. Yet this domino effect is missing from the actual war ledger. Efforts to measure the true costs of war have consistently found that they lie beyond the battlefield. In their work on the Iraq war, Joseph Stiglitz and Linda Bilmes tallied a catalogue of costs in the trillions of dollars once macroeconomic effects were included. Similarly, both the IMF and the World Bank have found that violent conflict depresses growth in economies far removed from it.

Even under conservative assumptions, the US may bear only a modest share of the total global economic damage (much as the negative spillovers of the war in Ukraine far exceed the direct cost to Russia). As European Central Bank President Christine Lagarde recently cautioned, the rest is diffused across the system, absorbed by energy importers, emerging markets and households worldwide. War, in this sense, is globally subsidised.

Three mechanisms make this possible. The first is spatial. Modern economies are deeply interconnected. When war disrupts one node (particularly an energy chokepoint), the effects cascade outward. The Strait of Hormuz is not simply a geographic passage but a structural vulnerability in the global economy.
The second mechanism is temporal. War typically requires the present to borrow from the future. Governments finance conflict through debt, deferring its cost to generations not yet politically represented. The fiscal consequences of past wars continue to unfold decades later, showing up in public debt, constrained policy options, and obligations that outlast the politics that created them.

The third mechanism is distributive. War concentrates decision-making while dispersing the costs. Those who decide are not the ones who pay. This last insight lies at the heart of modern conflict economics. The Oxford University economist Paul Collier has shown that wars persist not because they are collectively rational, but because they are privately beneficial. Small groups capture the gains as the broader population absorbs the losses. Today’s networked economy amplifies this asymmetry.

When the world pays the price
As Edward Fishman of the Centre on Global Energy Policy argues in his book Chokepoints, power today flows through global systems such as energy routes, financial networks and supply chains. But conflict turns these into channels for economic contagion. The result is a peculiar inversion. War appears expensive in theory but affordable in practice, because much of the bill is paid by others. This mispricing has predictable consequences. When goods are subsidised, we get more of them. When their price is too low, we get oversupply: too much pollution, too much risk and too much war.

The policy challenge is therefore familiar, even if the politics are not: to discourage war, its costs must be internalised. Those who initiate conflict must bear a greater share (or, even better, the entirety) of its true costs. Ensuring that outcome requires an effective global institution that can align the private and social costs of conflict more effectively than global markets can. Until the world can come up with such an institution, the incentives will remain perverse, because one of the most destructive activities imaginable seems so affordable to those who undertake it.

Toronto’s condo crisis and the failure of economic forecasting

Those familiar with the British sit-com The IT Crowd, which was about workers in the IT department of a firm, and premiered in 2006, will remember the catchphrase “Have you tried turning it off and on again?” which was their go-to response for any technical computing problem. A similar technique is currently being applied to the real estate sector in Canadian cities such as Toronto, especially for the market for new condominiums (or condos).

For the last decade and more, Toronto has been the construction hub of North America, its skyline studded with more cranes than any other city. Underlying all this activity was the unquestioned belief among investors that real estate was a safe investment. This was the case even during the Great Financial Crisis (GFC), which the Canadian economy endured quite well, in part because banks did not resort to the same complex financial derivatives as did their counterparts in the US. After the briefest of dips, house prices showed explosive growth, doubling over the next 12 years and almost tripling by the time they reached their glorious peak in 2022.

Usually this growth was attributed to demand from an expanding population, which fits with the traditional view that price rises are typically driven by excess demand. In reality, the number of houses being sold was fairly static. The only kind of property that was selling like hot cakes was the kind that didn’t actually exist: pre-construction condos.

Boxes in the sky
Often these were ‘shoebox’ apartments that were intended more as an investment than a place to live, and represented a kind of futures bet on the market. The majority were purchased by investors, who could put down a small deposit before construction began, and expect to sell at a profit just before completion to an end-user or another investor. Mainstream economists saw no problem with this because on the surface it seemed the economy was doing well. The central bank cut interest rates to the bone, since according to their metrics, which didn’t account for house prices, inflation was quiescent.

The deterministic models of the past are giving way to new approaches that embrace uncertainty

When official inflation jumped in the post-Covid years, interest rates bounced off their lows. Mortgages suddenly became more expensive. Population growth, which was almost entirely due to immigration, which peaked at around 3.2 percent in 2022, compared to an average 0.5 percent for G7 countries, was suddenly thrown into reverse, with Canada actually reporting a small decline in 2025 for the first time on record. The real estate market on the whole adjusted to these contortions with a decline in both sales and prices. But the market for pre-construction condos didn’t adjust – it just stopped.

In December 2025, only 87 pre-construction units were sold across the entire Greater Toronto Area, which has a population of about 7.8 million. That is the lowest single-month total in the 45 years that data has been tracked. Developer activity also ground to a halt, with just 10 new condo projects launching throughout the entire year, compared to the dozens typical in a healthy market. Remaining new home inventory hit a record high equivalent to over two years of sales. And in the first quarter of 2026, things really iced up, as zero new projects were launched. There is a sense though that this reset is about more than just pre-construction condos – it is about how we think about the economy.

Tail events
The GFC was a crisis not just for the economy, but also for the field of economics. Not in the sense that economists actually lost their jobs, but because their models failed. Economists had long assumed that probabilities could be described by a so-called normal distribution, or bell curve as it is sometimes known.

However, risk models based on this assumption quickly broke down when it turned out that so-called tail events had a much higher chance of occurring than the model suggested. And mainstream economics, which was based on the idea that the economy is a rational, efficient, self-stabilising system – which is immune to things like booms and busts – was thrown into a state of complete crisis along with the economy.

While the field of economics is famously resistant to change and new ideas, a couple of decades later, things do show signs of moving on, at least in some corners of the profession. In their recent book Adaptive Finance: Embracing Uncertainty and Complexity, economists Frank Fabozzi and Sergio Focardi write that “The need for models predicting tail events and market anomalies has become increasingly apparent after the GFC.

“Traditional models, which often rely on normal distributions and the assumption of efficient markets, could not predict the extreme events that characterised the crisis, such as the collapse of major financial institutions and the sudden freeze in credit markets.”

It is no surprise that in the “new paradigm in economics and finance” described by Fabozzi and Focardi, “the deterministic models of the past are giving way to new approaches that embrace uncertainty.” As another market freezes up in front of us, it is past time for economists to embrace these new insights. Instead of just saying, “Let’s try turning it off…”

A new blueprint for real estate investment

As the global real estate market enters a long-awaited inflection point in 2026, institutional players and private capital are finally returning to the field, signalling a shift from stagnation towards a new cycle of valuation and growth, according to the latest market outlook from Morgan Stanley. Yet, as commercial real estate investment activity is forecast to rise significantly this year, investors are being forced to rethink how they deploy capital in an environment still marked by dislocation and selectivity, as noted in the US Real Estate Market Outlook 2026 report by CBRE. For those looking beyond the headline-grabbing institutional deals, the most compelling opportunities are increasingly found in the middle market, where the inherent complexity of the asset often serve as a natural, protective barrier to entry for larger, more rigid competitors.

Middle market advantage
The middle market remains the largest segment of the investment landscape, structurally resembling a pyramid in which the vast majority of opportunities lie at the smaller end. It is also where inefficiency persists, and where opportunity follows. Our strategy is intentionally contrarian, focusing on deals under $50m, a segment where access to capital, particularly at this stage of the recovery cycle, is more limited. As a result, pricing dislocations tend to be more pronounced. In this space, we often find great properties with complicated histories, capital stack challenges, leasing gaps, or simple management fatigue. Unlike large institutions that must wait out long market cycles, many sellers here are driven by urgent liquidity needs or personal circumstances rather than strategic timing.

Compelling value is emerging in overlooked or dislocated asset classes

They typically cannot wait out market cycles, which further contributes to attractive entry points. This creates a fertile opportunity to acquire high-quality assets well below replacement cost, allowing us to address specific operational issues and create substantial value that is fundamentally independent of broader macro conditions. At the same time, middle-market activity is increasingly led by well-capitalised local operators who have a deep understanding of their submarkets. That local expertise, combined with disciplined capital, is a powerful advantage in identifying and executing opportunities others may overlook.

Alongside these market dynamics, family offices are undergoing a significant structural shift. Many are moving away from traditional stock-and-bond allocations to increase exposure to real assets. Driven by the need for income stability, inflation protection, and tax efficiency, families are moving beyond fragmented, indirect fund structures to build direct, intentional real estate portfolios.

Historically, access to real estate has been constrained by institutional fund structures or by fragmented direct investment opportunities that were difficult to scale. Today, more families are seeking direct, intentional exposure to the asset class. The appeal is clear: durable income streams, depreciation benefits, and the ability to exert more control over outcomes in an increasingly uncertain environment. In this landscape, relationship-first investing has become a critical differentiator and ensuring that capital is aligned with the family’s specific tax, income, and legacy-building objectives.

Beyond traditional core markets, compelling value is emerging in overlooked or dislocated asset classes. At the same time, we are seeing significant opportunities in the office sector, an area many investors have prematurely written off. In primary hubs like New York, Northern California, Houston, and San Diego, high-quality assets are trading at steep discounts, sometimes near land value. By targeting these dislocated areas, investors can capitalise on mispricing that others either lack the local expertise to identify or the operational discipline to execute upon effectively.

Navigating a bifurcated market
Today’s market can sometimes be a ‘feast-or-famine’ environment. Assets that align with modern tenant demand continue to perform, while those that do not struggle regardless of price. This makes underwriting more nuanced than ever; a 30–50 percent discount is often insufficient to offset functional or locational obsolescence. When that distinction is made correctly, today’s environment offers a rare opportunity to acquire quality assets at historically attractive bases. Conversion and repositioning strategies are also gaining traction, particularly in large, dense markets where supply-demand imbalances are most acute. These markets benefit from higher land values and stronger tenant demand, both of which support redevelopment economics.

Opportunity in real estate has not disappeared; it has simply shifted. Success in this cycle will depend on a blend of discipline, creativity and conviction. Investors who can navigate complexity, lean into long-term relationships, and act decisively in inefficient parts of the market will be best positioned to generate durable, risk-adjusted returns.

The next era of cross-border payments

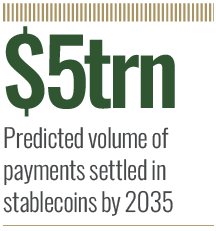
The painfully slow process of moving money across borders has stalled businesses for decades. The TradFi route is not fit for purpose but has been tolerated until recent years because no credible alternative existed at scale. According to Oliver Wyman, businesses collectively pay $120bn a year to move money across borders. Until the creation of stablecoins, moving money internationally meant waiting days for settlement, losing margin to FX spreads you cannot see or predict, and routing payments through intermediaries that add cost and time at every step. Now, Juniper Research is forecasting that cross-border B2B payments settled in stablecoins will reach $5trn by 2035.

This is less a prediction than a consequence of a broken cross-border banking system. At first glance, $5trn seems an extraordinary figure, but it reflects how enterprise demand is finally being met by infrastructure and regulation. The advantages of stablecoin payments over traditional cross-border rails are tangible. Payments move 24 hours a day, rather than on banking schedules, and settlement takes seconds rather than days. Payment terms can also be programmed and automated.

For businesses already on stablecoin rails, the efficiency gains are measurable – EY-Parthenon’s research also shows that there is further demand for wider industry support as 81 percent of corporates say bank support for stablecoins is critical or important. Juniper Research’s near 400x projected growth for the industry makes a lot of sense when you consider that the market is still at its earliest institutional stage. A sharp increase in the value of cross-border payments will naturally follow high demand and the right conditions for adoption.

The bottleneck was never demand
While stablecoins seem new and shiny to some, enterprise interest has existed for years – but the industry was missing the infrastructure and regulatory certainty that is necessary for commitment. Across the US and Europe, regulation is either progressing or falling into place. Last year, we saw the GENIUS Act pass in the US and, right now, the CLARITY Act is being debated in the Senate. The Markets in Crypto-Assets Regulation (MiCA) is live in Europe – over 40 Crypto-Asset Service Providers have been licensed as of March 2026.

If demand did not exist, financial institutions would not be investing

The market has crossed a commercial threshold. Landmark moves by major players have also signalled the shift from speculative use toward institutional payment infrastructure: Klarna recently built its own dollar-pegged stablecoin and Western Union committed to launching a stablecoin on Solana. Juniper predicts that 85 percent of all stablecoin transaction value in 2035 will come from international business-to-business activity. The direction of travel is clear – if demand did not exist, financial institutions would not be investing.

How to get adoption to skyrocket
For businesses with serious cross-border payment operations, the question has evolved from whether to implement stablecoin rails to which provider they trust to run them. The decision is harder than it sounds. In Europe, the MiCA grandfathering deadline of July 1, 2026 will mean providers without full authorisation must cease European operations from that date, with no grace period. But regulatory status is a baseline, not a differentiator. What separates credible infrastructure from everything else is whether it has been built to perform at enterprise scale: high transaction volumes, multiple jurisdictions, compliance across regulatory frameworks and integration with existing financial operations.

Confirmo Limited is authorised from the Central Bank of Ireland under both MiCA and as a Payment Institution under the Payment Services Regulations 2018 (PSR), covering the full stablecoin payment transaction lifecycle within a single regulated entity. More than half of enterprise non-users expect to adopt stablecoins within six to 12 months according to EY-Parthenon, and the providers ready to meet that demand are the ones who built the infrastructure before the forecasts made it look obvious.

The cross-border payments system has been extracting cost and time from businesses for decades. Stablecoins are not disrupting a system that works – they are replacing one that doesn’t. With regulatory frameworks now live across the US and Europe and the institutional capital flowing into payments infrastructure, the conditions for adoption at scale have finally arrived. The businesses that move now, while infrastructure is being built and competitive positions are still being established, will define what cross-border payments look like for the next decade.

How AI is reshaping corporate governance

As artificial intelligence becomes embedded across every aspect of business, many organisations are understandably focused on the productivity gains the technology promises to deliver. Boards, too, are exploring how AI can streamline governance processes and help directors absorb information more efficiently. In a business environment defined by intense competition, geopolitical uncertainty and growing complexity, the appeal is obvious. Yet in my conversations with directors and executives over the past year, it has become clear that AI is forcing boards to confront a deeper issue – whether current governance models are genuinely equipped for the pace, complexity and uncertainty organisations now face. They are asking fundamental questions about how AI may reshape leadership itself – how decisions are made, how judgement is exercised, and whether boards are equipped for the pace and scale of change now taking place.

This matters because boards are already operating under considerable strain. As regulatory expectations and stakeholder scrutiny have increased, board packs have grown longer and agendas more crowded. Directors often describe evenings and weekends spent wading through hundreds of pages of pre-meeting material, only to leave the meeting feeling dissatisfied because insufficient time was spent discussing the issues most likely to shape the organisation’s future. Directors are expected to oversee an extraordinary breadth of issues, ranging from cyber risk and sustainability to workforce transformation and geopolitical instability, often with limited time and incomplete information. The result can be a form of cognitive overload in which boards become highly effective at reviewing detail, but less effective at creating space for strategic debate and meaningful challenge.

New categories of risk
AI offers an opportunity to reduce some of the administrative burden that has accumulated around governance over the past decade. But it also introduces entirely new categories of risk and complexity for boards. Unlike previous waves of enterprise technology, AI does not sit neatly within a single function – it influences hiring decisions, customer interactions, compliance and competitive strategy simultaneously, while also changing how organisations themselves process information and make decisions.

Governing AI therefore requires a different kind of conversation from the one many boards are used to having. It demands a more interdisciplinary, dynamic and forward-looking approach, as well as a greater willingness to interrogate assumptions and challenge consensus. The most effective boards are rarely those that simply move fastest. More often, they are the ones that can also sustain high-quality discussion under pressure, creating environments where alternative perspectives are surfaced early and where directors remain willing to question both the information presented to them and the reasoning behind it. This is precisely why some organisations are beginning to experiment with AI not simply as an administrative assistant, but as a strategic sparring partner for the board itself. Last month, Board Intelligence partnered with Lloyds Banking Group to explore how AI could help executives and directors interrogate assumptions, identify gaps in reasoning and surface perspectives that might otherwise be overlooked ahead of high-stakes discussions. One director described the experience to me as being less like using a chatbot and more like having access to an additional perspective in the room, one capable of challenging logic, highlighting blind spots and encouraging deeper scrutiny before decisions were made. The objective was not to replace human judgement, but to strengthen it.

Faster isn’t better
That distinction is important because much of the first generation of ‘AI for boards’ has focused primarily on precisely the opposite. While AI’s automation and summarisation capabilities undoubtedly save time, a weak board paper summarised by AI is still a weak board paper. Faster processing of information does not produce better judgement. The more exciting opportunity lies in augmentation, using AI to improve the quality of challenge, broaden perspectives and create more space for thoughtful discussion around the board table. This only works if boards resist the temptation to treat AI purely as a time-saving tool.

Governance has always depended on deeply human qualities that technology alone cannot replicate – curiosity, scepticism, integrity and the confidence to challenge consensus when necessary. If AI merely accelerates boards’ existing weaknesses, whether that is overconfidence or a reluctance to challenge prevailing views, then faster governance may simply become less effective governance delivered at greater speed.

As the outlook for growth falters and disruption intensifies, the quality of a board’s judgement will become a far greater competitive differentiator than it has been historically. The boards that benefit most from AI won’t be those that rely on it for answers, but those that use it to ask better questions, challenge assumptions and sharpen their thinking.

Business schools and the leadership divide

Despite decades of diversity rhetoric, women remain markedly under-represented in business school leadership. Based on schools participating in our yearly survey, AACSB’s most recent data shows women comprise 41.8 percent of tenure-track faculty, 27.1 percent of full professors and 29.8 percent of deans. While these numbers have steadily increased over the years, there is still meaningful progress to be made in advancing the representation of women within business schools.

As institutions responsible for shaping inclusive, globally minded leaders, business schools have a duty to reflect those values in their own faculty. Students benefit most when they are taught by educators who represent the demographics and realities of the business world they will enter after graduation.

The challenges are multifaceted, spanning limited career pathways, persistent work-life balance pressures, and a lack of mentorship to develop the skills needed to progress into leadership roles such as dean. The data show that the drop-off doesn’t happen at entry; it happens on the path to leadership. Women are well represented in early academic roles yet remain significantly under-represented at professor and dean level.

This is not a pipeline issue, it is a progression issue, where capable leaders are not advancing at the same rate as their peers. Insights from business school deans reinforce why this matters. Leadership is not symbolic, it directly shapes institutional direction, from strategic priorities and resource allocation to culture and innovation.

The barriers are well understood. Entrenched networks, uneven access to sponsorship, and evaluation systems that reward traditional leadership profiles continue to slow advancement. At the same time, leadership itself is evolving. Deans point to the growing importance of adaptability, collaboration, and inclusive decision-making, capabilities that are strengthened through diverse leadership teams. When women are not advancing, business schools are not just missing representation; they are missing out on critical leadership capacity. The risk is strategic.

Schools that fail to fully leverage their talent risk weaker decision-making and a diminished ability to prepare graduates for a global, interconnected economy.

Leadership without trade-offs
One of the most persistent barriers to women’s advancement in business school leadership is not capability, but sustainability. The path to leadership has too often been shaped around expectations that leave little room for life outside of work, making it harder for many talented women to see themselves – or remain – on that path.

Insights from deans highlight that the role itself is becoming more complex and demanding, requiring constant availability, high visibility and significant personal investment. Without more flexible and human-centred approaches to leadership, institutions risk narrowing their own leadership pipelines by unintentionally excluding those who cannot, or choose not to, meet these expectations. Addressing this challenge starts with redefining what effective leadership looks like.

Women can lead at the highest levels and maintain full lives outside of work. There are practical steps that can make this a reality. More flexible leadership models, clearer expectations around workload, equitable parental and caregiving policies, and stronger support systems can all help ensure that leadership roles are accessible and sustainable. Transparency around career pathways, making those in the selection process aware of potential unconscious bias, and open conversations about balance also play a critical role in changing perceptions about what leadership requires. When business schools make space for both, they expand their talent pool, strengthen their leadership, and model the kind of inclusive, sustainable workplaces they seek to promote.

In an Insights from Deans report by AACSB in February 2024, we learned that 42 percent of first-time deans desire more mentorship coming into the role. AACSB heard this feedback and created the ‘Dean’s Journey’ in our AACSB Academy. This cohort-based programme, developed by business school deans, gives insights from experts, peer-to-peer connection, and preparation to lead. Across the first two cohorts, the participants are 45 percent female.

We are unlocking new paths for women to feel comfortable in their leadership abilities to continue taking the next step in their careers. AACSB is not just identifying the problem; we are taking steps to bridge the gap. As we see graduates come from our ‘Dean’s Journey’ programme, we are encouraged this will have a direct impact on bringing more women into business school leadership.

A call for accountability
The evidence is no longer in question. The talent exists, the ambition is present, and women across business schools are already demonstrating the capability to lead at the highest levels. Empowering women to lead means more than opening doors: it requires actively equipping them with the opportunities, networks, and confidence to step into leadership and shape the future of business education. It also means recognising and valuing diverse leadership styles that strengthen institutions.

Progress depends on sustained commitment, shared accountability, and a willingness to challenge long-standing norms that have limited leadership pipelines. The direction is clear. What matters now is ensuring that more women are not only prepared to lead but are empowered to do so.

Beer’s next growth story

In supermarket aisles and across pubs, bars and restaurants today, lower- and no-alcohol options are becoming staples of the modern drinking landscape. Consumers are embracing moderation and driving the rapid expansion of the lower- and no-alcohol beverage market. For consumers seeking a lower- or no-alcohol drink, beer is the obvious choice.

With a lower alcohol content than most beverages in the category, beer is moderate by nature. Typically sold at or under five percent alcohol by volume (ABV), a beer contains significantly less alcohol than say, a Negroni, Martini or Old Fashioned, which are made with hard liquor at 20–30 percent ABV or more, or a glass of wine at 12 percent ABV.

But a beer is still a beer no matter how much alcohol it has. A unique interplay of malted barley sweetness, hop bitterness and yeast esters during fermentation make up the character of a beer, and brewers preserve this character in their lower- and no-alcohol alternatives in a way few other beverages can achieve.

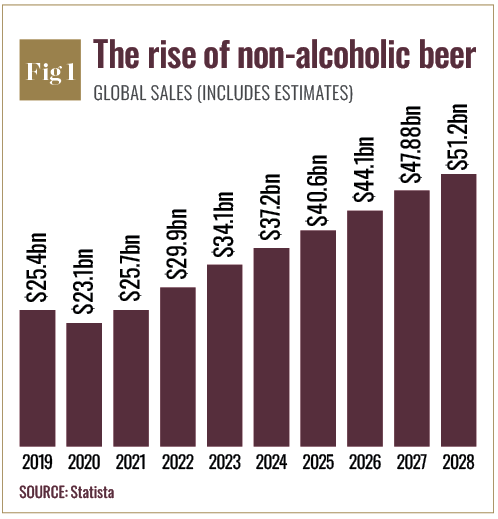
The global beer industry is uniquely positioned to deliver on the cultural shift towards moderation that we are seeing today, and brewers around the world have risen to the occasion (see Fig 1). IWSR forecasts no-alcohol beer and cider will contribute nearly 70 percent of the overall no/low-alcohol growth between 2022 and 2026, while a report from the European Commission reveals beer and cider make up 97 percent of the EU’s lower and no-alcohol market.

Industry aligned to economic priorities
Today’s moderate drinking landscape has obvious benefits for policymakers’ public health objectives too. Substituting high-alcohol beverages, like hard liquor, with lower-alcohol options, like beer, is a time-tested, evidence-based way to improve public health outcomes.

A comprehensive study on the impact of alcohol policies in Russia by WHO Europe found policies shifting consumption away from high-strength alcohol beverages towards lower-alcohol beverages were associated with improving multiple public health indicators, while a study by the Portman Group revealed one in five (21 percent) of consumers in the UK who drank alcohol said their weekly consumption had decreased since first trying lower- and no-alcohol alternatives.

The beer industry also supports thriving communities. While many global industries can tout big contributions to global GDP, the beer industry lifts up local economies in a unique way. 86 percent of brewers’ supplier spending is in local markets. From hops and barley farmers to trucking companies to hospitality, beer is the backbone of a robust and varied value chain. The productivity of those employed by brewers is also significantly higher than the average worker, driving economic growth and income opportunities, particularly in developing nations. Oxford Economics found brewers generate $117,000 of GDP per worker in lower-income countries, more than 18 times the average.

Policymakers can ensure the beer industry continues to deliver positive outcomes

But a thriving community is about more than just economics. Pubs, bars and restaurants are at the heart of our communities, providing a positive space for people to come together, connect and create shared experiences in a tradition that dates back thousands of years. A strong beer industry is vital to prolonging the life of these businesses, which sit at the core of local communities around the world. Now that lower- and no-alcohol beers are available in most local establishments, the beer industry has helped make pubs, bars and restaurants more inclusive than ever before, as customers can still enjoy the custom of sharing a beer – and the individual, social and community benefits it brings – with or without alcohol.

Policymakers can support this industry
Beer supports positive public health outcomes, strong economies and thriving communities. And the regulatory environment can support the industry to do even more. We are calling for policymakers around the world to regulate alcohol according to beverage type and strength, which would encourage the production and consumption of lower alcohol-strength products like beer. Many OECD countries are already leading the way by applying lower excise tax rates to beer than to hard liquor and offering even lower rates for lower- and no-alcohol options.

By creating a supportive regulatory and fiscal environment for brewers to do business, policymakers can ensure the beer industry continues to deliver positive outcomes to local communities around the world.

The new gatekeeper of global finance

I returned from Paris last month, having spent three days in rooms where the future of global finance was being quietly debated. Not by politicians, but by fintech executives, institutional investors and regulatory architects who are actually building it. What struck me most was the unanimity of the anxiety beneath the sophisticated technology on display. Operators from São Paulo to Singapore and from Dubai to Ho Chi Minh City all wanted US market access, but few knew how. That gap is about to narrow partially, creating both opportunity and risk.

For the better part of a century, US financial dominance rested on three interlocking pillars: the dollar’s status as a reserve currency, the depth of its capital markets, and an institutional infrastructure so entrenched that it became the default architecture for global trade. You did not choose to work within the American financial system. You simply did, because there was no viable alternative. Now, blockchain commoditises rails, replicates tokens and allows exchanges anywhere. The regulatory standard – the enforceable, globally legible rulebook – is the differentiator. This is what the Clarity Act aims to provide.

The Clarity Act’s global stakes
The Genius Act brought stablecoins under regulatory supervision and set reserve requirements for dollar-pegged digital currency. But it left most of the digital asset market – securities, commodities, DeFi, tokenised treasuries – in a legal grey zone, costing US and global enterprises billions in missed opportunity and confusion.

Compliance, executed well, is no longer a constraint on growth. It is the competitive advantage

The Clarity Act changes this. For the first time, US law will draw a definitive line between a digital security and a digital commodity, clarify the respective jurisdictions of the SEC and the CFTC, and create a coherent framework for exchanges, broker-dealers, and custodians. Crucially, it gives every enterprise outside the US – the Brazilian fintech, the Vietnamese payment company, the Dubai-based digital asset fund – a clear set of rules to align with before approaching a US institution.

In Paris, the reaction was not scepticism; it was relief. The demand for US market entry is profound. What has been missing is a door with a handle. American dominance won’t mean a monopoly. The EU’s MiCA, the UAE’s VARA, and Singapore’s MAS all offer a strong, attractive regulatory environment.

The US will win the battle for regulatory dominance as the Clarity Act will become the template other jurisdictions align with, because alignment means access. What American policymakers may cede is the battle for product innovation: the applications and platforms incubated in jurisdictions with lower friction and greater appetite for experimentation. This is not failure. It is a division of labour, one that must be accepted, because attempting to suppress innovation to protect legacy systems has already been tried. The market moved anyway.

The call to act, before the window closes
For every enterprise navigating this landscape, the imperative is not strategic; it is existential. Non-compliance does not look like a fine. It looks like paralysis: misaligned controls, transactions held or rejected while competitors move, credibility bleeding out at precisely the moment this market is accelerating. You are not paying a penalty; you are stuck, while deep-pocketed US investors onboard with your better-positioned rivals. They will not wait. There are other doors to knock on. The enforcement trajectory is unambiguous. In 2023, Binance paid $4.3bn, the largest Department of Justice corporate resolution in history at the time. In 2024, TD Bank settled for $3.1bn, becoming the largest US bank to plead guilty to a money laundering conspiracy. Even Revolut, celebrated as a model of fintech agility, was fined €3.5m for failures in transaction monitoring. These are not outliers. They are a pattern with a clear, accelerating direction of travel.

Over three decades of building technology for global financial institutions, I have watched compliance treated as a cost centre, an afterthought, and checked only after the deal closes. In the digital asset era, that model is obsolete. It is the single biggest differentiator separating institutions that will capture this market from those locked out of it. Compliance, executed well, is no longer a constraint on growth. It is the competitive advantage.

Do you know, before you transact, whether you are compliant? If the answer is anything other than an unequivocal yes, the window to fix that cheaply is closing faster than most people in Paris were willing to admit.

Could Universal Studios and Puy du Fou Transform UK Tourism?

Almost 50 years ago, Philippe de Villiers gathered together hundreds of volunteers to create Cinéscénie, a live-action re-enactment of history and folklore from his part of France, a region called the Vendée. Quite unlike the ‘liberté, égalité, fraternité’ motto that accompanies the revolution in a lot of France, in the Vendée region it was received with little enthusiasm, and in the process of uprising its inhabitants died in their thousands. De Villiers wants this recognised, which is partly what led him to create a large-scale performance, to ensure the story was told to future generations. Not a typical start to a fantastical theme park.

From its founding in the 1970s, that single re-enactment has grown into ‘the world’s biggest night-time show,’ and its home park a provider of dozens of eye-popping performances – world class in every sense of the word. Its name is Puy du Fou.

A leader in performance, spectacle and indeed customer experience, Puy du Fou is second only to Disneyland Paris as the biggest theme park attraction in France. It is a multi-million-pound business and tourism model, and it is currently under consultation to come to the UK.

There are two Puy du Fou parks already: the one in France founded in 1978, and a newer one in Spain since 2021. Both provide immersive, multi-award-winning, genuinely world-class shows telling famous historical legends and stories of the local area and beyond. When I say world-class, I mean it – Puy du Fou productions have won international awards for best shows; not best theme park shows, best shows. Their technical prowess and spectacle are preposterously good. The scale of them is life size or bigger – think exploding Viking ships and life-size castles appearing from nowhere. Visiting a Puy du Fou is a whistle-stop tour through famous and not-so-famous events in history, presented to spectacular effect.

Know your audience
The UK Puy du Fou consultation is being run with Cherwell Council in Oxfordshire, inviting perspectives from local people and businesses. Naturally there are objectors, but it would seem unlikely that the council will turn down the level of investment on offer, not only financially speaking but also in terms of regenerating the local environment. It sounds surprising but Puy du Fou evidence an improvement to the local environments of their parks in terms of site choice, tree planting, and biodiversity, delivering a net gain to the local environment. It is a pretty watertight and persuasive consultation package, having had 50 years of learning from their existing two parks, but the reality is that the council will only approve the park if it is felt to be financially and politically viable to develop this sort of attraction in their part of the UK.

It is a multi-million-pound business and tourism model

Interestingly, the proposed Cherwell site is within easy reach of Bicester Village, the second biggest tourist destination in the UK (after Buckingham Palace) for wealthy Chinese tourists. Indeed, the massive designer outlet hosts some seven million visitors every year and the Chinese represent the biggest demographic.

Marketed strongly in Mandarin online, particularly on Weibo, it has easy rail access from London and it is also close to the Cotswolds, which in turn has millions of tourists visiting every year. Make no mistake, there is already an abundance of disposable income in this area. A Puy du Fou, with its niche offering of historical and mythological re-enactments specific to its host country yet a quintessentially British experience, should appeal to international tourists but crucially, British ones as well.

Bringing Hollywood home
Those with a keen eye on the UK tourism industry will also be aware of the public consultation for a proposed Universal Studios to open in nearby Bedfordshire. The consultation website for this park states that a Special Development Order has been granted by the local authority, which ‘represents an important milestone for the project.’

The website itself states that 94 percent of the consultation responses have been in favour of the park; the UK tourism industry has arguably not had such a globally recognised attraction brand launching here since the opening of Warner Bros. Studio Tour London – The Making of Harry Potter, in 2012.

Much more of a classic theme park experience, with rides, rollercoasters, and movie set immersions, Universal Studios is a truly global brand with significant resources and experience that will know its UK market well. It is surely the better known of the two parks in the UK – indeed, Puy du Fou, while being the second-biggest attraction in France, somehow also manages to feel like a very well-kept secret. With the Universal name comes a global reputation it will need to live up to; with multiple stablemates in locations like California, Japan, and Singapore, the Orlando, Florida park is the largest (comprising three separate parks) and has long ranked among the world’s most popular tourist attractions. Attendance numbers have typically shown steady growth, peaking in 2019. The following year, however, brought an abrupt shift as the park faced months of closure and widespread travel lockdowns due to Covid, leading to a sharp decline in visitor numbers from which it has still not fully recovered.

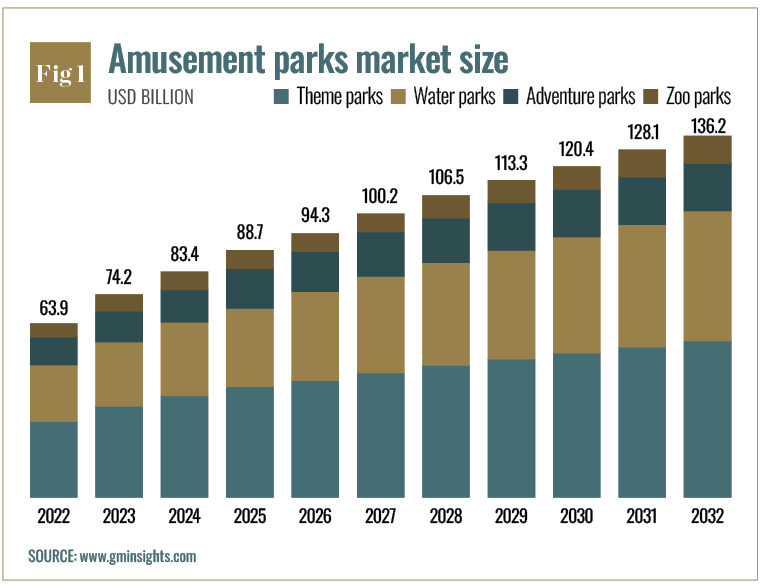
That said, Forbes reports that over a million people from the UK alone visited Florida in 2024 – that figure is still nowhere near pre-pandemic levels, but if a proportion of those visitors could be tempted to stay at home and still have the theme park experience here in the UK, the number may fall further still. Amusement parks are big business and that trend is predicted to continue in the coming years (see Fig 1).

Tradition or ambition?
But what of the quintessentially British experience? Does the UK actually want gigantic theme parks? Perhaps one of the characteristics that makes the UK so attractive to tourists is the typical understated charm of so many of our offerings. Certainly that is what drives many to visit the Cotswolds and places like Devon, Dorset and Cornwall. That olde-worlde British charm feels much harder to come by in the peak of summer, however, and one has only to recollect the frenzied staycations of the lockdown years and the genuinely serious issues with flytipping and mess left behind in overrun beauty spots that simply could not cope with such an influx, to recognise some of the concerns that respondents to the theme parks’ consultations are expressing online.

Social and environmental concerns are being carefully considered and planned for in both consultations, and the parent companies are engaging with local government, community groups, and businesses to assuage fears around everything from firework noise to local employment offers. There are detailed plans for the build phases, the customer experience during visiting hours, and longer term once anticipated peak guest numbers have been reached after opening.

Any large enterprise like a theme park requires enormous numbers of staff, both front of house and behind the scenes, onstage and in the back office. Excitingly, both parks also use actors and performers to enhance the visitor experience. With Puy du Fou especially, this is a central part of their brand, and they have specific career enhancement pathways that enable people to join, say, hospitality, but receive on-the-job training and development to join the ranks of highly skilled performers that make the shows so breathtaking and unique to watch.

Harry Potter Studios, Bicester and Bedford – you can drive from any one of these sites to another in about an hour. That is more than doable from a holiday perspective. When families from the UK visit Florida, it is common to plan entire holidays around the various parks. Big-ticket theme parks here in the UK such as Universal Studios and Puy du Fou could offer UK tourism a complete portfolio of visitor experiences that are well-connected (and hopefully, well thought out) and that could take the UK offering beyond the realms of quaint Britishness and into truly global tourism.

International tourists will keep coming to the UK, but whether the country’s own public has a sustainable appetite for this remains to be seen. With the cost of living continuing to bite more with every passing year, disposable income is not abundant for most UK working families, but perhaps this is in fact a reason for people to get behind projects like Universal Studios and Puy du Fou. Why spend hundreds of pounds on unreliable flights abroad that might never take off given global instability, when you can simply staycation closer to home? Added to the already impressive combination of luxury retail experiences, historical wonders like Stonehenge, and classic British attractions like Buckingham Palace, parks like Puy du Fou and Universal Studios could mean the feeling of being transported to another world might soon happen right on your doorstep.

A job apocalypse?

In 2023, Goldman Sachs estimated 300 million jobs across the world could be exposed to artificial intelligence.

More recently, a separate analysis by the investment bank found that AI could displace six to seven percent of the US workforce if it is widely adopted, while a McKinsey paper found that 30 percent of the hours currently worked across the US could be automated by 2030.

A report by Boston Consulting Group (BCG) meanwhile took it a step further, declaring that “five years from now – or perhaps further in the future – 10 to 15 percent of jobs in the US could be eliminated.” The firm concluded that “remaking the workforce is a competitive imperative.” The shift has been described as the cognitive, white-collar equivalent of the Industrial Revolution.

Major tech firms have already begun making large-scale job cuts while simultaneously pumping large sums into AI. In February, Jack Dorsey announced his fintech firm, Block, would be slashing its workforce from 10,000 to 6,000 people, directly citing intelligence.

“We are already seeing that the intelligence tools we are creating and using, paired with smaller and flatter teams, are enabling a new way of working which fundamentally changes what it means to build and run a company,” wrote Dorsey. “I had two options: cut gradually over months or years as this shift plays out, or be honest about where we are and act on it now.”

In April, Meta announced it planned to cut around 8,000 (10 percent) of its employees to “offset the other investments we are making,” in the words of chief people officer Janelle Gale. Last year, Microsoft made more than 15,000 job cuts while committing $80bn to AI investments. Amazon Chief Executive Andy Jassy has meanwhile said he expects the conglomerate to “reduce its total corporate workforce as we get efficiency gains from using AI extensively across the company.”

But as these firms bet on an AI-driven future with slimmer teams and higher productivity, there are multiple questions; how realistic is this vision, are consumers ready to put their trust in bots, and what might it mean for the future workforce if concepts that were once purely the stuff of sci-fi come to fruition?

All hail the AI agents
Underpinning much of the speculated AI-driven workforce of the future is agentic AI, or AI agents – that is, agents that can act on content produced by generative AI to plan, make decisions and execute tasks. Going beyond the limits of generative AI by taking a more active, human-like role, they can come in digital form – such as chatbots and coding agents – or physical embodiments, including robots, drones and self-driving cars.

AI could wipe out half of all entry-level white collar jobs

These tech-forward ‘agents’ are already making an early-stage appearance; one example is OpenClaw, which launched in November 2025 and, as per its website, “clears your inbox, sends emails, manages your calendar, checks you in for flights. All from WhatsApp, Telegram, or any chat app you already use.” Firms in both the tech sphere and beyond are starting to capitalise on the hype.

In May, Citigroup announced Arc, a new platform that will “allow the bank to build and scale AI agents across the firm,” in the words of a recent statement. “These agents enhance human judgment by taking on tasks such as research, synthesis, preparation and execution, reducing manual effort and accelerating how teams operate day to day,” it reads.

The same month, AI lab Anthropic released a series of new agents (or AI systems) for the financial services industry that can carry out tasks with limited human intervention – including building a pitchbook, auditing statements and drafting credit memos.

JPMorgan is going full steam ahead in its plans for agentic AI. Chief analytics officer, Derek Waldron, told the CNBC last year that in its future vision, “every process is powered by AI agents, and every client experience has an AI concierge.” Amazon chief executive Andy Jassy outlined a similar premonition, declaring in a statement in 2025: “There will be billions of these agents, across every company and in every imaginable field.”

An ongoing need for humans
The general messaging from many experts in the industry is that the rise of these agents would entail a combination of human and AI work, providing workers with more time to do (currently) human-only tasks. “Even as these systems become more capable, it remains critical that humans stay in the loop, setting direction, applying judgment and remaining accountable for outcomes,” Sida Peng, Research Economist at Microsoft, told World Finance.

Even highly skilled and highly valued positions are now under threat

“What that means for the workforce is that people spend less time on repetitive execution and more time directing work, making decisions and managing outcomes across teams of agents and humans.”

It’s not just about automating existing human tasks but augmenting them, according to Peng. “One of the biggest opportunities AI presents is the ability to expand what people and organisations are capable of,” he says. “In our Work Trend Index research, 58 percent of workers said they are producing work they could not have done a year ago, rising to 80 percent among Frontier Professionals [AI-first employees using agents to ‘augment or automate’].”

The rise of the ‘feeling economy’
This certainly sounds promising – and the fundamental shift in how we work could mean mass new job creation. A recent McKinsey paper, The agentic organisation: Contours of the next paradigm for the AI era, points to ‘M-shaped supervisors’ and ‘T-shaped experts.’ “New profiles are emerging, such as agent orchestrators, who design and supervise agent workflows; hybrid managers, who lead blended human-agent teams; and AI coaches, who help employees integrate AI into daily work,” wrote the researchers.

Another study, Artificial intelligence, workers, and future of work skills, meanwhile highlights ‘trainer’ roles, where human workers teach AI systems how to perform (including curating data); ‘explainer’ roles, requiring communication and technical skills to explain AI output for end users; and ‘sustainer’ roles to help make sure AI systems in organisations operate fairly and transparently. This shift could mean ‘human’ skills become increasingly in demand, according to many experts. A recent independent paper, How AI influences the experience of work: upsides and downsides for workers, describes this as a new ‘feeling economy,’ with interpersonal skills, empathy and social and emotional intelligence at the core.

Pencheng Shi, Associate Dean for Research and Program Director at the Rochester Institute of Technology, agrees. “What I have seen is that employers are starting to look for people who are much better in softer skills,” he says. “These include leadership, organisation, communication and really understanding the human side.”

He believes competing with AI could bring other benefits too – challenging us to go beyond what AI can currently do and bring elements that are, for now at least, uniquely human. “We need to push ourselves and recognise what makes us different – from each other but also from the machines,” he says. “Work that has your own unique signature and your own ideas is what will stand out, and what makes every one of us different. As people we bring different perspectives, and I think that’s still, for now at least, a human-only strength.”

The entry-level threat
But while this human enhancement is an exciting prospect, there are likely to be significant challenges if and as we move towards what McKinsey researchers recently described as “the largest organisational paradigm shift since the industrial and digital revolutions.” Anthropic Chief Executive Dario Amodei told Axios last year that while AI currently is indeed augmenting human roles, the balance could soon tip into automation – with entry-level roles among the hardest likely to be hit (with many entry-level admin tasks such as legal admin, data entry and simple coding already automatable with AI).

“AI could wipe out half of all entry-level white collar jobs and cause an unemployment surge of 10 to 20 percent in the next one to five years,” he said in the report, adding that AI firms and governments need to stop “sugar-coating” the impending era and take action to raise public awareness of the very real threat. “Most people are unaware that this is about to happen,” he said. “It sounds crazy, and people just don’t believe it. We, as the producers of this technology, have a duty and an obligation to be honest about what is coming.”

A McKinsey survey in 2025 on the new era of work found that 51 percent of organisations reported generative AI was reducing their need for entry-level positions. Shi says he has witnessed a similar trend in the computer programming field. “I am seeing that the big computer companies are only hiring people with 10–15 years’ experience and PhD graduates,” he says. “On the other hand, graduates with bachelor’s and master’s degrees are facing tremendous employment challenges that were unimaginable only three years ago. So even highly skilled and highly valued positions are now under threat.”

Widening the social gap
This narrowing of the workforce is perhaps inevitable if the AI agent vision becomes reality. “In the agentic organisation, structure will pivot to small, outcome-focused agentic teams,” researchers wrote in the McKinsey report on the ‘agentic organisation.’ The analysis found a human team of just two to five people could oversee an agent factory of between 50 and 100 “specialised agents running an end-to-end process such as onboarding a customer, launching a product or closing the books.”

Roles and sectors especially at risk have been widely publicised. A Microsoft report last year ranked the 40 jobs with the highest ‘applicability score’ (or crossover) with generative AI, putting historians, writers, customer service reps, telephone operators, sales reps, journalists, mathematicians, data scientists and personal financial advisors high on the list.

As the list suggests, it’s not just ‘knowledge’ sectors likely to feel the impact; lower-wage workers are especially at risk, according to a 2024 McKinsey analysis, A new future of work: the race to deploy AI and raise skills in Europe and beyond. Researchers found that in Europe, workers in the two lowest-wage-bracket jobs were three to five times more likely to have to change occupations than higher earners; in the US, this figure surged to 10 to 14 times.

Many believe this could cause a concerning gap between those possessing AI and other in-demand skills in the ‘agentic’ era, and those who don’t – and are underlining the importance of educating every area of society in order to democratise the market. “Workers will need to acquire new skills to transition to better-paying work,” wrote the McKinsey researchers in the Race to deploy AI paper. “If that doesn’t happen, there is a risk of a more polarised labour market, with more higher-wage jobs than workers and too many workers for existing lower-wage jobs.”

A new economic model?
While some have argued AI could actually shrink the disparity by making skills more accessible to everyone who has access to the intelligence, Shi believes the social and cultural upheaval is one of the biggest risks we face as AI grows in its dominance – and that wealth distribution will be key if the more negative forecasts become reality. “I think if we don’t change the way we distribute wealth, the social bifurcation in the AI era could get drastically worse,” he says. “I think societies need to have a safety net in place to support those who may pay a bigger price.”

Anthropic’s Amodei likewise believes these discussions are of the essence. “It is going to involve taxes on people like me, and maybe specifically on the AI companies,” he told Axios, floating the idea of a ‘token tax’ on AI revenues. Earlier this year, Elon Musk proposed the idea of a ‘Universal High Income’ to counteract any potential large-scale, AI-induced unemployment. A development on the earlier economic idea of ‘Universal Basic Income’ (UBI), this assumes that AI would lead to a significant increase in productivity, boosting the economy and creating enough wealth to go around.

“Universal High Income via checks issued by the federal government is the best way to deal with unemployment caused by AI,” he tweeted. “AI/robotics will produce goods and services far in excess of the increase in the money supply, so there will not be inflation.” While it’s an interesting, potentially utopian idea, some have already posited issues around its predecessor, UBI; this would likely bring further challenges still.
Psychological threats
In any case, it’s not just the financial impact that needs to be considered if this fundamental transformation comes about in the way many are predicting it will. McKinsey’s A new future of work paper claimed that up to 12 million occupational transitions could be required in Europe alone as a result of AI – double the pre-pandemic rate. That is likely to bring a significant psychological toll, especially among societies where identity and self-worth are often synonymous with work, career status and progression.

In a study, Gen AI and the psychology of work, researchers Erik Hermann, Stefano Puntoni and Carey Morewedge looked at how generative AI in the workplace can “frustrate basic psychological needs for competence, autonomy and relatedness.”

“Unlike previous technologies, GenAI can demonstrate cognitive, creative and interpersonal capabilities that challenge traditional human–machine boundaries and redefine the knowledge, task, and social characteristics of work,” they wrote. They outlined the need for employers and employees to address these threats, fostering “human-centred” workplaces to balance the benefits and risks of AI.

The potential psychological impact isn’t just limited to identity, of course; with ever-greater reliance on LLMs and other forms of generative AI, are we dumbing down our skills, especially as younger generations grow up around it?

“I believe this is the most challenging question,” says Shi. “I think if Google Maps or GPS is an example, I think we could lose those skills or cognitive thinking ability. I think this is something we have to find ways to address.”

In a recent study published in The Lancet, a group of experienced doctors were given AI tools to help with diagnosis in colonoscopies. After they returned to human-only diagnosis following the three-month trial, their performance had dropped from before they had started using it. “This was a period of just a few months,” says Shi. “So if you scale that up, it is a little alarming.”

An unpredictable future
All of this is based on the assumption that AI continues to advance at its current rate, of course – and largely depends on the development of agentic AI. How advanced agentic AI really gets is a key question that even experts right now can’t fully be sure of. “So far, AI agents are still put together by humans for intended purposes,” says Shi. “It is hard to predict if they could become fully autonomous – including in mission critical situations such as military operations.”

If such agents were to become more advanced, to what level they would be trusted to make high-level decisions is another key obstacle. “AI could make decisions in critical situations such as military operations in milliseconds or nanoseconds,” says Shi. “They could arguably make fewer, less severe mistakes than humans. But what is the right way? These are fascinating ethical, legal and moral questions.

“I think there needs to be a global consensus to ensure AI isn’t used for bad outcomes,” he says. “AI could be more dangerous than nuclear weapons if there aren’t guardrails in place to ensure it is used for positive, not negative, outcomes.”

There are multiple other risks and roadblocks to overcome, of course – from bias in AI algorithms to how much trust consumers will have in AI, alongside ongoing inaccuracies and ‘hallucinations’ (or false information, disguised as accuracy) still sometimes seen in LLMs. And as with every prediction, where any of this really goes is anyone’s guess until it actually happens. “The story of humanity is one of evolution and replacement,” wrote the researchers in Gen AI and the psychology of work. “Many skills and jobs will be replaced by GenAI. Organisations and workers will adapt, as they have in response to earlier technological innovations, creating demand for and developing new skills and roles.”

While this may well be true – and while the raft of newly created jobs could go at least some way in mitigating the impact – re-training displaced workers to take them up will be a race against time if AI continues apace (and it is growing rapidly; McKinsey analysis found that AI systems could potentially complete four days of work without supervision by 2027).

AI may well bring net good and provide a major boost to economies. It could save some of the greatest challenges of our time, from climate change to cancer. But as with any major economic revolution, governments, businesses and individuals need to prepare themselves for an unpredictable ride that could lead in many different directions and to many variable outcomes.

Now is the time for tech companies, business leaders and policymakers to take control of which way it goes – for the future of not only the workforce but the very identity and humanity by which we live our day-to-day.
Can private capital save development?

From her office in Delhi, Dr Nisha Dhawan is doing something her predecessors at EMpower never did: running a global foundation from the Global South. The new president and CEO of the New York-headquartered foundation, which was set up 25 years ago by emerging markets investment professionals to channel money back into the regions generating their returns, was never asked to relocate. That, she says, is the point, and it is a recognition of the importance of leadership that’s close to the people an organisation is helping.

“I was never asked to get on a plane and move to London or move to New York,” she says. “And that, I think, is not only different for EMpower, but it is different for the sector as a whole.” Her appointment lands at an awkward moment for development finance. Official development assistance from OECD donor countries fell 23.1 percent in real terms in 2025 to $174.3bn, according to preliminary data published by the OECD in April – the steepest single-year drop on record. The US alone drove three-quarters of the decline, falling by 56.9 percent.

At the same time, investment capital is flowing back. US ETFs focused on EM stocks absorbed almost $31bn over the year, according to estimates from Strategas Securities.

Investment, philanthropy or a hybrid
The World Bank has put the financing gap needed to achieve the Sustainable Development Goals (SDGs) by 2030 at around $4trn. But can private capital, whatever form that may take, whether it is investment, philanthropy or some hybrid, meaningfully fill a gap of that scale?

Dhawan, who started at Deutsche Bank and Barclays in London before completing a PhD at IIT Delhi, has spent 14 years inside EMpower watching the answer evolve.

“It is absolutely possible,” she says of philanthropy stepping into the vacuum. “It is amazing to see how the philanthropic sector has stepped up, namely individuals. I feel like there is a lot more risk capital, for lack of a better word, coming from individuals than we have ever seen. And corporates are really thinking through their role, their responsibility in what it means to be giving back in the markets they are investing in.”

It is amazing to see how the philanthropic sector has stepped up

EMpower has deployed over $60m across nearly 400 locally run organisations in 15 countries since 2000. But what EMpower brings to the table is more than just capital, it is a different model of sustainable giving, and what that kind of philanthropy can do, Dhawan argues, is sit beside investment capital rather than replace public funding.

“We know that top down investment doesn’t work,” she says. “If we flip the script where that top down which is necessary and non-negotiable investment in the emerging markets is clubbed together with meaningful, strategic, effective philanthropy at the local grassroots level. That is where the magic happens, because that is where they meet in the middle. And that is where you are going to see the needle moving in emerging market countries.”

Almost 70 percent of EMpower’s money comes from financial services, raised largely through galas and donor networks in London, New York and Singapore, but the granting decisions are kept local. Country teams based on the ground identify and back local organisations directly, and partners are funded for 10 years rather than the one- or two-year cycles typical of the sector. In India, for example, the final call on which new organisations to bring into the portfolio sits with EMpower’s youth fellows. These are young people from the communities the foundation serves.

Investment strategy
Of course, it is not just in India that EMpower taps into the knowledge of the people it is helping. In Mexico, fellows are helping design the investment strategy in the country. In South Africa, a cohort is shaping how mental health programming gets embedded across the regional portfolio. And in Indonesia, fellows have helped build a secular and reproductive health curriculum that is now used across grantee partners in the greater Jakarta area. “It is young people creating a curriculum that is then embedded across several of our organisations,” Dhawan says. “Expertise lies in the hands of the people that we most want to serve.”

Dhawan rejects the sector’s habitual obsession with scale in numbers. She points to the Antarang Foundation, whose school-to-work modules the Indian government now runs across six states; Virlanie in the Philippines, working with young people born on the streets; and a partner in Argentina that helped embed mental health programming across Buenos Aires.

“Success can be depth and it can be influence and influencing others in a meaningful way,” she says. “The greatest cream that rises to the top is that for us success looks like sustainability.” That meeting point between commercial and concessional capital is where investment managers like Triodos Investment Management are operating.

Triodos recently signed an agreement with the Austrian Development Bank and with FMO. Their investment will be integrated into the Hivos-Triodos Fonds, a fund that will then be used to deploy capital into agriculture, renewable energy and the like.

Maritza Cabezas, senior investment strategist, says one of the ways the group can create greater impact is by “collaborating with institutions whose sources of funding can be cheaper than ours, and in that way getting more attractive investments for our clients. It has to be at the lowest cost possible but have the highest impact possible, and therefore we find these partnerships through blended finance quite attractive.”

Cabezas adds: “We have several examples of how we work with different development financial institutions to finance projects that need attractive funding costs in order to be viable. We finance agriculture projects in Ghana that use technology in the agricultural sector.” But there are challenges. She says that because large development finance institutions are very demanding, their requirements can be challenging for the smaller investees Triodos funds in emerging economies.

Considering the impacts
Another challenge is the existence of non-like-minded investors that do not consider the impact they are having in emerging markets. Because the cost of considering impact isn’t transparent, returns of those who are doing harm to people and the planet can seem higher. Therefore, it can be difficult to attract the capital that is needed to invest in areas that Triodos prioritises, such as financial inclusion or biodiversity.

For EMPower there is another difficulty to attracting capital. Its giving largely tracks the financial markets its donors work in, with the foundation feeling the 2008 and 2013 downturns clearly. But institutional funders, where roughly 30 percent of its funding comes from, provides a counterweight to market cycles and lets the organisation back its boldest ideas.

What we want to make sure is that this time no one is left behind

“Ford Foundation, Co-Impact, SIF, all of these organisations who have the technical wherewithal, but also the gravitas, have enabled us to try out our boldest ideas, whether that is girls making the final decisions about our grant making, or whether that is bringing together youth fellows to decide curricula,” Dhawan said. Adam Heuman, vice president of global development at EMpower, agrees and recalls what the organisation’s co-chair Mary-Therese Barton, who is also CIO for fixed income at Pictet Asset Management, says.

“The way she puts it is that emerging markets are back as an asset class. And that is something to really celebrate. What we want to make sure is that this time no one is left behind,” he says. “We hope that there is a boost to what we are able to do in terms of capital inflows. But how we use that is to make sure that no young person gets left behind.”

One way Dhawan wants to ensure that is done, and other investors also think about it as well, is by applying a gender lens to every single investment decision.

“We can’t talk about moving the needle in a market and seeing overall GDP going up if we are not considering the people that live within it,” she says. “And we can’t consider the people that live within it if we are not meaningfully double clicking on the lived realities and the barriers, the additional barriers that women and girls face.” She adds: “If we start thinking about young people who are not in education, in entrepreneurship or in technical training, and we break down that number, very often, it is a woman or a girl. If everybody got to start thinking about disaggregating for gender in a meaningful way, or even just assuming the gender lens, it would change the planet.”

The superhub race for global wealth

To walk through Hong Kong’s Central District is to feel a city that never stops transacting. Hong Kong’s and Singapore’s skylines speak the language of prosperity. Beneath the glass and steel, a question emerges: where will global capital choose to live next? Early morning Hong Kong hits you before you clear the MTR barriers. Humidity rises off Victoria Harbour as Star Ferries surge across the water. The smell of gai daan jai mixes with diesel.

Elevated walkways funnel suited crowds towards Exchange Square. Brokers bark in Cantonese, chasing the first deal.

Four hours south, Singapore greets you with a different intensity. Quieter, more controlled, efficient. The skyline sharper, air cleaner, the streets meticulously ordered. In Raffles Place, the soundscape softens: air-con hum, polished shoes on marble, the low murmur of wealth managers easing clients into tax-efficient structures. Where Hong Kong vibrates, Singapore glides. The choice is no longer between cities, but how to balance both. Bloomberg Intelligence projects that both cities will surpass Switzerland to become the world’s fastest-growing cross-border wealth hubs.

Anatomy of a superhub
A superhub attracts capital and talent during geopolitical instability. Success rests on a powerful trifecta: quality of life, career opportunity and proximity to the engines of global finance. April’s 2026 Numbeo Quality of Life Index ranks Singapore ahead of Hong Kong (159.08 to 130.75). While Singapore leads in purchasing power and lower pollution, Hong Kong remains a competitor in safety and climate. Hong Kong operates under Common Law, an asset for international contracts. Its regulatory direction increasingly aligns with Mainland policy priorities, creating a market defined by speed and high potential, but also volatility. Singapore, dubbed Asia’s Switzerland, offers neutrality and predictability. The Monetary Authority of Singapore (MAS) is proactive and transparent. Governance has shifted from back-office necessity to strategic asset. “Governance is no longer a framework you set and forget,” says Ken Ong, managing director at Morgan McKinley, Singapore. “With MAS updating regulations frequently, compliance has shifted from a support function to a core, resilient part of business.”
 

Hong Kong

1891 – HKSE established
Foundations of Hong Kong’s financial markets

1970s – Capital-market rise
Emerges as one of Asia’s most liquid markets

1983 – Dollar peg
HKD linked to the US dollar

1997 – Handover
Retains common law under ‘one country, two systems’

2000s – Mainland integration
Offshore RMB hub and gateway to China

2010s – IPO dominance
HKEX becomes a leading global listing venue

2020s – Turbulence and resilience
Retains role as China’s ‘super connector’

2026 – Renewed momentum
IPO recovery and capital-market rebound


Hong Kong is experiencing a resurgence. The ‘Top Talent Pass Scheme’ has stabilised the workforce with new talent inflows. Singapore is winning the family office race. Its 13O and 13U tax incentives, combined with strong governance and green finance, make it the preferred base for multi-generational wealth. Jeremy Cheng, Adjunct Assistant Professor at CUHK and Principal at Lansberg Gersick Advisors, explains that “families are increasingly embracing a ‘Barbell Strategy’ in wealth management.” “Establishing a satellite office in a new jurisdiction is frequently the first time a rising-generation member assumes a true operator role,” says Cheng. “If the incumbent generation builds wealth through concentration in specific industries, the rising generation is focused on preservation through portfolio transformation.” This shift is accelerating direct investment into AI, biotech and transition finance.

Hong Kong’s pressure points
• Mid-level talent shortages persist despite aggressive recruitment schemes
• Capital flows remain exposed to geopolitical and Mainland policy shifts
• 35 percent of firms support AI upskilling, risking long-term productivity

AI and the next decade
The GFCI 39 report ranks Hong Kong first globally for fintech, driven by its AI readiness and integration with the GBA tech cluster. AI may be the defining factor. Nine in 10 Hong Kong financial institutions are deploying or piloting AI. “Hong Kong’s adoption is intensifying but remains focused on tactical AI tools,” says Iain Bonner-Fomes, Chief Commercial Officer at KEY Smart Technologies. “Hong Kong doesn’t have the same problems as Singapore, so its uptake ought to be different. Singapore’s largest problem is the capacity to grow its business while constrained by its geographical size.”

Yet, Bonner-Fomes believes Singapore is ahead: “We are seeing the government there forming strong partnerships with businesses. In Hong Kong, that isn’t happening. It is more of an individual effort. It will be relatively easy to catch up.” As Singapore consolidates its status as Asia’s anchor of stability, Hong Kong mounts a comeback. It is a contest shaping the next era of global finance. Hong Kong rose as a capital-markets gateway to China. Singapore’s strength came from regulatory stability and geopolitical neutrality.

Wong Joo Seng, Chairman of the Singapore International Chamber of Commerce (SICC), explains, “Singapore serves as a global and regional base, while Hong Kong offers proximity, market understanding and connectivity into Mainland China.” This enables businesses to bridge both ecosystems with greater precision and confidence.

The April 2026 partnership between the SICC and the Federation of Hong Kong Industries (FHKI) is a proof of concept. Wong explains: “We are creating pathways into the Greater Bay Area, leveraging Hong Kong’s role as a gateway into mainland China. SICC aims to create a reciprocal membership framework, where member companies from both organisations are better positioned to navigate market entry, build partnerships and expand across each other’s markets.”

The MOU cements the emerging ASEAN–GBA corridor. Linking ASEAN growth to GBA innovation, Wong notes, “the partnership is about turning access into advantage – helping companies move faster, partner smarter and scale with confidence in one of the world’s most dynamic economic regions.” At a private capital level, the same logic is beginning to take shape. Sophisticated families increasingly separate where capital is preserved from where it is deployed.

Singapore’s pressure points
• Rising compliance and operating costs are increasing pressure on large funds
• Critical shortage in AI-specialised roles, driving up overheads
• KYC standards can push onboarding times to nine months

The new geography of power
Both centres serve different needs, shaped by geography, purpose and alignment. Hong Kong remains the gateway and a natural base for China-centric priorities. It is the only international financial centre with direct access to Mainland China’s capital markets, the GBA and the world’s largest offshore renminbi pool. Singapore is the gateway to ASEAN, a preferred hub for Southeast Asian flows and growing links to India and the Middle East.

The latest GFCI results show razor-thin margins. Professor Michael Mainelli, Chairman of Z/Yen Group and index co-creator, explains, “GFCI 39’s one-point gap between Hong Kong (765) and Singapore (764) is less a story of convergence than of compression at the top. The real signal lies in the sub-indices: marginal shifts across instrumental factors such as business environment, human capital and sectoral specialisation are now decisive, suggesting not a single ‘superhub’ emerging, but differentiated excellence within a tightly packed elite.”

Hong Kong’s momentum is visible across major indicators. More than 450 IPO applications are in the pipeline, expected to exceed 2025’s figures, renewing confidence in its capital markets. Hong Kong recorded 5,221 start-ups in 2025, an 11 percent YoY increase. HSBC’s third Global Investment Summit brought together over 1,500 institutions and 5,200 industry leaders. As Maggie Ng, CEO of HSBC Hong Kong, noted in her closing remarks, the city has demonstrated resilience despite market instability. Large-scale events reinforce Hong Kong’s role as the superconnector between China and the world. Cheng notes that high-growth capital is deployed in AI and biotech, where NextGen leaders see opportunities for returns and influence over the future of the global economy.


Singapore

1965 – Independence
Singapore prioritises finance and trade

1971 – MAS established
Centralised monetary regulation

1970s–80s – Asian Dollar Market
Global banks drawn to stability

1990s – Wealth-management expansion
Emerges as a private-banking hub

1997 – Asian financial crisis
Stability reinforced during crisis

2008 – Global financial crisis
Safe-haven capital inflows accelerate

2010s – Tech-finance expansion
Investment in digital finance and RegTech

2026 – Safe-haven consolidation
Family-office boom and neutrality strengthen position


Singapore’s strength lies in its institutional clarity. The city has built a professionalised ecosystem for family offices. A generational shift reshapes how wealth is managed. “ESG and sustainability are now seen as primary drivers of long-term outperformance,” says Cheng. As family offices compete with venture capital firms for talent, Singapore’s evolution from wealth centre to innovation allocator accelerates. Beyond family offices, multinationals are responding to this stability premium. Singapore’s emergence as a dominant APAC headquarters hub is reshaping its talent base. Ong notes that the seniority of roles has shifted: “Ten years ago, it was just a Head of Compliance in Singapore. Now, we are seeing APAC Heads based here.” He notes, “Over the last two to three years, we have seen more headquarters moving into Singapore.”

Google opened its first Singapore office in 2007 with 24 employees; today, its purpose-built Asia-Pacific headquarters houses nearly 3,000. Dyson’s 2022 relocation of its global HQ from the UK to Singapore echoes this future-proofing. Yet growth faces a bottleneck: Morgan McKinley’s 2026 Singapore Salary Guide states that employers continue to face a shortage of skilled professionals, especially in AI, data, cybersecurity and sustainability. Singapore’s long game: a safe-haven model built on predictability and the ability to attract senior decision-makers.

Two cities, two futures
The dual-hub model could define the next decade of global finance. Singapore provides the stability of treasury, governance and preservation. Hong Kong delivers the velocity of capital raising, liquidity and access to the Chinese growth engine. One refines the plan; the other accelerates it. As evening settles over Hong Kong, the city shifts into its nocturnal rhythm. Trams hum past towers lit with the residue of the trading day. The Symphony of Lights dances over the skyline. A choreography of colour and motion mirroring the city’s economic temperament.

Singapore moves more deliberately. The Night Safari opens as Hong Kong’s markets exhale. Across the bay, the Supertrees glow in a measured sequence. These are not rivals, but two superhubs with distinct philosophies. The advantage belongs to firms and investors able to move between both with precision. As Cheng puts it: “The most successful leaders will be those who weave both Singapore and Hong Kong into a single, diversified and resilient web of global wealth.”

From passion purchase to portfolio strategy

Art that hung on walls and wine that sat in cellars is now competing for space in portfolios. After two years of correction, the market is finding its footing, but the numbers still demand careful reading. In spring 2022, as public equity markets stumbled and central banks signalled the end of cheap money, auction rooms told a different story. Sotheby’s reported record results. Rare whisky indices hit levels that would have seemed fanciful five years earlier. Tangible assets, long dismissed by mainstream wealth managers as indulgences of the very rich, were attracting serious institutional scrutiny for the first time.

Passion investing, encompassing fine watches, contemporary and classic art, vintage wine, rare whisky and high-end accessories, has spent a decade trying to shed its image as a plaything of the wealthy. In some corners of wealth management, it is succeeding. In others, scepticism remains deep and justified. The gap between those positions reveals something important about how investors think about value and risk.

For most of the 20th century the value of art, wine and watches was partly financial but mostly cultural, expressions of taste and inheritance rather than deliberate capital allocation. What changed was the infrastructure that grew up around them. Index providers began tracking price movements and platforms emerged to authenticate and trade collectibles. A prolonged period of low interest rates left investors hunting returns in unfamiliar places.

The long-run numbers remain striking. The Knight Frank Luxury Investment Index (KFLII) showed that $1m invested in 2005 would have grown to approximately $5.4m by end-2024. Individual categories performed even more dramatically at their peaks: rare whisky appreciated 191.7 percent over a decade and watches 125.1 percent.
Liam Bailey, Global Head of Research at Knight Frank, says: “Luxury collectibles have delivered for investors over the long term.” Wealth managers, particularly those serving ultra-high-net-worth clients, have begun to formalise what many already knew: that significant client wealth was sitting in collectibles, whether or not those assets appeared on any investment statement.

The performance reality check
The long-term figures are compelling. The recent ones are a useful corrective. The KFLII recorded a marginal –0.4 percent decline in 2025, signalling stabilisation after two years of broad correction across several collectible categories. That follows falls of one percent in 2023 and 3.3 percent in 2024. Even after three consecutive years of correction, the index remains 40 percent above its 2020 baseline, showing a market settling after a boom, not one in distress.
The auction houses tell a similar story of tentative recovery. Sotheby’s, Christie’s and Phillips reported combined projected revenue of $14.1bn for 2025, up roughly 10 percent from 2024. Sotheby’s alone reported total sales of $7bn, a 17 percent increase over 2024, with fine art up 15 percent to $4.3bn. That compares with auction sales of $4.1bn across the big three in 2024, itself nearly half the 2022 peak. Impressionist sales surged 80.4 percent, modern art advanced 19.4 percent, and Old Masters registered a 68.7 percent uplift.

We see a lot of interest driven by the tangibility and the emotional factor

Christie’s CEO Bonnie Brennan said: “The energy has returned to the saleroom, online and across the market. We have seen renewed confidence worldwide.” The recovery, though, followed a pattern familiar to anyone who has watched asset markets closely: a pandemic-era surge driven by liquidity and newly wealthy buyers, followed by a reversion as rates rose. Assets that held up best were handbags, jewellery and coins and tended to be those with genuine scarcity and cultural resonance. Those that fell hardest had attracted the most speculative attention. The fine wine market posted a decline of 2.5 percent in 2025, with total losses approaching 25 percent since the 2022 peak. Whisky, the standout performer of the previous decade, has still not recovered its pre-correction highs.

The lesson is not that luxury assets are poor investments. It is that they are uneven and cyclical. Returns cluster around quality and timing in ways that reward expertise and punish trend-chasing. The investor who bought a Patek Philippe Nautilus watch at the height of the pandemic premium paid a very different price to one who bought the same watch in 2018. Same object, three years apart, entirely different financial story.

What is driving demand?
Despite the correction cycle, the structural forces behind long-term growth remain intact. Inflation has revived interest in tangible stores of value. Geopolitical uncertainty has reinforced the appeal of portable, internationally recognised assets. The value of 1959 Macallan whisky, for example, is legible to collectors from Shanghai to Geneva.

Liam Bailey, Global Head of Research at Knight Frank , speaking on the 2026 Wealth Report, said: “After a cycle defined by extraordinary highs followed by rapid readjustment, the luxury investment market is now entering a more rational and more discerning phase. Collectors are increasingly prioritising rarity and cultural resonance and younger generations are reshaping ownership models through digital and fractional platforms.” Demographics are shifting the buyer base in ways that will define the category’s next decade. At Sotheby’s, buyers under 40 made up 17 percent of global fine art bidders and just under 30 percent in luxury categories in 2025, while first-time bidders accounted for 35 percent of all participants. Where older collectors gravitated toward old masters and grand cru Bordeaux, younger buyers are drawn to contemporary art, street-wear, sneakers and independent watchmakers. For this cohort, the line between cultural consumption and financial investment has all but disappeared. “As people become wealthier, their preferences evolve beyond mass-produced luxury items to seek more unique and exclusive pieces. There is a desire for items that reflect authenticity, craftsmanship, heritage and skill,” Bailey adds. Serious participation in luxury collectible markets once required three things in short supply: significant capital, specialist knowledge and the right relationships.

Digital platforms and fractional ownership models have begun to change that, though not without complications. Phillips Auction House reported that 70 percent of works sold in the first half of 2024 were purchased via online bidding. For newer categories, rare sneakers, vintage haute couture, even natural history specimens, the internet has created new markets. A 66-million-year-old Edmontosaurus skull, sold via a fractional platform, delivered a 22.4 percent return in just eight and a half months, according to Knight Frank.

Leonardo De Keersmaeker, Asset and Partnerships Manager at Timeless Investments, explains the appeal: “We see a lot of interest driven by the tangibility and the emotional factor. It is about diversification of assets, with a fun story to tell.” The tension in all of this is real. The exclusivity underpinning the value of luxury collectibles is foundational to their appeal. Eran Peer, Co-Founder and CEO of fractional platform Konvi, cautions that: “the most valuable asset in the luxury investment space is knowledge” and that investors must “move beyond the hype and avoid simply following trends.” He believes success requires deep knowledge rather than simply following market hype.

Any serious discussion of luxury as an asset class must reckon with characteristics that sharply distinguish it from traditional investments. The most significant is liquidity, or the consistent lack of it. There is no exchange on which to sell vintage cognac at a moment’s notice. Auction timelines run to months. Private sales require the right buyer at the right moment, and the right buyer is never obligated to appear.

Valuation presents a related problem. Without a central pricing mechanism, the true market value of a collectible is largely unknowable until the moment of sale. Indices provide orientation, but they track categories, not individual items, and the spread between an exceptional piece and an average one can be enormous. Physical risks are unique to this category too: improper storage, contested provenance, or an accident that insurance may cover but the market will not forget. Authentication in the watch market, where sophisticated counterfeits are increasingly hard to detect, has become a cost of entry.

Success requires deep knowledge rather than simply following market hype

The broad consensus among wealth managers is that luxury belongs at the margins, a satellite position rather than a core holding, sized appropriately for its illiquidity and the expertise required. Some advisers suggest allocations of up to 20 percent in alternatives broadly defined, with collectibles representing a portion of that, not the whole.

The more important shift is in how the question is being framed. For most of the 20th century, passion purchases were kept separate from investment portfolios by convention. That convention is dissolving. As trend forecaster Martin Raymond observed in Knight Frank’s 2026 Wealth Report: “Collecting is not conspicuous consumption – it is conspicuous taste.” The generation that normalised cryptocurrency as a portfolio asset sees no reason to treat a limited-edition watch differently from any other store of value, and wealth managers who treat the categories as entirely separate risk losing the conversation.

Passion with discipline
Knight Frank frames the current moment as a market characterised by buyers who are highly disciplined, not afraid to spend, but unwilling to pay above fair value. The froth has cleared. The question now is what endures underneath it and which investors are patient and knowledgeable enough to find out.
The most successful long-term participants in luxury collectible markets have consistently been those who understood both dimensions: who bought what they genuinely valued, held through volatility without panic and sold with as much discipline as they brought to acquisition. In the end, the best investors in luxury may be those who understand both the market and its meaning and never mistake one for the other.