Digital Banking Awards 2025

The digital banking landscape has undergone another transformative year, as technology, regulation, and consumer behaviour continue to reshape the way financial services are delivered. From the rise of embedded finance and open banking to advances in AI-powered personalisation and cybersecurity, 2025 has been about deepening digital trust and enhancing customer experience. Banks and fintechs alike are finding new ways to blend innovation with reliability – delivering platforms that are smarter, safer, and more intuitive than ever. 2025’s World Finance Digital Banking award winners have stood out for their ability to harness technology in meaningful ways, driving financial inclusion and redefining digital excellence.

Best Digital Banks

Africa
Ecobank

Asia
DBS Bank

Europe
Revolut

Latin America
Banco Popular Dominicano

Middle East
Commercial Bank

North America
Ally Financial

Best Consumer Digital Banks

Bulgaria
Postbank

China
Fubon

Colombia
Bancolombia

Costa Rica
BAC Credomatic

Dominican Republic
Banco Popular Dominicano

France
Revolut

Ghana
Ecobank Ghana

Greece
Eurobank

Hong Kong
Standard Chartered

Indonesia
Bank Negara Indonesia

Kuwait
National Bank of Kuwait

Malaysia
Maybank

Mexico
Banorte

Nigeria
Access Bank

Pakistan
Habib Bank

Portugal
Santander

Saudi Arabia
Al Rajhi Bank

Singapore
DBS Bank Singapore

Turkey
Garanti BBVA

UAE
Mashreq Bank

US
Ally Financial

Best Mobile Banking Apps

Bulgaria
m-Postbank

Colombia
Bancolombia App

Costa Rica
BAC Credomatic App

Dominican Republic
Banco Popular Dominicano

France
Revolut App

Ghana
Ecobank Ghana Mobile App

Hong Kong
Standard Chartered Mobile App

Indonesia
BNI Mobile Banking App

Kuwait
NBK Mobile Banking App

Malaysia
Maybank2u App

Mexico
Banorte Movil

Nigeria
Access Bank Nigeria App

Pakistan
HBL Mobile App

Saudi Arabia
Al Rajhi Bank App

Singapore
DBS Digibank App

Taiwan
Taipei Fubon

Turkey
Garanti BBVA

UAE
ADCB

US
Ally Mobile App

Best Bank for AI Integration & Digital Transformation

Africa
Discovery Bank
Asia
DBS Bank
Europe
Unicredit
Middle East
Commercial Bank

Best Use of Social Media

Kuwait
Gulf Bank

Investment Management Awards 2025

For investment managers, 2025 has been a year that demanded both agility and conviction. With markets influenced by macroeconomic uncertainty, interest rate recalibrations, and renewed focus on ESG integration, firms have been tested on their ability to generate sustainable value in a shifting global economy. Across both traditional and alternative asset classes, top performers have embraced technology to sharpen their analysis, enhance transparency, and deliver meaningful outcomes for clients. The World Finance Investment Management award winners for 2025 represent the very best of that evolution. They have shown vision in navigating risk, creativity in portfolio construction, and leadership in advancing responsible investment practices. We congratulate all of them for not only achieving strong results but also helping define the standards of excellence that will guide the industry into the next chapter.

Best Investment Management Companies

Austria
Kepler Fonds

Bahrain
SICO

Belgium
KBC Asset Management

Brazil
BTG Pactual Asset Management

Bulgaria
DSK Asset Management

Canada
Stonebridge Financial

Chile
Patria Investimentos

Colombia
Sura Asset Management

Denmark
Nordea Asset Management

France
BNP Paribas Asset Management

Germany
Metzler

Ghana
InvestCorp

Greece
Eurobank Asset Management

Hong Kong
HSBC Asset Management

Jordan
Al Arabi Investment Group

Kuwait
Kamco Invest

Luxembourg
Genève Invest

Malaysia
Maybank Asset Management

Mexico
BBVA

Monaco
Monaco Asset Management

Morocco
Wafa Gestion

Netherlands
Van Lanschot Kempen Investment

Nigeria
FBNQuest

Pakistan
Al Meezan Investments

Romania
BT Asset Management SAI

Saudi Arabia
Alistithmar Capital

Singapore
UOB Asset Management

South Africa
Sanlam Investment

Switzerland
Vontobel

Thailand
UOB Asset Management

Turkey
Ak Asset Management

UAE
Emirates NBD

Vietnam
Dragon Capital

Islamic Finance Awards 2025

The Islamic finance sector enters 2025 with renewed momentum, marked by steady expansion across key markets, growing investor appetite for Sharia-compliant products, and a widening global appreciation for ethically grounded financial models. Sukuk issuance continues to mature as a mainstream funding mechanism, Islamic wealth management is attracting a new generation of clients seeking values-aligned investment strategies, and digital innovation is reshaping how institutions deliver Sharia-compliant solutions—from fintech partnerships to AI-driven compliance tools.

Against this backdrop of growth, diversification, and technological progress, the Islamic Finance Awards celebrate the organisations and leaders who are setting new benchmarks for excellence. This year’s winners represent the sector’s most dynamic achievements: from pioneering product innovation and strengthening regulatory alignment to expanding financial inclusion and elevating global standards.

We extend our sincere congratulations to all the award recipients. Their commitment to integrity, innovation, and industry leadership continues to move Islamic finance forward and reinforces its vital role in the future of global financial services.

Business Leadership & Outstanding Contribution to Islamic Finance
Dr Hussein Said ─ Chief Executive Officer ─ Jordan Islamic Bank

Best Islamic Bank, Jordan
Jordan Islamic Bank

Best Islamic Insurance Company
The Islamic Insurance Company

Best Digital Banking & Finance Software Solutions
ICS Financial Systems

Best Islamic Banking & Finance Software Solutions
ICS Financial Systems

Excellence in Financial Technology Solutions
ICS Financial Systems

Best CSR Engagement and Empowerment Project
Kuwait International Bank, KIB The Stadium

Most Innovative Digital Real Estate Application
Aqari


Innovation Awards 2025

Innovation has always been the engine of progress in financial services – and in 2025, that engine is running at full speed. From fintech disruptors to established institutions reinventing themselves through partnerships, data analytics, and generative AI, this year has demonstrated how creative thinking can translate into real-world impact. Whether through smarter payments infrastructure, next-generation wealth platforms, or inclusive financial access initiatives, innovation is no longer a buzzword – it’s the foundation of growth. World Finance’s Innovation award winners for 2025 exemplify the courage to challenge convention and the ability to turn visionary ideas into measurable results. They remind us that the future of finance belongs to those who not only adapt but also imagine new possibilities.

Most Innovative Companies 2025 (by industry)

AI-Powered Green Fintech for Sustainable Financing 
CTBC Bank

Automotive Interior Design
Antolin

Banking
Banco Azteca

Chemical
INEOS Styrolution

Cybersecurity & Digital Identity Solutions
Kapital Bank

Decentralised Climate Finance
KlimaDAO

Digital Asset Payments for Emerging Markets
Tether

Digital Platforms
ByteDance

Fintech
RedCompass Labs

Fuel-Free Power
Hybrid Power Solutions Partners

High-Yield Asset-Backed Digital Currency Solutions
Kinesis Money

LatAm Digital-First Neobank
Banco W

MENA Real-Time Payments
RAKBANK

Midwest and Southwest Financial Services
BOK Financial

Open Banking & Hyper-Personalisation Solution
Zenus Bank

Payment Technology
Ecommpay

Regtech, Risk & Compliance Solutions
REGnosys

Sustainable Aviation Fuel
LanzaJet

Search Engine
Perplexity

Sustainability Accounting Fintech
Lele-HCM

Sustainable Infrastructure Finance
Stonebridge Financial

Tackling methane emissions in livestock: unlocking voluntary carbon credits

Every 10 seconds, human activity emits over 4,000 metric tonnes of greenhouse gases (GHGs) into the atmosphere. While carbon dioxide (CO₂) remains the most abundant of these gases, methane (CH₄) is far more dangerous in the short term. Despite accounting for only about 20 percent of total GHG emissions, methane is over 80 times more potent than CO₂ over 20 years when it comes to trapping heat in the atmosphere.

Methane’s short atmospheric lifetime – approximately 12 years compared to CO₂’s centuries – means that cutting methane now can deliver significant near-term climate benefits. According to the Intergovernmental Panel on Climate Change (IPCC), methane mitigation is one of the most powerful levers we have to slow global warming over the next two decades. Among methane sources, agriculture is one of the most significant contributors globally, and within agriculture, livestock – especially ruminants like cattle – are primarily responsible. Methane is emitted mainly from the digestive processes of ruminants, a phenomenon known as enteric fermentation. In cattle, this methane is released mostly through belching and accounts for a significant proportion of agricultural emissions.

Our mission is not only to reduce emissions but to empower farmers as key contributors to climate solutions

As the global population continues to rise and demand for meat and dairy products increases, this problem is expected to intensify. The world’s cattle population currently stands at around 1.5 billion and is expected to grow significantly by 2050, especially in developing regions with rising incomes and food consumption. Without effective mitigation, livestock methane could jeopardise global climate goals, including those set by the Paris Agreement.

While various technologies have been proposed to reduce methane emissions from livestock, demonstrating both a measurable impact and scalability in real-world conditions remains a challenge. The need for a solution that is effective, scalable, economically viable, environmentally friendly and scientifically sound has never been more urgent. This is the problem our solution was built to solve.

A game-changing innovation: ANAVRIN
We have developed ANAVRIN, a blend of essential oils, tannins and bioflavonoids carefully selected to support and improve ruminal functions while counteracting methane production. Essential oils play a crucial role in the growth kinetics of certain bacteria. Tannins have positive effects on protein metabolism and possess anti-inflammatory properties, while bioflavonoids act as powerful antioxidants.

By maintaining a stable ruminal environment, enhancing the functionality of beneficial bacteria while controlling the growth of methanogenic ones, ANAVRIN helps improve ruminants’ zootechnical performance and simultaneously reduces methane emissions. ANAVRIN not only cuts emissions but also enhances animal productivity, creating a powerful incentive for adoption and enabling rapid, global-scale impact. This unique combination of climate benefits and productivity improvements sets ANAVRIN apart, aligning environmental goals with agricultural sustainability.*

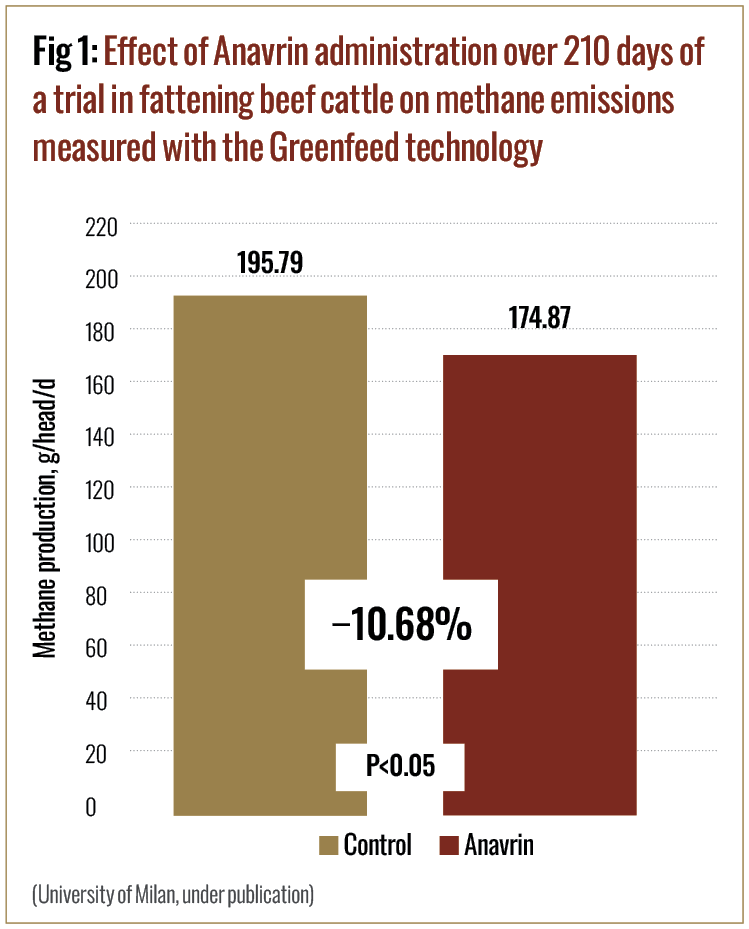
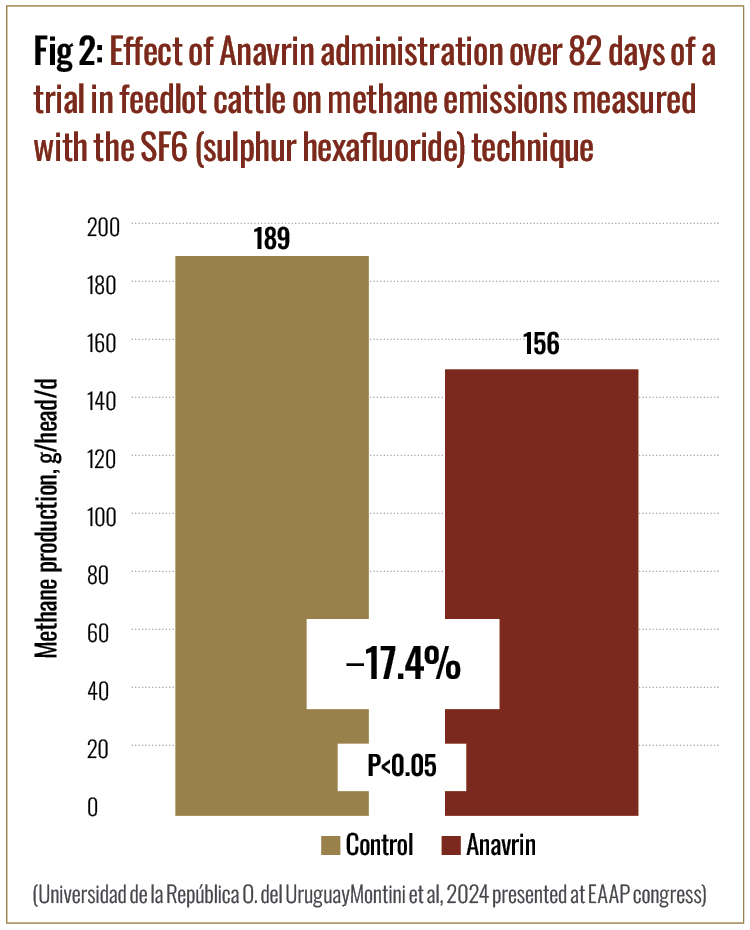
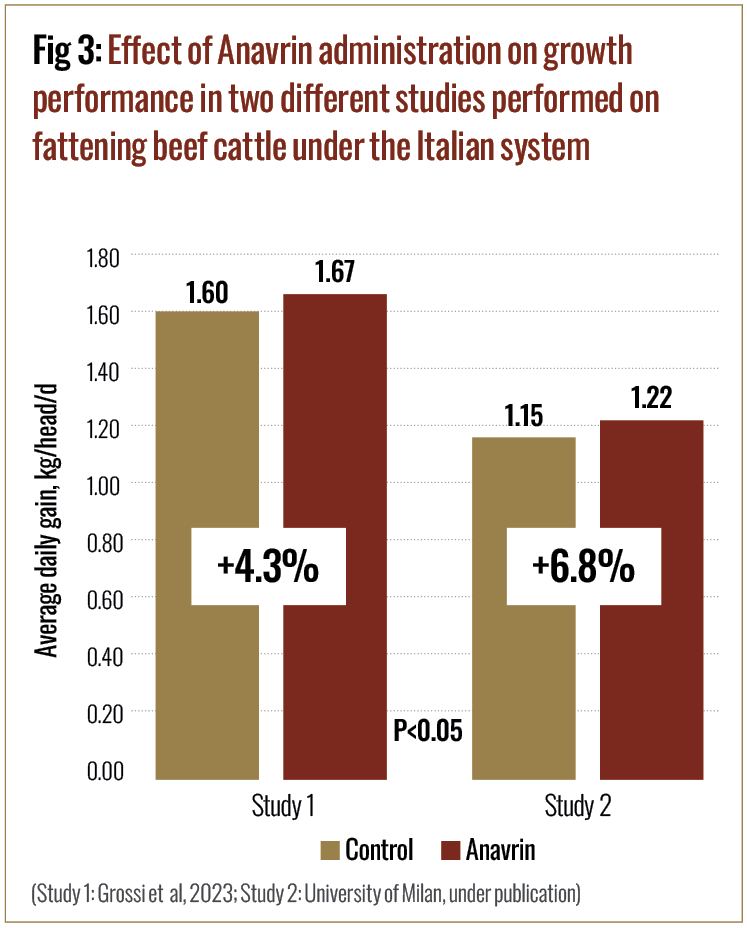
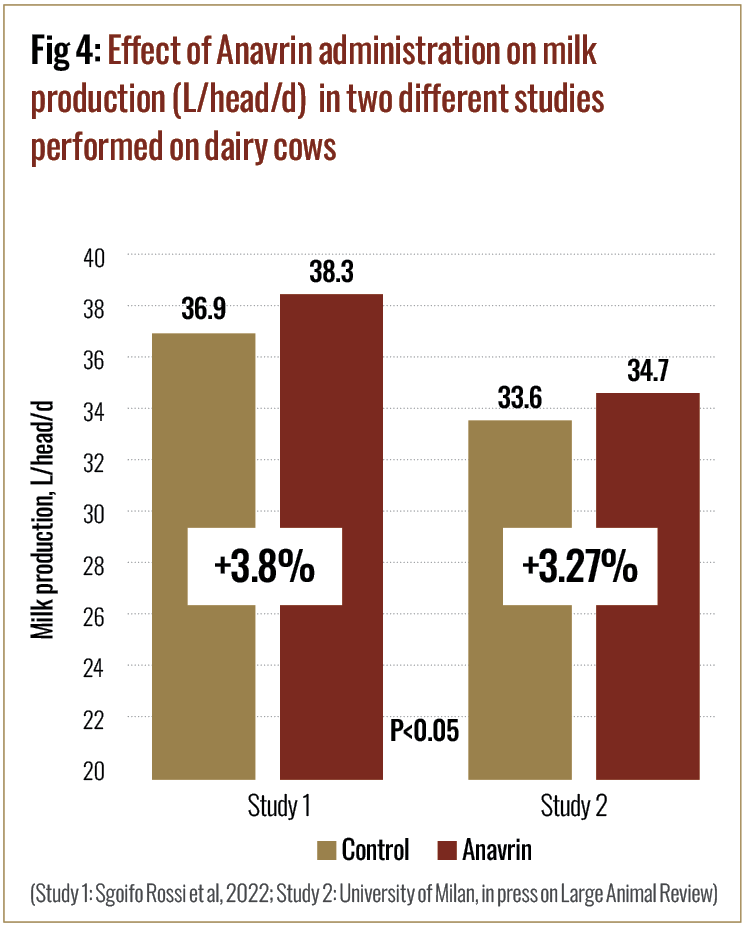
Our technology is grounded in rigorous scientific validation. Over the past several years, we have partnered with leading research institutions and universities to conduct a series of in vivo and in vitro studies across diverse regions and cattle breeds. The findings, published in peer-reviewed scientific journals, consistently confirm that ANAVRIN reduces methane emissions from enteric fermentation by an average of 10–16 percent in terms of methane production grams per head per day (g/head/d). It also improves milk production in dairy cattle and weight gain in beef cattle, with milk yields increasing by 3.2–3.8 percent in energy- and protein-corrected milk, and average daily weight gain rising by 5.5–6 percent (kg/head/day). Furthermore, it improves feed conversion ratio efficiency in both beef and dairy cattle by 6–8 percent, meaning animals require less feed to achieve the same or better growth or milk output. Importantly, studies show no adverse effects on animal welfare or product quality, with some reporting improvements. These results have been consistently replicated in various climates, production systems, and animal types, demonstrating that ANAVRIN is ready for global deployment.

Comprehensive decarbonisation project
Recognising the broader potential of our technology, we initiated a comprehensive decarbonisation project in 2020, beginning in Uruguay, a country renowned for its progressive approach to sustainable agriculture. In collaboration with Verra, the world’s leading standard for carbon credit certification, we launched the first carbon credit project in the livestock sector in South America, specifically targeting methane reduction.

The project’s objectives are to quantify and verify methane reductions in real farm settings using ANAVRIN, translate these emission reductions into verified carbon credits under an internationally recognised framework, and establish a standardised implementation model that includes a regulatory approval pathway, farmer training protocols, methane measurement procedures, and a carbon credit certification process.

The Uruguay project, which has already received initial approval from an independent verification body approved by Verra, has paved the way for global expansion. This model has since been implemented in Italy and Spain, with preparations underway for launches in Brazil, Costa Rica, Argentina, Chile and Australia. This growing momentum reflects the increasing interest from farmers, governments, and sustainability leaders who seek practical solutions for reducing methane emissions.

We are also working closely with two globally recognised climate and carbon advisory organisations whose expertise is guiding us toward global Verra protocol validation for our method. Climit, an experienced consulting firm with a track record in developing and implementing carbon projects worldwide, coordinates initiatives in South America. Rete Clima, a specialist in helping companies develop mitigation strategies to reduce their greenhouse gas footprint and achieve a long-term competitive advantage, serves as the focal point for the project in Europe.

Unlocking new revenue: carbon credits
One of the most innovative aspects of our project is the ability to monetise methane reductions through carbon credits. Under the Verified Carbon Standard (VCS) from Verra, emission reductions generated by farmers using ANAVRIN can be converted into tradeable carbon credits. This opens an entirely new revenue stream for livestock producers, one that is independent of market prices for meat or milk and instead tied to the global demand for emissions reductions. Farmers become part of a new class of environmental stewards, compensated for their role in helping the planet. This approach can be especially transformative for small and medium-sized farms, which often operate with narrow profit margins and face increasing pressure to adopt sustainable practices without sufficient financial support. Our mission is not only to reduce emissions but to empower farmers as key contributors to climate solutions.

The path forward involves scaling our technology and carbon credit framework across regions and livestock production systems. Over the next five years, we aim to secure global Verra protocol validation for methane reduction via ANAVRIN, expand our carbon credit projects to at least 10 more countries, collaborate with governments, cooperatives, and NGOs to encourage adoption, invest in farmer training and support services, and build robust measurement, reporting and verification (MRV) infrastructure.

We are committed to maintaining scientific integrity, transparency and inclusivity throughout this process. Farmers, researchers, policymakers, and sustainability leaders all play a crucial role, and we welcome collaboration at every level. Our work has already been recognised with the award for ‘Best Innovation in Livestock Decarbonisation,’ a testament to the technology’s potential and the measurable impact it is delivering. This recognition is more than a milestone – it is a driving force behind our continued growth, innovation and expansion into new regions and projects. We are only at the beginning and remain committed to bringing our proven solution to a global scale.

*Results may vary based on farm conditions. ANAVRIN’s regulatory status varies by jurisdiction. Carbon credits are subject to final Verra protocol validation.

Carbon Awards 2025

The global transition toward a low-carbon economy has gathered extraordinary momentum over the past year, as governments, investors, and corporations alike accelerate their commitments to net zero. Amid tightening disclosure standards, evolving carbon markets, and growing scrutiny around greenwashing, 2025 has underscored the importance of credible, data-driven sustainability strategies. The winners of 2025’s World Finance Carbon awards have not only demonstrated measurable impact but also shown leadership in integrating climate responsibility into the core of financial and operational decision-making. Their achievements reflect the industry’s broader shift from ambition to action – proving that sustainability and performance are no longer competing priorities but mutually reinforcing goals. We congratulate all our winners for their pioneering work in driving carbon accountability and helping chart a more sustainable path for the global economy.

Best Technology Providers for Carbon Reduction

Blockchain Solution for Carbon Market Liquidity
KlimaDAO

Building Products Supplier
Earth4Earth

Carbon Issuance in GreenTech
SME Rainbow

Decarbonisation in Aviation
LanzaJet

Decarbonisation in the Beef Industry
Vetos Europe

ERW Technology
UNDO Carbon

Farming Technology
Farmonaut Technologies

Large Enterprise and Financial Carbon Accounting
Persefoni

Payment Technology
Ecommpay

SMEs Carbon Accounting
Plan A

Best Companies for Carbon Reduction

Airports
Aeroporti di Roma

Chemicals
INEOS Styrolution

Data Centres
Quality Technology Services

Flag Carrier Airlines
Turkish Airlines

Footwear
CCC

Glass
BA Glass

Oil & Gas
Harbour Energy

Semiconductors
GlobalFoundries

Steel
Nucor Corporation

Travel
Amex GBT Egencia

Wine Products
Corticeira Amorim

Best Railway Transportation for Carbon Reduction

Africa
Lobito Atlantic Railway

Asia
Central Japan Railway

Europe
Go-Ahead Group

GCC
Etihad Rail

North America
CPKC

South America
Rumo Logística

Best Carbon Markets Projects

High-Integrity Carbon Project Developer
South Pole

North American Environmental Markets Broker
Anew Climate

Swine Livestock Farming
SinGEI Project

Wealth Management Awards 2025

The past year has seen the wealth management industry navigate an environment defined by market volatility, shifting client expectations and accelerating digitalisation. As inflationary pressures and geopolitical uncertainty shaped investor sentiment, advisers and firms have been challenged to deliver consistent performance while preserving trust and transparency. At the same time, the rise of holistic financial planning, sustainable investment options, and AI-driven client engagement tools has continued to redefine what excellence in wealth management looks like. The World Finance Wealth Management awards winners of 2025 exemplify the adaptability and insight required to meet these evolving demands. They have demonstrated not only strong performance, but also a commitment to long-term client wellbeing, innovation and ethical stewardship.

Best Wealth Management Providers

Argentina
Santander Wealth Management

Armenia
Wilco

Australia
Westpac

Austria
Kathrein PrivatBank

Bahamas
Scotia Wealth Management

Bahrain
Ahli United Bank

Belgium
Degroof Petercam

Bermuda
Butterfield Bank

Brazil
BTG Pactual

Bulgaria
Compass Invest

Canada
RBC Wealth Management

Chile
BTG Pactual

China
ICBC Private Banking

Colombia
BTG Pactual

Denmark
Nykredit

Estonia
Raison Asset Management

Finland
Nordea Private Banking

France
BNP Paribas Banque Privée

Georgia
Bank of Georgia

Germany
Commerzbank

Greece
Alpha Private Bank

Hong Kong
DBS Private Bank

Hungary
OPT Private Banking

Iceland
Islandsbanki Asset Management

India
Kotak Mahindra Bank

Indonesia
Hana Bank

Italy
BNL BNP Paribas

Japan
UBS SuMi Trust Wealth Management

Kuwait
NBK Wealth

Liechtenstein
Kaiser Partner

Lithuania
INVL

Luxembourg
BNP Paribas Wealth Management

Malaysia
Bank of Singapore Wealth Management

Mauritius
Stewards Investment Capital

Mexico
Santander Wealth Management

Monaco
Banque Richelieu Monaco

Morocco
BMCI Groupe BNP Paribas

Netherlands
ING Private Banking

New Zealand
Bank of New Zealand

Norway
Nordea Asset & Wealth Management

Oman
Bank Muscat

Philippines
EastWest Bank

Poland
PKO Bank Polski

Portugal
Santander Wealth Management

Saudi Arabia
NBK Wealth

Singapore
DBS Private Bank

South Africa
Investec Wealth and Investment

South Korea
Woori Bank

Spain
Santander Wealth Management

Sweden
SEB

Switzerland
Pictet

Taiwan
CTBC Bank

Thailand
Kasikornbank

Turkey
Akbank Private Banking

UAE
Emirates NBD

UK
Schroders

US
Northern Trust

Vietnam
Genesis Fund Management

Insurance Awards 2025

Resilience has once again been the defining quality of the insurance industry. In 2025, firms have contended with everything from the lingering effects of climate-related claims to the growing need for cyber coverage and digital underwriting. At the same time, the sector has made impressive progress in embracing technology – from AI-driven risk assessment to seamless customer experience platforms – all while strengthening its regulatory and sustainability frameworks. The winners of 2025’s World Finance Insurance awards embody this balance between innovation and reliability. They are the organisations that continue to earn policyholder confidence, deliver operational excellence, and redefine what responsible insurance looks like in a digital age.

Best General Insurance Companies

Argentina
Sancor Seguros

Australia
Insurance Australia Group

Austria
Helvetia Austria

Bahrain
Qatar Insurance Company

Belgium
AXA

Brazil
Zurich

Bulgaria
Uniqa

Cambodia
Infinity General Insurance

Canada
Intact Group

Caribbean
RBC

Chile
ACE Seguros de Vida

China
Ping An P&C Insurance

Colombia
Liberty Seguros

Costa Rica
ASSA Compañía de Seguros Pan American Life Insurance

Cyprus
Genikes Insurance

Czech Republic
KB Pojistovna

Denmark
Tryg

Egypt
AL Mohandes Insurance Company

Finland
Fennia Mutual Insurance

France
Groupama

Georgia
Unison

Germany
Allianz

Greece
Interamerican

Honduras
Ficohsa Seguros

Hong Kong
Liberty Insurance

Hungary
Groupama Biztosító

India
ICICI Lombard

Indonesia
Asuransi Astra Buana

Italy
UnipolSai

Japan
Mitsui Sumitomo Insurance

Jordan
GIG

Kazakhstan
Eurasia Insurance

Kenya
CIC Insurance Group

Kuwait
Qatar Insurance Company

Lebanon
AXA Middle East

Luxembourg
AXA Luxembourg

Malaysia
Etiqa

Malta
GasanMamo Insurance

Mexico
GNP

Myanmar
AYA SOMPO Insurance

Netherlands
Unive

New Zealand
Tower Insurance

Nigeria
Zenith Insurance

Norway
Tryg

Oman
Qatar Insurance Company

Pakistan
Adamjee Insurance

Peru
Rimac Seguros

Philippines
Standard Insurance

Poland
Warta

Portugal
Generali Tranquilidad

Qatar
Qatar Insurance Company

Romania
Omniasig VIG

Saudi Arabia
Tawuniya

Serbia
Generali Osiguranje

Singapore
Great Eastern

South Korea
Hanwha General Insurance

Spain
SegurCaixa Adeslas

Sri Lanka
Continental Insurance

Sweden
Hedvid

Switzerland
Helvetia

Taiwan
Cathay Century Insurance

Thailand
Thaiviat

Turkey
Zurich Sigorta

UAE
Qatar Insurance Company

UK
AXA UK

US
State Farm

Uzbekistan
Apex

Vietnam
BaoViet Insurance

Best Life Insurance Companies

Argentina
Magnal Life

Australia
Acenda

Austria
Helvetia

Bahrain
Al Hilal Life

Belgium
NN

Brazil
Sulamerica Cia Saude

Bulgaria
Uniqa

Cambodia
Forte Life Assurance

Canada
Sun Life

Caribbean
Sagicor

Chile
SURA

China
China Pacific Insurance

Colombia
Seguros Bolívar

Costa Rica
Pan American Life Insurance

Cyprus
Eurolife

Czech Republic
KB Pojistovna

Denmark
Nordea Life & Pensions

Egypt
Allianz Egypt

Finland
Localitapiola

France
CNP Assurances

Georgia
Imedi L

Germany
The Talanx Group

Greece
NN Hellas

Honduras
Pan-American Life

Hong Kong
China Life Insurance (Overseas)

Hungary
Magyar Posta Eletbizosito

India
Max Life Insurance

Indonesia
Great Eastern Life

Italy
Poste Vita

Japan
Nippon Life Insurance Company

Jordan
Arab Orient Insurance Company

Kazakhstan
Freedom Life

Kenya
Britam

Kuwait
GIC

Lebanon
Bancassurance

Luxembourg
Swiss Life

Malaysia
Zurich Malaysia

Malta
HSBC Life Assurance Malta

Mexico
New York Life

Myanmar
Prudential Myanmar

Netherlands
Aegon the Netherlands

New Zealand
Asteron Life

Nigeria
Sanlam Life Insurance

Norway
If Skadeforsikring

Oman
Qatar Insurance Company

Pakistan
State Life Insurance Corporation

Peru
Pacifico Seguros

Philippines
BPI AIA

Poland
Warta

Portugal
Fidelidade

Qatar
QLM Life & Medical Insurance

Romania
Metropolitan Life

Saudi Arabia
Tawuniya

Serbia
Generali Osiguranje

Singapore
Great Eastern

South Korea
Kyobo Life

Spain
VidaCaixa

Sri Lanka
Ceylinco Life Insurance

Sweden
Folksam

Switzerland
Swiss Life

Taiwan
Fubon Life Insurance

Thailand
Thai Life Insurance

Turkey
Zurich Sigorta

UAE
Oman Insurance

UK
Aviva

US
MassMutual

Uzbekistan
New Life Insurance

Vietnam
Prudential

Banking beyond borders

You have led iib through a significant global expansion. How do you define the institution’s core identity in today’s banking landscape?
iib isn’t just another commercial bank – we see ourselves as an intermediator between financial flows from developed markets to developing markets and frontier markets. We saw higher regulation and operating costs for western financial institutions post 9/11 and this accelerated post the Global Financial Crisis (GFC). We observed a mass exodus of western institutions facilitating banking in the emerging markets space. We look to fill that gap.

Our mission is to unlock the potential of regions often overlooked by mainstream banking. We believe in a value-led financial infrastructure: one that drives responsible growth, fosters inclusion and respects local dynamics. We are not just intermediating capital flows; we are reallocating confidence to the economies that would otherwise remain underserved.

You have expanded into regions like Cape Verde and are reportedly exploring further opportunities in Africa and the Caribbean. What is the logic behind that strategy?
The strategy is not Cape Verde, Djibouti, Bahrain, Dubai, or the Bahamas per se. What these specific geographies allow us is to build regional franchises. Economic and political stability, rule of law, and forcibility of contract and stable financial currencies allow us to rebuild a regulated banking footprint on a regional basis. Cape Verde allows us to build a regional banking franchise in Lusophone Africa, Djibouti allows us in turn to build a franchise to facilitate Ethiopian and regional trade and transaction flows, Bahrain and Dubai allow us to support clients regionally in the GCC and South Asia. The smaller markets where we have invested regulated capital allow us to build and leverage larger regional markets.

We are reallocating confidence to the economies that would otherwise remain underserved

We enter markets with patience, not as extractive institutions. We seek to build deep, permanent relationships. That is why we localise leadership, invest in financial education, and support ESG initiatives on the ground. For us, success isn’t just about financial return – it is about social and systemic return.

With rising digitisation in banking, how does iib position itself in terms of innovation and fintech integration?
Digital transformation is core to our strategy. For us as a bank that intermediates capital flows, transactionality and functionality are critical to our business model. Digitisation helps us achieve this better at a lower cost, enabling us to solve real problems. We prioritise digitisation in ways that lower transaction costs, increase access to capital, and improve transparency.

In many of our markets, traditional banks impose friction: high fees, rigid processes and limited reach. Our digital products, whether through mobile platforms or cross-border settlement tools, are designed to democratise finance. But we never automate empathy. We blend technology with human insight.

What is your perspective on the geopolitical role of banks today? Can banks remain neutral?
Banks are no longer neutral vessels. We live in a world where capital flows are political, data is currency, and trust is a geopolitical asset. Our role is to ensure that financial infrastructure remains resilient and independent of noise, yet conscious of context. At iib, we operate with the understanding that neutrality is not silence. We take principled positions: we stand for financial dignity, transparency, and long-term vision and growth. These are not political stances, they are human ones.

Some may see small international banks as too niche or fragmented to compete. What makes iib different?
Scale matters, as does clarity of vision. We may not be the largest bank in terms of balance sheet; however, our international reach allows us to do what we do in intermediating capital flows whether in commercial banking, transactional banking or trade finance, better than our peer group. Our structure allows us to be agile without compromising governance. We are backed by serious leadership, a prudent risk culture, and a long-term strategy that does not change with market winds.

Where others see complexity and risk in emerging markets, we have the ability to navigate the local operating environment, build banking infrastructure and systems and provide services and solutions at a cost at which others may struggle.

What is next for iib in the coming decade?
Our next chapter is about resilience and responsibility. We are investing in green financing, sustainable trade corridors, and building a decentralised ecosystem that empowers local institutions.

We are also exploring how AI and digital identity can reshape credit models for the underserved. But the compass remains the same: inclusion, transparency, and trust. Our ambition is to further enhance our position as a respected cross-regional bank operating with a relentless focus on customer relationships, financial inclusion and tailored solutions to shape the communities we serve.

The hidden risks in private credit’s $3trn boom

Early in 2025, the private credit market surpassed $3trn in assets under management (AUM) and has been one of the “fastest-growing segments of the financial system over the past 15 years,” according to an article by McKinsey. This meteoric rise has seen the industry grow by a factor of 10 between 2009 and 2023, adding $1trn in the past 18 months alone. The leading cause? Bank retrenchment. Traditional banking was forced to pull back following the global financial crisis in 2007–08, shifting away from traditional lending and becoming more reliant on debt markets and shadow banking.

Since then, of course, we have witnessed global economic uncertainty in the form of the pandemic, the Russia-Ukraine war, ongoing conflict in the Middle East and more recently, whenever the US President leaves a comment on social media or gets in front of a camera. Recent retrenchment isn’t solely driven by market volatility but also by tightening regulatory pressure, including Basel III Endgame proposals, which would require banks to increase their capital reserves in a range of lending areas and introduce liquidity rules that would reduce banks’ appetite for longer-term loans, according to McKinsey.

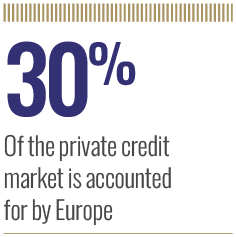
With the banks sensitive to market shocks and stymied by policy, private credit has moved in, with a recent EY report estimating that “Europe accounts for roughly 30 percent of the private credit market.” There are plenty of key drivers for growth across the continent, including investment in infrastructure and energy. Private credit is expected to play a leading role in the global green energy transition “with estimates suggesting that between $100trn and $300trn will be necessary by 2050,” according to EY. Private credit appears now to be a mainstay of the financial landscape, a counter-cyclical champion in times of economic turbulence, but what happens when private capital meets geopolitically unstable jurisdictions, and how exposed are financial markets to risks they can’t see coming?

The private credit explosion
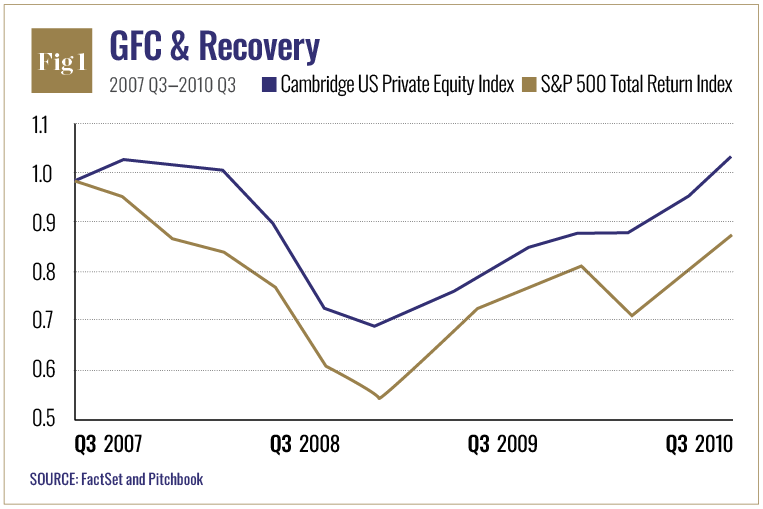
Post-GFC, the failure and near-failure of several ‘too big to fail’ banks helped trigger the Great Recession, the most severe downturn in the global economy since the Great Depression. Millions lost their homes, their savings and their jobs. While the economic downturn did have an effect on private credit, the data shows that “historically, private equity portfolios have generally experienced shallower peak-to-trough declines than the public markets,” according to a study on return patterns during economic downturns by Neuburger Berman (see Fig 1). While the banks had to limit their exposure, the private deal-making landscape bounced back during the later part of the recession, in 2009. The post-GFC environment was private equity’s first real stress test and it passed, albeit narrowly. A recent report on private equity during the Great Recession discusses how fund managers in private equity missed opportunities “to acquire high-quality assets at steep discounts” despite the surge in deals.

Analysts attribute the historic rise of private credit to three key characteristics. In stark comparison to the banks, PE has better access to capital and more freedom to deploy it, allowing it to increase market share and experience higher asset growth during crisis. Most global funds also have active management with a heavier focus on value creation. This provided decisive support for funds to develop new capabilities and drive transformation projects. Lastly, private equity is relatively illiquid, meaning that during economic downturns it can help insulate investors from panic selling, which typically comes with higher losses. With higher yields, bespoke terms and less oversight, the appeal of private credit cannot be overstated.

The past 15 years has seen private credit explode, but buried within this success story are reasons for caution. The most obvious is the illiquidity risk. While helpful during a downturn, the ability to get money out of an investment quickly is generally considered to be a good thing. Coupled with the fact that geopolitical instability is rarely priced in adequately, cracks could quickly form.

In comparison to market risks, geopolitical risks are incredibly difficult to hedge against. The effects of political instability, trade disputes, war, cyberattacks, climate change and natural disasters can be sudden and severe.

Not long before Russia’s invasion of Ukraine, Horizon Capital, Ukraine’s largest private equity group, had just launched its fourth flagship fund. Sarah de St Croix, head of private funds at law firm Stephenson Harwood, commented on the importance of having provisions in place to help fund managers respond to geopolitical developments. In this instance “affected managers were able to rely on their generic right to forcibly withdraw an investor from the fund where their continued participation breaches law or regulation.” Even though these clauses were drafted without a clear sense of when they might be needed, funds were able to “manage the problem of having a sanctioned investor in a commingled pool following the broad imposition of sanctions on Russian individuals in 2022.”

Private credit went global after the GFC, during a time when geopolitical risk wasn’t front of mind. Weijian Shan, executive chairman and co-founder of investment firm PAG, says “the geopolitical risks are very real nowadays. You used not to have to think very much about it. Now you really need to think about decoupling risks; you really need to think about restrictions to international flow of goods, people and capital.”

Resource nationalism
And this comes rather sharply into focus when you consider things such as sanctions risks, political unrest or local capital controls trapping foreign investments, or populist governments overturning investor protections.

The past 15 years has seen private credit explode, but hidden within its success story are reasons for concern

Indonesia, which produces 37 percent of the world’s nickel and is a major global exporter of coal, palm oil, copper, gold and other minerals, has been engaged in a decade-long programme of resource nationalism. Indonesia’s programme has coincided with heavy demand from China and as Dr Eve Warburton of the Australian National University notes, “over this same period, the Indonesian Government introduced more and more nationalist policies – new divestment obligations for foreign miners, a ban on the export of raw mineral ores, stringent new local content requirements and restrictions on foreign investment in the oil and gas sector.” Additionally and perhaps most tellingly, “observers noted an increase in court cases and popular mobilisation against foreign companies.” This is particularly significant given nickel’s essential role in electric vehicle batteries and renewable energy storage, placing Indonesia at the heart of the global energy transition.

Weighing up the risks
The private credit market must navigate considerable obstacles if it is to avoid becoming a victim of its own success. Rapid growth has increasingly pushed funds into new niches, often in emerging and frontier markets where the yield – and the risk – is highest.

In Geopolitical Influence and Peace, a report by the Institute for Economics and Peace, they state that “geopolitical risks today exceed levels seen during the Cold War, driven by heightened military spending, stalled efforts at nuclear disarmament and a diminished role for multilateral institutions like the United Nations.” At the same time, we are witnessing active wars in Ukraine and Gaza, the US-China decoupling, increasing political instability and polarisation, the spread of misinformation, and a rise in the use of cross-border sanctions and capital controls.

The risk of financial contagion is also a concern for the industry. Anyone who has loaded up on private credit – think pension funds, sovereign wealth funds or insurers – increasingly has their capital tied up in opaque, illiquid private deals.

Investors run the risk of being exposed to losses they neither anticipated nor adequately priced for. Any crisis in the private credit market could have a significant knock-on effect with the broader financial system. As private credit funds stretch further into higher-risk jurisdictions to meet yield expectations, the potential for sudden, severe losses rises dramatically.

Private credit’s success has been built on access to capital, flexibility, and the ability to go where banks won’t. But those advantages can quickly become liabilities in an unstable world. As geopolitical risk surges, private credit managers and their investors must rethink how they assess the rapidly changing modern landscape. The next market crisis may not start on Wall Street or in the bond markets – but in a foreign ministry, a war room, or a populist parliament. Private credit needs to be ready.

Europe’s neobanks eye American wallets

As one of Europe’s leading digital banks, Bunq hoped for quick approval when it applied for a US banking licence in 2023. One year later, the Amsterdam-based fintech firm withdrew its application due to a misalignment between US and Dutch regulators. The company is now making a second attempt, filing in April for a broker-dealer licence that will allow its US users to invest in stocks, mutual funds and ETFs. This is only the first step in an ambitious American adventure, says a Bunq spokesperson, adding that it will “start by making investing effortless and fully transparent, with no hidden fees,” possibly a jab at its US competitors and their practices. Bunq, which boasts 17 million European users, plans to reapply for a banking licence later this year.

Growth above all
Bunq is not the only European digital bank that is seeking expansion across the Atlantic. UK digital banking leaders Revolut and Monzo have also been eyeing the US market, riding a wave of renewed interest from investors following a post-pandemic funding crisis. The strategy is a no-brainer, given slower customer acquisition in Europe after a decade of manic growth and intensifying competition that compresses margins. A sense of urgency is also taking over the fintech market as it matures and fewer digital banks (also known as neobanks) are expected to become dominant globally. Some are in the black after years of losses; 2024 was Bunq’s second consecutive year of profitability.

One problem for neobanks is that they lag behind incumbents in the quintessential banking business: credit extension. Their lending operations are relatively small, meaning that revenue has to come from payment fees and premium accounts.

Regulation has also become stricter. “Europe has become increasingly hostile ground for fintechs, with tighter funding conditions and tougher regulations throttling growth,” says Carrie Osman, founder of Cruxy, a UK growth consultancy working with fintech firms. A wave of regulatory reform across the Atlantic, including the recent ‘1033 rule’ that has unlocked access to consumer financial data, has put the US on their radar, she adds. “The upside is that because they operate under more stringent regulations and thinner margins in Europe, they are better placed to innovate in transparency, cost efficiency and cross-border functionality,” argues Alessandro Hatami, former chief operating officer of digital banking at Lloyds Banking Group and author of Inclusive Finance: How Fintech and Innovation Can Transform Financial Inclusion.

A regulatory minefield
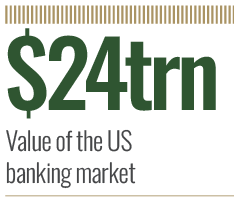
Despite these reforms, navigating the country’s Byzantine regulatory landscape remains an obstacle to conquering the $24trn US market. Obtaining a banking licence requires approval from state and federal regulators, while state-by-state money transmission licences are necessary to operate in several states. On top of a banking charter, aspiring lenders need to secure deposit insurance and proof of sufficient funds. Rising US protectionism adds an extra barrier, says Hatami: “Current instability in engagement with foreign providers is possibly making the rollout of a European fintech in the US problematic.”

Previous attempts faltered due to underestimating the complexity of US regulation

Dealing with US payment infrastructure can also be tricky. In Europe, neobanks benefit from interbank payment systems that enable customers to make transactions seamlessly, whereas US banks have been slower in adopting similar technologies. European entrants who view the US as a single market have struggled, says Dave Glaser, CEO of Dwolla, a US payment service provider, whereas opportunities exist for those who recognise that modernising their payment infrastructure involves adapting to America’s complex financial backbone.

Past attempts to crack the US market have proved traumatic. Monzo withdrew its banking licence application in 2021 when regulators warned that approval was unlikely. Berlin-based neobank N26 closed down its US operations in 2021, having failed to offer there its profit-making membership deals. Revolut’s delay in obtaining a UK banking licence made a US application practically impossible.

Without a banking licence, digital banks are unable to generate revenue through credit products. “Previous attempts faltered due to underestimating the complexity of US regulation, overestimating brand pull and launching without a compelling local value proposition,” says David Donovan, head of financial services North America at digital transformation consultancy Publicis Sapient.

For fintechs unable to obtain their own banking charter, partnering with a US bank is a no-brainer. Monzo has partnered with Sutton Bank to hold users’ deposits. Cleo AI, a UK fintech which offers personalised financial assistance through a chatbot, has partnered with Thread Bank and WebBank and boasts seven million customers in North America. The downside is that partners retain a share of card transaction fees, a major revenue source since they are significantly higher in the US. “It eats into your margins; you have less autonomy around product decisions; and you are often tied to the maturity of the partner bank’s risk and compliance processes, which can feel very outdated,” argues Stephen Greer, banking industry consultant at analytics platform SAS, adding: “This means the entry point to the US market is building services on top of a simple demand deposit account, which is a very low-margin product and typically doesn’t outpace your cost to acquire new customers.”

The recent collapse of Evolve Bank, triggered by its partner Synapse’s mismanagement of customer funds, has also intensified regulatory scrutiny of such partnerships. More ambitious neobanks have decided that going it alone is a bet worth taking. Revolut offers its card through its partner Lead Bank, but also has a US broker licence and is now seeking its own banking licence.

“The best strategy for a European fintech is to create a US entity and nurture this by tapping into the US investor markets, from venture capital all the way to IPO. And to play down its European roots as far as possible,” says Hatami.

Fierce competition
US retail banking is a competitive market, with over 3,000 institutions including regional banks, savings banks and credit unions, meaning that European fintechs must be prepared for slower growth and higher customer acquisition costs. US fintechs like Venmo, SoFi, Zelle and Chime have massive marketing budgets. “Word of mouth and referrals can only get you so far in the US,” says Dylan Lerner, a digital banking analyst at Javelin Strategy & Research, a US market intelligence provider. “You might have to spend some serious money to establish yourself – from heavy spending on advertising to naming rights on stadiums and sports sponsorships.”

The flipside is that new entrants can focus on niche markets that are large enough to be profitable. European neobanks can offer one-stop banking solutions to customers hungry for digital-first experiences with fancy add-ons on top of savings accounts, such as investing tools and real-time spending analytics. “Many US fintechs are built on banking-as-a-service models that limit control and innovation. European firms, having built more of their stack, can differentiate on both cost and customisation,” says Donovan.

Remittances is one potential revenue stream, notably offering cross-border and multicurrency services to around 20 million US-based immigrants. A case in point is the success of Wise, a platform that “addresses international money movement with a clarity and fee structure that is still uncommon in the US,” Hatami says. Bunq is also targeting digital nomads, “especially the nearly five million European expats who struggle with banking bureaucracy while pursuing a location-independent lifestyle,” according to the firm’s spokesperson.

Most companies want to list on Nasdaq or NYSE, raise a tonne of money and cash out

Cultural differences also come into play. American customers are more credit-focused than Europeans and are constantly offered customer rewards and loyalty deals, meaning that new entrants must provide expensive perks to lure them. Their loyalty to traditional banks is also rock-solid. “Americans are largely satisfied with their financial institutions. They are not eager to switch banking relationships,” says Lerner from Javelin Strategy & Research.

A recent survey by the firm found that 77 percent of consumers were unlikely to switch away from their primary financial institution. Foreign neobanks focused on business-to-customers solutions face an uphill battle due to relatively high customer acquisition costs, argues Kevin Fox, chief revenue officer at Thredd, a UK payments processor that recently expanded into the US and has helped several neobanks scale internationally. “Without a pivot to some differentiated credit product, prepaid and debit offerings often don’t generate enough revenue to warrant those costs,” Fox notes, adding that fintechs moving to a business-to-business model by providing solutions to SMEs, such as expense management services, have a better chance of US success.

Surprisingly enough, the biggest opportunity for European fintechs may be disrupting the technological backwardness of the US banking system. Perhaps the starkest example is the persistence of cheques, still widely used by banks and corporations, in a digital era. “What they [European neobanks] bring is primarily tech: fast onboarding, seamless user experience, a fully digital experience. That is not something the US banking system excels at yet,” says Arthur Azizov, founder of fintech alliance B2 Ventures.

Going public
For European fintechs, the biggest prize that comes along with US presence is the possibility of a public listing. US IPOs typically achieve higher valuations and provide access to the world’s biggest investment pool. Revolut and Monzo are expected to go public by the end of the decade, and their leadership has indicated preference for a US listing. Such decisions, however, have a political dimension that can cause friction at home. “Revolut was recently granted a banking licence – probably in part because of a promise to list in London, not in the US. Most companies want to list on Nasdaq or NYSE, raise a tonne of money and cash out. But governments want to keep their unicorns close to home,” says Azizov, adding: “For a serious US expansion, they will need to go all in: full teams, full infrastructure, full commitment. They may even need to move their HQ.” For sceptics though, going public might be a premature step without a clear US-orientated strategy and profitability model – the latter being the holy grail that will seal their position in the banking world.

“The real endgame is profitability at scale. This is something that has eluded most fintechs, regardless of listing venue,” says Donovan from Publicis Sapient. “It would prove that a digital-native, product-led model can work even in the world’s most competitive and entrenched banking market.”

Saudi cuts spark global ripples

When the Public Investment Fund (PIF) sneezes, a very large number of companies catch colds. And plunging oil prices have given Saudi Arabia’s massive sovereign wealth fund a definite case of the sniffles, with serious implications for a huge swathe of concerns.

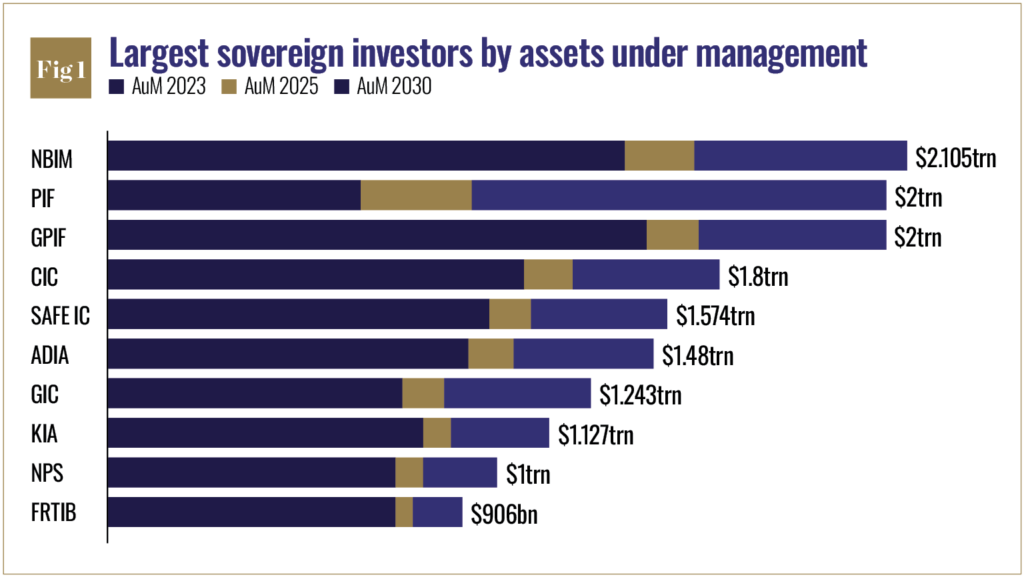
The PIF was worth $941bn in 2024, according to its latest annual report, making it the sixth largest sovereign wealth fund on the planet. Its assets rose almost fivefold in the eight years since 2016, a compound annual growth rate of 22 percent. It has a stated aim of seeing its assets under management pass $1.1trn by the end of 2025 and hitting $2trn by 2030 (see Fig 1). PIF has four global offices, and more than 2,500 employees.

Right now, however, the PIF is slowing down and cutting back, with serious implications for the more than 13 million foreign workers in Saudi Arabia and the many hundreds of companies that rely on the Saudi economy to keep going.

The fund, which was founded in 1971, has around 170 subsidiaries, and has been credited with stakes worth hundreds of millions of dollars at a time in household name companies including Facebook owner Meta ($522m), Disney ($500m), BP ($830m), Boeing ($700m), Uber ($2.7bn) and Citigroup ($520m).

The biggest single slice of its investments is in the energy sector, at 23 percent, followed by property, at 17 percent, IT at nine percent and financials and communications services are at around seven percent each.

It invested more than $100bn in the US alone between 2017 and 2023, generating, according to its own estimate, 103,000 US jobs and $33bn in GDP. By 2030, PIF claims, it and its portfolio companies will have invested $230bn in the US and supported the creation of more than 440,000 US jobs.

Controlling budgets
In the first half of 2024 the PIF was the world’s highest-spending state-owned investor, according to the consultancy Global SWF, and it was expected to raise its annual spending to $70bn in 2025, a year earlier than previously announced, according to the International Monetary Fund.

Another way to raise money in the face of falling oil revenues is to tap the bond markets

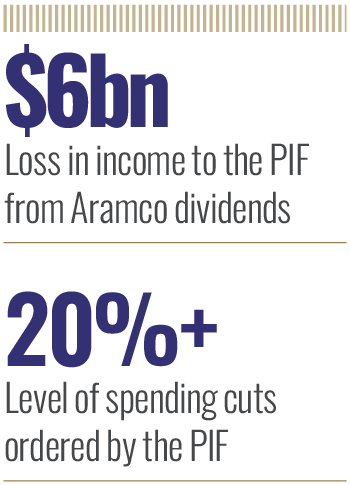
But this spring the PIF, which is chaired by Crown Prince Mohammed bin Salman, the de facto ruler of Saudi Arabia since 2015, ordered spending cuts of at least 20 percent across those parts of its portfolio where it can exercise control over budgets, which covers investments in around 100 different companies ranging from the Saudi start-up airline Riyadh Air to Newcastle United Football Club. The result has been layoffs, hiring freezes and project delays.

Some budgets have been cut by as much as 60 percent, according to the web-based business news service Arabian Gulf Business Insight (AGBI). The five so-called ‘giga-projects,’ massive real estate schemes such as Neom, a planned $500bn new city meant, eventually, to cover more than 10,000 square miles in the north-east of Saudi Arabia, and Red Sea Global, a huge effort intended to massively boost tourism to the country through plans such as a 1,500 square mile new tourist destination including 25 new hotels, have been particularly badly hit by the cuts.

A $5bn contract at Neom was cancelled the day before the signing ceremony was due to take place. A central part of the Neom project is a linear city called ‘the Line,’ originally billed as 170km long. After a host of delays, and amid claims reported in the Wall Street Journal of huge salaries for imported management and a toxic work culture, the initial stage of the project has been scaled back to just five kilometres to be completed by 2030.

There have also been reports of cash flow problems leading to payment delays for contractors, particularly in the construction sector, with one leading international contractor reportedly claiming it was owed $800m by Saudi clients. The company blamed prolonged payment delays as a significant factor in its decision to scale back operations in the kingdom. One big European construction company has allegedly withdrawn from the Saudi market altogether, blaming payment risks and financial uncertainties.

Oil prices decimated
The big problem, on the financial side, is the plunging price of oil. The International Monetary Fund has declared that oil needs to be $91 a barrel to balance Saudi Arabia’s budget. But oil has not been above $90 a barrel since August 2022. At Easter this year the price of Brent crude was down below $67, and the US crude benchmark, West Texas Intermediate, had fallen to less than $64, some 30 percent below that Saudi break-even price. Soon after, at the beginning of May, Brent had dropped to $61.63, which is 30 percent down on its 12-month high, and WTI to $58.56, also 30 percent down. The result is that the country’s giant state-owned oil company, Saudi Aramco, has already slashed its estimate for its total dividend payout for 2025 by almost a third, to $84.5bn, and may not even hit that. The PIF owns 16 percent of Aramco, and will thus see its own income from Aramco dividends drop by at least $6bn.

The PIF wants to, for example, spend money on the resorts being built along the Red Sea coast to eventually bring in 19 million tourists a year as part of Saudi Arabia’s ‘Vision 2030’ project to reduce its reliance on oil revenue. The main objective is to raise the private sector’s contribution to the country’s GDP from 40 percent to 65 percent by the start of the next decade. But the irony is that Saudi Arabia needs the oil revenue to fund the developments that are meant to eliminate the need for oil revenue.

Pat Thaker, editorial director for Middle East and Africa at the Economist Intelligence Unit, told FDI Intelligence that she expected “several large-scale initiatives may be re-evaluated, postponed or even scrapped due to financial limitations.”

World Cup commitment
One answer is to try to get more foreign investment into PIF projects. Money is required for several big and prestigious projects in the coming decade that Saudi Arabia has committed itself to, including international events such as the Asian Winter Games in 2029, Expo 2030 and the football World Cup in 2034. The country appears to be currently struggling to attract overseas interest: overall FDI flows in the third quarter of 2024 were down by 21 percent on the same period a year earlier, at $4.27bn, Saudi Arabia’s General Statistics Authority said.

However, in March, the PIF signed a memorandum of understanding (MoU) with Goldman Sachs to create funds to invest in Saudi Arabia and the wider Gulf region. The same month it struck an agreement worth $3bn with Italy’s export credit agency, Sace, saying that the deal provided “support for co-operation between Italian companies in the private sector and PIF and its portfolio companies.” It has also signed MoUs with Japanese financial institutions including Mizuho Bank, MUFG Bank and Sumitomo Mitsui Financial Group worth up to $51bn to help support funding via its local capital markets.

Another way to raise money in the face of falling oil revenues is to tap the bond markets. In January this year, the PIF unloaded $4bn of bonds in a sale that was four times oversubscribed, after attracting investors with credit spreads 95 and 110 basis points above US Treasury bonds. At the end of April the fund shifted $1.25bn in seven-year sukuk, or shariah-compliant bonds, with the offer more than six times over-subscribed. The eagerness with which investors have snapped up the bond issues at least eases fears that the news of enforced budgetary cutbacks could hit investor confidence in the giga-projects and the broader Saudi economy.

Phenomenal job creation
The PIF’s importance as a generator of employment cannot be exaggerated. By 2024, it is reckoned to have contributed to the creation of more than one million jobs in three years and supported the establishment over the same period of almost 50 companies in 13 strategic sectors. However, the effect of falling oil prices, a report by the consultancy JLL Middle East predicts, will be that employment growth in Saudi Arabia will plunge after hitting a high of nearly 10 percent in 2022, slowing to three percent by 2026 as the kingdom reins in spending.

This will affect a host of countries in the Middle East and South Asia that have been sending surplus workers to Saudi Arabia, and enjoying the wages they send back home. Nearly two million expatriates, skilled and unskilled, have joined the Saudi workforce in Saudi Arabia over the past two years. The country’s construction industry has more than doubled in size. But the slowdown means that workers are now looking for jobs elsewhere in the region, even if it means taking a pay cut to relocate or shift to other PIF-backed companies, according to Shyam Visavadia, the founder of WorkPanda Recruitment, a specialist in construction hiring based in Dubai.

In addition to the plunge in oil revenues, Visavadia told AGBI, “Giga-projects are scaling too quickly without long-term planning or clear strategy.” Now, future phases are “either postponed, remastered, or not receiving budget approvals,” he said.

Yet another problem is that the scale and complexity of the various giga-projects means that costs can easily exceed initial estimates. It appears the PIF may now be looking to prioritise projects with more immediate economic returns, and/or those that are further along in development.

The corporate cost of misinformation

Until recently, the chances of a company suffering any lasting damage due to a deliberate misinformation campaign were so low as to not even be included on the corporate risk register. But not anymore. Now, companies can see their share value nosedive overnight if a lie gains enough traction that customers boycott a company’s products and services over fabricated fears that they are unsafe, are made unethically, are of poor quality, or even linked to extremist groups.

The seriousness of the spread of false information should not be downplayed. The World Economic Forum’s (WEF) latest Global Risks Report cites government misinformation and disinformation as one of the key leading short-term risks that could fuel instability and undermine trust in authority. But it also warns that this growing trend could have a negative impact on corporates: for example, misinformation and disinformation around some industries could stifle growth and sales. For sectors like biotech, this is a serious problem, with biohackers and other non-medical professionals touting ‘unproven’ health remedies or performance-enhancing procedures and slamming ones that actually work, are regulated and are safe.

Furthermore, the WEF warns that some governments may foment aggressive misinformation and disinformation campaigns about goods and services from targeted countries, hardening public perception that could lead to more frequent consumer boycotts of products – hardly a welcome development in an era of increased geopolitical tension that has already spilled over into trade wars and spiralling tariffs. AI could exacerbate consumer boycotts further, it warns, as algorithms programmed to highlight trending or popular content could prioritise reader engagement over accuracy and unintentionally promote misinformation in the process.

Deliberate deception has the potential to destabilise or create financial or reputational damage

Unfortunately, companies can’t necessarily count on the law to correct falsehoods, remedy reputational damage, or regain financial loss, as it is supremely difficult to hold any person or company to account for spreading misinformation via the internet or social media sites. In the US, for example, online platforms are immune from civil liability for content provided by their users under Section 230 of the US Communications Decency Act. It also shields them from moderation activities that they undertake in good faith to remove certain content. And pursuing defamation claims in the US – or anywhere else – to try to right wrongs and gain financial redress is another costly gamble that not many organisations can consider.

Deliberate sabotage
“At its worst, deliberate deception has the potential to destabilise or create financial or reputational damage,” says Ant Moore, a senior managing director in strategic communications at business consultancy FTI Consulting. “Where misinformation is often fuelled by false information (a doctored photograph or an impersonated voice, for example), disinformation is characterised by a more deliberate attempt at sabotage. In all cases, literacy around determining fake content isn’t always where it should be.”

There are a range of ways misinformation can threaten companies. Besides consumer boycotts, false narratives can quickly shape public perception and erode brand trust, leading to loss of investor confidence and reputational harm. It can also lead to disengaged and polarised workforces, resulting in employees leaving or refusing to join organisations they believe are misaligned with their values. Misinformation campaigns that target specific industries can also create increased legal and regulatory scrutiny as authorities, shareholders and stakeholders demand increased assurance.

Some high-profile companies have already experienced problems. In 2016 the sportswear company New Balance faced considerable backlash on social media after misinformation circulated that the brand was closely aligned with far-right movements. Similarly, in 2022 Eli Lilly’s stock price fell by 4.37 percent after a fake Twitter account impersonating the pharmaceutical brand falsely announced that insulin would be given away for free (as opposed to the $1,000 monthly pricetag it could cost some US citizens without health insurance at the time). In 2023 the CEO of brewer Anheuser-Busch InBev Michel Doukeris blamed misinformation on social media for stoking a conservative consumer boycott of Bud Light that saw sales drop by a quarter after the best-selling US beer was promoted by transgender influencer Dylan Mulvaney.

“When it comes to the risk posed to corporates, the only surprise is that this hadn’t come sooner,” says Chris Clarke, co-founder of strategic comms agency Fire on the Hill. “Companies have been operating in an increasingly complex and globally connected landscape, with new forms of media growing in prominence. It makes information impossible to control and makes identifying trustworthy information from reliable sources harder than ever.”

Clarke continued: “In the current information environment – chaotic, fragmented and lacking in trust – the ground is fertile for misinformation to go viral and bad actors to purposely spread misleading and false information. Whether those bad actors are foreign governments targeting the economic interests of other states, activist groups, or competitors, deploying strategies to mitigate risks should be a top priority.”

Get ahead of the spiral
Given the speed at which false stories can be created with AI and proliferate and spread on social media, experts say companies need to learn how to proactively monitor for malicious stories in real-time before they spiral out of control. The challenge, however, arises in how companies currently monitor for these sorts of malicious attacks. “Historically, communications and PR teams have focused their attentions on tracking comments and trends across mainstream social media such as X, Instagram or TikTok,” says Rebecca Jones, associate director of client accounts at business intelligence firm Sibylline. “However, that is not where these disinformation campaigns begin, and arguably, by the time disinformation hits these sites, the issue has already gone viral and you are in crisis.”

You need to build a strong community of fans who love and support your brand

More often than not, says Jones, disinformation begins on alternative social sites, where the audience is more likely to react to a story that may seem a little unbelievable, but which triggers emotions: indeed, an issue can sit in this ecosystem slowly being refined and gathering momentum over the course of hours, days or even weeks before it migrates to mainstream and goes viral. Monitoring these sites for potential threats can be a game changer, as it can help teams to get ahead of a potential crisis before it takes place.

“Even if it can’t be stopped – which is usually the case – hopefully such an early warning mechanism enables teams to have a plan of action in place for when it does hit the mainstream: your executives are prepped, the press team is ready to respond, and perhaps you have even taken steps to pre-bunk the story,” says Jones.

Chris Walker, managing director of Be The Best Communications, says companies should make sure they control their own narrative. “Facts are more impressive than fiction. Gather your evidence which disproves the claim and which highlights your organisation’s commitment to doing the right thing,” he says. Companies should also challenge the source of fake news to reveal what evidence they have to back up their claim: if they can’t ‘put up,’ they may ‘shut up.’

Alice Regester, Co-founder and CEO at specialist communications agency 33Seconds, agrees that it is increasingly important for companies to control and have access to channels of communication to quickly debunk falsehoods. “The value of information companies are sharing via their owned channels is increasingly important,” she says, adding that this is a good way to “ensure they are building a voice of trust and authenticity on both websites and blogs, as well as social media channels, so consumers know they can come directly to the brand for the truth.”

Collaborate and amplify
Having friends is also a very useful weapon to deflect malicious claims, say experts: it can certainly pay for companies to identify potential spokespeople outside of their organisations who can be called upon to help push back against false narratives. Businesses can collaborate with customers, fact-checking organisations, consumer advocacy groups, and trusted media to amplify credible information. Building an influencer programme can also be a good way for companies to protect themselves, says Adam Blacker, PR director at website hosting information site HostingAdvice.com. “It is really hard to do everything yourself. You need to build a strong community of fans who love and support your brand. They in turn become brand ambassadors,” he says. So-called ‘social listening’ tools – essentially, software applications that companies can use to continuously scan social media sites for mentions of their name, brands, and industry trends – are also fast becoming critical solutions. By analysing conversations in real time, companies have the advantage of being able to verify and fact-check claims early enough to take action.

Andy Grayland, CISO at threat intelligence tech company Silobreaker, says traditional crisis management approaches are no longer sufficient – companies must transition from reactive damage control to proactive defence.

“Cyber threat intelligence (CTI) solutions provide that necessary early-warning system. By continuously monitoring brand-related risks across open-source intelligence (OSINT), including news sites, forums, social media, and the deep web, organisations can detect and neutralise threats before they escalate,” says Grayland. “AI-powered tools are now essential for cutting through the noise, identifying real risks, and flagging coordinated disinformation campaigns before they gain traction,” he adds.

As an example, such monitoring would detect and alert a pharmaceutical company if an anti-vaccine movement that normally averages 50 mentions of a particular drug brand a day suddenly increases that number to 500. By tracking the influencers behind these kinds of movements in real-time and identifying shifts in narratives relating to a company or brand, companies have a better chance of either engaging strategically or correcting the narrative.

Early detection translates into real business value, says Grayland. “With real-time visibility into emerging threats, businesses can mitigate financial losses, prevent reputational crises, and stay ahead of regulatory and shareholder concerns. In a world where disinformation spreads at the speed of social media, CTI tools provide the radar and response capabilities needed to protect brand integrity and the bottom line,” Grayland says.

While experts say that misinformation and disinformation are hardly new challenges, they add that their impact on companies has become far more acute – thanks to the scale and speed at which they can spread. “Businesses have always been vulnerable to false narratives, but the digital age and AI has turbocharged that risk,” says Ryan McSharry, crisis specialist at international PR agency Infinite. The difference now, he says, is the sheer volume and immediacy with which misinformation can erode trust and disrupt markets, making it a much more potent threat to a company’s reputation.

“The question isn’t whether companies should be concerned – it is how they should be responding,” McSharry warns.

Flight path to autonomy

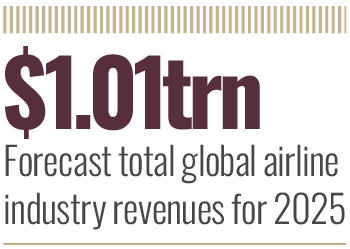
The global aviation industry has seen a number of developments in the last few years, such as more sustainable and green travel, electric aircraft and better maintenance, repair and overhaul (MRO) technology. The International Air Transport Association (IATA) expects total global airline industry revenues to reach $1.01trn in 2025. If so, this will be the first time that the industry’s revenues surpass the $1trn barrier, while also being a 4.4 percent rise from 2024.

Passenger numbers are likely to touch 5.2 billion this year, which would be an increase of 6.7 percent from last year. Cargo volumes are estimated to rise 5.8 percent on an annual basis and hit 72.5 million tonnes as well. This expected growth in the global aviation sector has led to several aerospace and tech companies attempting to develop autonomous airplanes.

At the moment, major sector giants such as Boeing, Airbus, Lockheed Martin and Northrop Grumman, as well as innovative tech start-ups such as Whisk, Joby and Elroy Air, are working on developing autonomous flight technologies and systems. Countries with strong government funding, sophisticated aerospace ecosystems and strategic defence priorities, such as China, the US and some EU nations, are leading this development.

The timescales involved
Although vehicles with varying degrees of autonomy have become more common recently, fully autonomous cars (level five) are not commercially available to the general public as yet. Similarly, fully autonomous airplanes could still take several years to be available on the open market, although related technologies such as automatic target recognition have been operational for a while now. Autonomous military and speciality unmanned aerial vehicles (UAVs) or drones have also been functional for years. Dan Bubb, aviation historian and associate professor in residence, UNLV Honors College, noted: “There is no doubt aviation technology continues to make giant leaps including in automation. Some businesses predict that autonomous aircraft will dominate aviation by the 2040s. I can envision that in the military, cargo, and general aviation sectors.”

Fully autonomous airplanes could still take several years to be available to the open market

Dr. Walter Stockwell, vice president of Engineering at ANELLO Photonics, also expects autonomous aircraft versions to be more adopted in surveillance, specialised missions and cargo in the near term, with broader commercial passenger applications likely to happen in the next 10–15 years. “Hybrid models combining autonomy with human oversight could be dominating the skies by the early 2030s,” Stockwell said.
The Covid-19 pandemic, ongoing Russia-Ukraine war and Middle Eastern tensions have all contributed to a surge in supply chain bottlenecks and constraints in the last few years. These have led to long shipping delays and detours, a shortage of certain products, as well as significant financial losses.

Autonomous cargo and logistics aircraft have the potential to largely reduce many of these constraints. As such, these could likely be ready for large-scale operations as soon as the next five to 10 years, according to Sylvester Kaczmarek, chief technology officer at OrbiSky Systems. However, one of the main factors affecting the timeline for autonomous aircraft is how long it takes to properly understand the risks around artificial intelligence and autonomy, as well as to bring about the appropriate legislation to regulate this technology.

Disrupting the aviation sector
Autonomous aircraft can enhance decision-making and situational awareness, especially when analysing data with AI. They can also make hazardous area and remote operations easier, while slashing operational costs and having the potential for 24/7 operations. These aircraft could drastically increase efficiency as well, mainly through optimised fuel consumption and flight routes.

Bill Irby, the CEO of AgEagle Aerial Systems, explained: “The potential payoff is huge. Airlines and military organisations have gone through many periods of shortages and surplus of pilots and flight crews. Implementing autonomy could help even out the staffing surges.”

Autonomy could mean that more AI technicians and remote operators are required, rather than pilots, significantly changing the landscape of the aviation labour market. Smaller airline crews overall may become the norm. New business models from urban air taxis to high-frequency cargo drones could potentially transform the aviation industry at every level, according to Stockwell. Other business models include rapid middle-mile cargo and specialised delivery and surveillance airplanes.

Michael Healander, CEO and co-founder of Airspace Link, believes that the immediate impact of autonomous aviation will be seen through drones in areas such as infrastructure inspection, emergency services and agricultural monitoring.

“As the digital infrastructure matures, we will see integration with traditional aviation that will eventually extend to autonomous air taxis that move people as well as goods, revolutionising urban transportation networks while generating new revenue streams for airports and municipalities,” Healander explained. On the other hand, autonomy will also affect air space management, while requiring the entire industry to bring in more regulations relating to safety, security and fair use of technology.

Crunching the numbers
According to a recent report by McKinsey, a number of companies developing autonomous aircraft could potentially need anywhere between $1bn and $2bn for the development, prototyping and testing needed for type certification alone.

Irby noted that some of those investments were already underway. “Several Advanced Air Mobility (AAM)-focused organisations are already investing many millions of dollars in this emerging area. Government offices are engaged as well, and given what has been underway for the last few years in combat zones, it is evident that government tech investments need to increase to develop and field these technologies at a faster pace,” Irby said.

According to Healander, the US is now in a prime position to lead in the higher-value segments of autonomous systems and airspace management infrastructure. However, more investments from US tech giants, logistics and aerospace companies will be needed to speed up this transition. New models of declaring airworthiness and new equipment standards from both government and industry are critical too.

“The countries that will ultimately lead this space will be those that best balance innovation with appropriate regulatory frameworks – creating safe systems for autonomous operations at scale rather than just manufacturing the hardware,” Healander said. To launch autonomous aircraft on a large scale, along with regulatory frameworks, investment also needs to focus on public acceptance and technological infrastructure.

The private sector needs to keep working on detect-and-avoid systems, aircraft design and command-control solutions, among other things. Along with that, public-private partnerships will be key in accelerating this transition. One of the other things required would be advanced inertial navigation systems (INS), which includes next-generation optical gyroscopes. Better AI and autonomous decision-making systems are also needed, which are capable of safety-critical and real-time judgements across the aviation ecosystem.

Looking at the challenges
Along with the significant financial investment needed, one of the main challenges with developing and scaling autonomous aircraft is creating strong detect-and-avoid capabilities that will ensure safety in dynamic and complex environments. Developing the robust digital infrastructure needed to handle millions of daily flights remotely is also difficult.

Irby highlighted: “True machine-learning and autonomy are very complex areas that require tremendous computing power. This is one pacing limitation if edge-autonomy is the intent, given the size-weight-power tradeoff for aircraft.”

With autonomous aircraft, I think it will take longer to convince the public

Irby added: “The other complex area is moral clarity and moral application of autonomy. Nations have differing views on the technologies’ application, especially when considering the preciousness of human life.” Navigating the changing regulatory landscape while retaining public trust can be tricky too, especially when vehicles already offering some autonomous features, like Tesla, continue to face issues.
Bubb said: “How do we regulate autonomous aircraft to ensure they are safe? Given the recent spate of crashes that have taken place, and the deep concern the public has about aviation safety, how do we overcome that concern? With autonomous aircraft, I think it will take longer to convince the public, and we will have to work even harder than we are now.”

However, he pointed out that rapid developments in aircraft technology such as better navigation instruments, aerodynamic efficiency and cabin design are very encouraging.

Real-world testing is also much more difficult for autonomous aircraft than it is for autonomous cars, despite some of their similarities. “A UAV cannot just pull over to the side of the highway if there is a problem – so access to airspace for testing and acceptance of test failures are critical to advancing the technology,” said Stockwell.

Another major issue is cybersecurity protection of autonomous systems, as well as a risk management plan in case of technical issues and outages, especially given the widespread impact of the recent Microsoft and Crowdstrike outage. Cybersecurity can ensure that key tools such as navigation, command links and onboard systems are protected from attacks.

Air traffic integration, which involves managing mixed airspace with manned and autonomous aircraft safely, can be difficult too. “We believe the foundation of successful autonomy lies in navigation technologies that are fault-tolerant, precise, and independent, ensuring autonomous flight is not just possible, but safe and scalable in all environments,” Stockwell concluded. n

From oil to opportunity

Project finance in the Gulf Cooperation Council (GCC) region is shifting. Hugh Morris, Senior Research Partner at Z/Yen, thinks this is because the market is maturing – particularly in terms of how political risk is seen in the region. This maturity has supported the creation of a pipeline of projects and funding because investors perceive that the geopolitical risks in the region are reducing, which permits more competition.

As a market the GCC is also attractive to them because in comparison the West offers lower risk and yields, and around the world there is a lack of low-risk, high-yield assets. Higher risk and higher yields tend to be available in the East. However, the Gulf sits in the middle of the two both geographically and from a risk profile perspective.

Morris therefore comments that lower risk makes it easier to finance projects, and so this is leading to an increased collaboration between international banks. While they have access to funds and the expertise in project finance, local GCC banks have the local market expertise and local contacts to ensure that a project is successful.

Risks nevertheless still exist. Some project finance contracts can last 20 years at least. Yet while repayments can take 12–25 years to complete, and while the duration of project finance deals is getting longer around the Gulf, many projects are refinanced early. As for debt financing, project owners do not guarantee repayment. That tends to come from any revenue that is generated from a completed and fully functional facility.

Repayment therefore depends on each project succeeding. This increases risk, and so banks expect to be paid a premium in return for accepting the high risks associated with it. To be competitive, lenders are offering better value deals. That is a hard prospect to achieve when they need to factor in industry rules on how much capital banks must hold. So, whenever the perceived or actual risk of supporting a project is high, banks understandably want to charge a premium in order to obtain a return.

Working collaboratively
With an eye on the increasing opportunity in the region, international banks, local banks, and credit agencies are working collaboratively to provide both short- and long-term financing. To get projects off the ground, project managers are opting for short-term financing, and over a longer period of time they typically replace bank financing with longer-term bond financing. “This enables them to lock in lower rates of interest and match long-term liabilities with long-term asset revenues,” Morris explains. It also permits the matching of revenue and costs to generate a return over the lifetime of an asset.

Saudi Arabia and the United Arab Emirates lead the pack in the Gulf, Morris says, because the largest finance projects are typically in one of those countries. A key driver is the “diversification away from oil and gas to build a post-oil and gas economy in Gulf countries,” and Morris suggests the nature of the centralised directives that emanate from their ruling families creates a short chain of command from political leaders to infrastructure projects.

For example, Morris reveals that “Saudi Arabia is investing in green hydrogen, and the UAE is investing in nuclear power. There are also major urban development projects, such as – in Saudi – the substantial development of Al Diriyah under the At-Turaif District Development Plan consisting of $50bn investment near Riyadh. The aim is to create a major cultural and tourist destination which will tap into the tourism market and replicate in Saudi Arabia what Dubai has achieved on the coast.” Nevertheless, a spokesperson for Bank ABC – Arab Banking Corporation, suggests that not everything is all rosy. It says there is allegedly a $5trn annual investment gap for clean energy and there are some COP29 shortcomings. The bank therefore feels that there is a need for financial institutions to take on a leadership role. This view highlights why so many of them are concentrating their investments on energy transitioning.

Project financing shift
However, there has also been a shift to financing projects such as hospital and education infrastructure. Ehab Nassar, a director at Fitch Ratings, comments: “It is coming on the back of the strategic shift away from oil dependency, and the governments are financing the projects as Public-Private Partnerships (PPPs).”

Banks expect to be paid a premium in return for accepting the high risks associated

Initially, before 2019, project finance was limited and GCC countries such as Saudi and the UAE began to develop their PPP frameworks in the GCC region’s bid to diversify away from oil and gas, while maintaining course with renewable energy and while moving towards social infrastructure.

Nevertheless, Christiane Kuti – a senior director at Fitch Ratings – says the Barakah nuclear plant in Abu Dhabi was not financed using a PPP structure. Instead, the finance involved a combination of debt and equity, including loans of $16.2bn from the Department of Finance of Abu Dhabi, and $2.5bn from the Export-Import Bank of Korea (KEXIM). There were also equity investments of $4.7bn from Emirates Nuclear Energy Corporation (ENEC) and Korea Electric Power Corporation (KEPCO) to establish the Barakah One Project Joint Venture Company.

The UAE recognised the project as being given a green loan because it is perceived by the authorities as playing a role in decarbonising the power grid, and for its contribution to the UAE’s green economy. Moreover, the project was refinanced in July 2023 by two leading Emirati banks: Abu Dhabi Commercial Bank (ADCB) and First Abu Dhabi Bank (FAB). They took over the loan facilities previously held by KEXIM.

Financing evolution
Abbas Husain, Head of Infrastructure and Development Finance at Standard Chartered, says there is a financing evolution in certain infrastructure projects in the GCC region. This is because re-financing is increasingly borne by the off-taker – the buyer of the product or service produced by a project. While structured on a ‘hard mini-perm’ basis, with a shorter date, they benefit from a long-term concession agreement.

The aim is to create a major cultural and tourist destination

Husain explains why this is invaluable: “Key benefits include lower financing cost that results in tariff competitiveness as well as an increase in liquidity to finance these projects. Deals are re-financed by project bonds or long-term commercial debt.” However, Husain adds that infrastructure projects, where the re-financing risk is not covered, “continue to be financed by long term commercial debt, including ECA financing which provides stability and cost-effective financing over the tenor.”

Credit agency support, from either export credit agencies or development finance institutions, is available to enhance the credit profile of projects. The aim is to make them more attractive to long-term investors. “This structure also facilitates access to alternative capital sources such as infrastructure funds and institutional investors that may otherwise be wary of early-stage construction risk,” Husain suggests.

Refinancing period
Mazen Singer – Partner in Infrastructure Finance at PwC Middle East, says that most project owners (sponsors) tend to want to refinance after a project has been operational over a period of five to eight years because the project will be at a stage where construction is complete, operations are stable, and at a point where revenue flows are more predictable.

Singer remarks: “At that point, the project’s risk profile has improved significantly, opening the door to more favourable financing terms, and this gives sponsors an opportunity to lower the overall cost of capital, optimise their debt structure, and in some cases, release capacity to fund future development.”

Singer warns that waiting longer could dilute some of the refinancing benefits, particularly as the remaining debt tenor shortens, and because this can reduce the positive impact of refinancing once a project is self-sustaining. However, Singer is seeing a broadening of the financing landscape in the region. For example, more export credit agencies are active. Singer says this reflects the scale of infrastructure investment there. This includes infrastructure funds that are “drawn by mature, cash-generative assets, and capital markets are increasingly receptive to well-structured opportunities.”

The Gulf is well-placed to be among the leaders of the next phase of global infrastructure financing

Husain adds: “As the Gulf has matured as a project finance destination, with better regulatory and governance frameworks, clearer procurement processes, and higher-quality sponsors, banks have become more comfortable with the risk.” Husain believes this is complemented by the region’s strong sovereign backing as the off-take risk is typically emanating from a state-owned utility “or back-stopped by a Ministry of Finance, which has reduced perceived credit risk, allowing banks to price more competitively.”

Morris suggests there are a sufficient number of completed projects in the GCC region to see a “pipeline of successful financing, and so the projects look sensible to invest in one after another.” The projects and the collaborative nature of financing and investing in them, Morris says, demonstrate the determination of the governments in the region to build a post-oil future that involves well-run infrastructure projects as they can be a very good class of asset for investment.
However, Morris warns, there is a need to maintain tight control of what investors take out in equity returns because they can be accompanied by debt loading. Morris argues this is what the regulator in the UK failed to do with that country’s water industry. This action left the industry saddled with debt, while investors took out handsome equity returns.

Still some work to do
Nassar and Kuti think there is still a lack of case history, which brings uncertainty. For example, the enforceability of security in the Gulf region and a higher level of transparency in the sharing of information are much needed. So there is still some work to do to reduce risk by enforcing laws, and by developing appropriate regulatory frameworks across the GCC.

Regulatory frameworks are key to boosting project finance across the region, as they will bring in the capital markets at a time when the funding needs are significant. This stage of development differs materially across the GCC, with the UAE and Saudi being the most advanced markets.

Husain concords with industry analysts that progress in project finance transformation is nevertheless significant within the Gulf. However, Husain would like to see a greater standardisation of PPP frameworks across jurisdictions to enhance bankability, and deeper secondary markets to support refinancing and portfolio diversification. If refinancing risk were borne by the off-takers, there would be an enhancement of liquidity for financing infrastructure projects.

Husain ends by saying that with continued regulatory innovation and stakeholder collaboration, the Gulf is well placed to be among the leaders of the next phase of global infrastructure financing.
To achieve this end, Singer concludes that the region needs to continue to attract and develop the necessary expertise and institutional capacity. That can be done by fostering national and regional champions in project finance.