America first, global health last?

When US President Donald Trump reawakened the venomous ghosts of his ‘America First’ mantra during his second inauguration in January 2025, few could have foreseen the tsunami of disruptions and chaos that he intended to unleash on the global arena. “During every single day, I will, very simply, put America first,” he said with his characteristic bravado. True to his words, Trump has unapologetically caused widespread turmoil, with the US global health programmes being among the biggest casualties. To the administration, the programmes were deeply broken, had become inefficient, wasteful and had created a culture of dependency.

Simply put, they were not serving the interests of the US despite billions in annual budgetary allocations. Trump was clear that maintaining the status quo would not be an option. The outcome is a completely different approach to global health assistance, anchored on the largely controversial and divisive America First Global Health Strategy (AFGHS).

“We must keep what is good about our health foreign assistance programmes while rapidly fixing what is broken. This strategy lays out a plan to do just that,” said Marco Rubio, US Secretary of State. For countries that for decades have depended on the US for health assistance, particularly in dealing with infectious deadly diseases such as HIV, TB, malaria, smallpox, burdensome non-communicable diseases and maternal and infant mortality, AFGHS is an extremely bitter pill. Worse still, the road to its unveiling on September 18, 2025, was paved with painful spikes.

It started with the dismantling of the US Agency for International Development (USAID), which for decades had been the face of US foreign aid with missions primarily concentrated in Africa and Asia. In Africa alone, USAID had committed about $132bn across health systems, economic development and humanitarian relief from 2001 to 2024. The health funding gaps created since its shuttering are widespread and devastating. Nigeria and Botswana are cases in point. The former was left with a whopping $600m hole, while Botswana lost a third of its HIV response funding. Notably, USAID was a key implementing agency of the $110bn President’s Emergency Plan for AIDS Relief (PEPFAR) that has saved over 26 million lives since 2003.

Global shockwaves
While the dismantling of USAID was bad enough, the decision by the Trump administration to withdraw the US from the World Health Organisation (WHO) sent shockwaves across the global health systems. Trump has never hidden his disdain of the global body, which he has accused of mishandling the Covid-19 pandemic, refusing to reform and being prone to undue political influence, specifically from China. For WHO, the US withdrawal was a major blow considering Washington was the top donor providing between 12 and 15 percent of its funding. In 2022–23, the US contributed $1.2bn.

Another layer of the paving was a mission to cut the US government’s global health aid funding, a plan scattered by US legislators who approved a $9.4bn package for the current financial year. Though a cut from the $12.4bn allocated in the 2024–25 financial year, the funding is $5.7bn more than what the Trump administration wanted. A key aspect was the fact that Congress upheld funding for programmes such as PEPFAR, the Global Fund to Fight TB, AIDS and Malaria, and HIV/AIDS.

“The US must understand that a withdrawal from global health commitments makes the world – and therefore the US – less safe and less healthy,” says Michele Barry, Director of the Centre for Innovation in Global Health and senior associate dean for Global Health at Stanford University. She adds that Covid was proof that diseases do not respect geopolitical boundaries and is evidence that weakened healthcare systems anywhere in the world can have ripple effects on the US. Despite attracting unprecedented criticism, the Trump administration contends that the AFGHS will make the US safer, stronger and more prosperous. Through the strategy, the US intends to pivot away from open-ended aid to a system that puts emphasis on accountability, clear objectives and defined milestones within stipulated timelines. In essence, the era of blanket funding is gone.

The administration has built a strong case for AFGHS. Top of the list is the need to address inefficiency and wastefulness. Of the billions allocated for foreign health assistance annually, less than 40 percent is used for supplies and healthcare workers. Of this, approximately 25 percent is used for the purchase of commodities while the remaining goes to employing healthcare workers. The fact that 60 percent is spent on ambiguous expenditures and overhead smacks of wastage.

A serious wastage problem
PEPFAR is the poster child of wastage, according to the US State Department. Of its $4.7bn budget, the programme spent $1bn on medical commodity purchases, transport and delivery and $600m on its 270,000 frontline workforce. The remaining $3.1bn was spent on activities such as training, mentorship, supervision, and quality management among others. AFGHS is also designed to cut out the roles of non-governmental organisations (NGOs) in US-funded programmes. To the Trump administration, NGOs have been co-conspirators in aiding wastage with their ‘perverse incentives’ enabling them to self-perpetuate. For the strategy to be effective in saving millions of lives and assisting countries in developing resilient and durable health systems, removing NGOs from the equation and transitioning programmes to local ownership is seen as critical.

The health funding gaps that have been created are widespread and devastating

Though saving taxpayers’ dollars is paramount, the pillars on which AFGHS stands are causing disquiet across the globe, specifically among countries that are dependent on US health assistance. With regards to keeping America safer, the US intends to strengthen global surveillance systems to detect outbreaks to ensure quick response before they reach its shores. Part of this will involve posting a larger number of staff in geographies perceived as high-risk when it comes to outbreaks. To some, this amounts to an invasion of countries’ independence in managing the sovereignty of their health systems.

With regards to making America stronger, the plan is to enter into strategic multi-year bilateral agreements that require countries to co-invest, while on the prosperity pillar, the US will be seeking to create markets for its companies and innovators. Specifically, countries that sign the agreements will be required to open their markets to US health innovations and products. Africa, where the US is aggressively pushing AFGHS, is a key target considering that US pharmaceutical exports to Africa account for only 4.4 percent with India, China and Europe dominating.

“The US is clearly leveraging its central position on the global stage as one of the few actors capable of mobilising financing at scale in an increasingly extractive and transactional way,” states Lami Mabifa, a consultant at Africa Practice. He adds that the explicit linkage between global health cooperation and US national interests could prove highly disruptive.

This is already happening. Critics reckon AFGHS is not only exposing the globe to vulnerabilities of outbreaks but is also a clear representation of modern-day biomedical imperialism by the US. Since its launch in September 2025, at least 28 countries (22 of them in Africa) have signed memoranda of understandings (MOUs) with the US. Most have signed under duress because they need to fill gaps in health funding, a reality amplified by the fact that Africa’s health sector faces a staggering $66bn in annual financing gap.
For the countries that have signed the bilateral agreements, US State Department data show Washington has availed $12.7bn in assistance with partner governments contributing $7.8bn in co-financing commitments. This notwithstanding the fact that most countries are feeling the heavy weight of co-investing. A case in point is Nigeria. While the US is contributing $2.1bn, the country is required to raise $3bn, an amount that is close to 40 percent of its 2025 health budget allocation.

Spending commitments
While at one level the co-investment provisions respond to a longstanding concern across Africa that external aid can foster dependency and leave health systems vulnerable when donor funding is withdrawn, on another level it is locking countries into spending commitments that are difficult to meet. The challenge is compounded by the fact that in some of the MOUs, the US is tying financing to sensitive data sharing. For instance, countries are required to share biological specimens and genetic sequence data of pathogens with epidemic potential in the shortest time possible after detection. Besides, some agreements have locked data and specimen sharing arrangements for up to 10 years, well beyond the funding cycle.

These conditions have become the breeding grounds for resistance. Zimbabwe is among countries that have turned their backs. Despite being eligible for $367m in US funding, Harare refused to commit after it was told to share sensitive data. A near similar situation unfolded in Kenya, the first country to sign the MOUs. Despite securing $1.6bn in funding, implementation was suspended by the High Court over concerns on data protection and the constitutionality of the agreement. In Zambia, the US plans to arm-twist the country and tie a $1bn funding to access to critical minerals such as copper, cobalt and lithium ended up backfiring.

“Global health crises cannot be contained through a patchwork of bilateral agreements,” notes Barry. She adds that outbreaks demand cooperation, coordinated, multilateral responses rooted in trust and shared responsibility. “Retreating from multilateral institutions undermines both US security and global preparedness.”

Part of the reasons why the agreements are being termed as ‘patchworks’ is because they are time-bound (averaging five years) and also contain withdrawal clauses, with any party free to exit upon giving a notice of 180 days. This creates room for abrupt disruptions of programmes, some of which are designed to run for years
The dollar’s greatest threat is America itself

Economic historian Barry Eichengreen has long been one of the most insightful guides to the global monetary system. In his recent book Money Beyond Borders: Global Currencies from Croesus to Crypto, the George C. Pardee and Helen N. Pardee Professor of Economics and Political Science at the University of California, Berkeley, turns his attention to how money is evolving in a world of rapid technological and geopolitical change. From the rise of stablecoins to shifting power between the dollar and emerging challengers, Eichengreen explores what it means for global currencies to move ever more freely across borders while governments try to retain control. The book blends economic history – from ancient Greece to medieval Florence, Amsterdam and then Britain’s handover of global financial leadership to the US – with sharp analysis of today’s monetary debates. In this exclusive interview with World Finance’s correspondent Alex Katsomitros, Eichengreen reflects on how domestic political challenges affect the dollar’s global status, the risks and opportunities posed by innovation, and whether dollar dominance can endure in a fragmented world economy.

What is the biggest threat to the dollar’s dominance right now?
The US itself. Not the economy, but rather US politics. Global currency status has political as well as economic and financial preconditions. These domestic political preconditions are at risk at the moment. Global investors have to be confident that the rule of law, separation of powers, control of corruption and respect for Fed independence are intact. They have to be confident about the country’s foreign policy, whether its alliance policies are sound and stable, whether the US is still regarded as a reliable alliance partner because central banks, governments, firms and commercial banks use the currency of partners who are viewed as reliable stewards of their holdings. There are questions about that.

Would a more isolationist Fed undermine the dollar’s global status, given its role as a global lender of last resort?
The Fed has played an important role by extending dollar swap lines to foreign central banks, which is a foundation stone of the global dollar. Foreign central banks will only be comfortable about seeing banks and firms under their jurisdiction holding dollars if those central banks can act as dollar lenders of last resort because they can swap their currencies for dollars with the Fed. If we have a nationalistic US president who insists on nationalistic behaviour by the central bank, things will be different. Take President Trump’s supposed temporary appointee to the Fed Board, Stephen Miran, who thinks the US should not provide global public goods by acting as a global lender of last resort and that we should demand recompense prior to doing that. Kevin Warsh wants to shrink the Fed’s balance sheet. Will a central bank with a smaller balance sheet that focuses narrowly on its domestic responsibilities still act as a global provider of dollar liquidity? I have my doubts, and this makes me even more worried about the prospects of the dollar as a dominant global currency.

Are there any parallels between what the Nixon administration was doing in the 1970s to deal with the balance-of-payments deficit and what the Trump administration is doing now with tariffs?
There are two parallels. One, both administrations wanted a weaker dollar to boost export competitiveness and address that balance of payments weakness. The reason Nixon imposed a 10 percent import surcharge in August 1971 was to allow the dollar to depreciate without other governments depreciating their currencies. Only after that currency alignment was he prepared to remove the import surcharge. That is similar to the Mar-a-Lago Accord. We hear today that the dollar should be devalued, and tariffs are used to induce foreign governments to go along. The second parallel is that it didn’t work then, and it’s not working now. The dollar is item number 10 down the list of determinants of US competitiveness. That competitiveness depends on our productivity growth; investment in the skills and training of our workers; entrepreneurship; capital investment; tax system efficiency. Further down on the list comes whether the dollar is 10 percent higher or lower.

Most economists consider the dollar an exorbitant privilege for the US. Some, however, even in President Trump’s circle, suggest that it is a burden. What do you think?
I see both sides of the coin. There have been dominant currencies in the past that faced problems of international competitiveness or overvaluation because of the large global demand to hold them as reserves. That was the case of Florence in the 15th century, Amsterdam in the 18th century, and the UK in the late 19th century and early 20th century. My evaluation is that the benefits outweigh the costs. The benefits are convenience, being able to do cross-border business in your own currency, which aids competitiveness; funding the Treasury’s debt at lower cost because there’s demand for Treasurys; an automatic form of insurance that you are the safe haven currency and funds flow into your markets when volatility spikes, rather than experiencing capital flight and financial market collapse. Finally, your financial sanctions are more effective than they would be otherwise.

When the euro was created many people expected it to compete with the dollar. Why hasn’t this happened?
The euro has gained zero ground on the dollar as a global currency since 2001. The reason is resistance from special interests and lack of political will at the national level. There are three prerequisites for a larger global role.

One, a capital markets union, which would create a more liquid market in euro-denominated government securities. But the banks don’t like this idea; they want to hold on to their part of financial business for investment funds in Luxembourg and Ireland. They want to keep regulation at home rather than allowing it to migrate to Brussels or Paris, where it would foster a capital market union.

Two, there is a shortage of safe euro-denominated assets. There are only three European governments with triple-A ratings from all rating agencies. They have around €3trn worth of government securities between them, compared to $30trn to $40trn worth of US Treasurys. The EU could issue more bonds of its own. There are schemes where the EU would buy up national government bonds, and use the interest paid to it by national governments to issue and service its own bonds. But national governments are reluctant to see those schemes implemented.

Three, there is no common EU defence and security policy. Leading global currencies are the currencies of political entities that can secure their borders and build strong alliances with foreign partners. The EU and its citizens are beginning to think about the importance of not relying on the US for security and building that common EU policy. But there is this famous observation that 13 different EU countries are producing 13 different tanks. How can you have an effective tank battalion on the battlefield, absent greater integration?

Do you consider the renminbi a stronger rival to the dollar?
The playbook the Chinese authorities are following is taken directly from what the Fed did, starting in 1914, to promote use of the renminbi for cross-border trade settlements with China itself, and once that process is underway, to promote purely financial transactions. They are building the relevant infrastructure, the Chinese cross-border interbank payments system with close to 200 direct participants and 1,600 indirect participants. They have an electronic platform, mBridge, built with four other monetary authorities and central banks. They are moving as fast as they can. The People’s Bank of China has extended more currency swap agreements to foreign central banks than the Fed or the ECB. But they are starting out way behind.

They have been internationalising their currency for a little more than a decade. The US has been doing so for more than a century. The US accounts for nearly 60 percent of global foreign exchange reserves. China accounts for two percent. China’s cross-border renminbi transactions have been growing at double-digit rates, whereas their growth has slowed down. Nothing in China is growing at double-digit rates anymore. And then there are the political obstacles. I described my doubts about US politics and how that can negatively affect the dollar. Checks and balances, rule of law, regulatory transparency – these are not characteristics of the Chinese political system. Will they grant independence to their central bank? Will they allow competing political parties? Obviously not in my lifetime.

Are stablecoins a threat to the dollar’s dominance – or a digital tool to preserve it?
I would distinguish the token from the payments rails, which are blockchain or distributed ledger technology. One of my book’s themes is that financial and payments technology is always changing. Blockchain and distributed ledger technology is here to stay and will provide another vehicle through which cross-border transactions are completed. We don’t know what kind of units will run on those rails. Will they be privately issued stablecoins? 99 percent of them are linked to the dollar. Or will they be a combination of tokenised commercial bank deposits and central bank digital currency (CBDC) to create finality? Those units can also run on a permissioned blockchain. Both the ECB and the People’s Bank of China are betting on tokenised commercial bank deposits and a CBDC. In the US, Congress has prohibited the Fed from issuing a CBDC. My view is that we are betting on the wrong horse and that privately issued stablecoins may turn out not to be stable and fungible. If Amazon and Walmart issue stablecoins, will we be able to use Walmart Coin at Amazon and Amazon Coin at Walmart? Tokenised bank deposits take advantage of an already existing banking system inside the regulatory perimeter that is important for stability. Commercial banks have already made progress in figuring out how to issue and manage a CBDC. Time will tell which horse ends up winning the race.

What would a world without dollar dominance look like?
It would make for a more fragmented global monetary and financial system. If you imagine a dollar area, a euro area and a renminbi area, it’s important to design these areas to overlap with one another and maintain a semblance of transactions between them. Imagine a scenario where China and the countries around it do business only in renminbi and the US is on such bad terms with China that we do no business using the renminbi. We know from the 1930s that is disastrous. So we have to design monetary systems where the blocs can do business with one another.

Fast and reliable execution is our priority, says Interstellar Group (FISG) director

Interstellar Group (FISG) is a leading CFD broker, serving more than 112,000 clients across four continents. Amir Amidian, Director of Research and Analytics at Interstellar Group, discusses FISG’s latest tech innovations to improve execution and enhance its trading infrastructure, Interstellar’s multiplatform educational offering, and its award-winning reputation for consistency and putting clients first.

World Finance: Amir, how is Interstellar Group leveraging the latest tech innovations to improve your services?

Amir Amidian: Interstellar continuously invests in technology to improve both our trading infrastructure and overall the client experience.

Our priority is super simple: traders need fast, reliable execution. That’s why we have invested heavily in high-performance servers and network infrastructure to ensure stability, low latency, and consistent execution.

Last year, we introduced FLUX 1.0, our proprietary execution accelerator, which further enhances platform performance, even during the periods of high market volatility.

World Finance: Many jurisdictions are tightening up regulations around CFD trading – how is Interstellar responding to this?

Amir Amidian: With more than 15 years of experience, regulatory compliance has always been at the heart and core attention of our business.

As regulation continues to evolve, we proactively strengthen our internal controls, enhance our reporting standards, and continuously improve our due diligence and risk management process.

Today, we operate under respected regulations including Cyprus SEC, ASIC, FSCA, and also FSA, while actively pursuing additional licences for all around the world.

Our objective is pretty simple: building long-term trust by providing a secure, transparent, and compliant trading environment for our traders.

World Finance: Now, how does Interstellar help traders improve their skills?

Amir Amidian: So, education is one of our pillars for the business, because informed traders tend to make better long-term decisions.

We provide a complete learning ecosystem designed for both new and experienced traders.

Our educational resources range from trading fundamentals for beginners to advanced market analysis; delivered through webinars, seminars, e-books, and practical market insights by our different platforms.

Take our Youtube Channel, FISG Interstellar Group, for example. We have launched about six major educational series on it, which we constantly update and provide completely for free for all of our traders.

Shows like Guess Now, Pro Talk and Trading Tips are already popular, and I highly recommend traders pick the content based on their own skills and also experience.

World Finance: Finally, you’ve received a number of awards in recent years – how has FISG developed and maintained its glowing reputation?

Amir Amidian: So we are deeply gratified to have received numerous honours recognising our excellence across trading environment, trading conditions, partner programmes, client services and integrity.

However, we believe our reputation has been built on something more important, which is consistency.

Our clients value reliable execution, transparent pricing, and strong regulatory standards; and that’s exactly what we focus on in our day to day.

By continuously investing in technology and education, maintaining high compliance standards, and also putting our clients first, we have built long-term trust.

Our vision is to become a century-long global brand, recognised not only for our innovation, but for delivering a good, secure, transparent, and dependable trading experience for generations of traders.

Cybercrime emerges from the dark web

When Cybercrime magazine predicted in 2020 that the scourge of cyberattacks would cost the world $10.5trn by 2025, many considered the estimate to be wildly exaggerated. In fact, it is turning out to be absolutely correct. The actual cumulative cost of cyberattacks in 2024 was $9.5trn and, although the figures aren’t yet out for 2025, the rate of increase is on target. Considering that the price of these pernicious economic invasions was $3trn in 2015, cybercrime has clearly become a growth industry of apocalyptic proportions. If cybercrime were seen as an economy in its own right, it would be the third biggest in the world after the US and China. And the damage is mounting by the day.

As Cybercrime magazine’s editor-in-chief Steve Morgan wrote at the time about the exponential danger of these attacks: “They represent the greatest transfer of economic wealth in history, risks the incentives for innovation and investment, is exponentially larger than the damage inflicted from natural disasters in a year, and will be more profitable than the global trade of all major illegal drugs combined.” Legendary investor and economic philosopher Warren Buffett agrees, describing cybercrime as mankind’s main problem and ranking it as a bigger threat to humanity than nuclear weapons.

Assembly lines hit
Many victim companies can attest to that, as the following recent examples show. South Korean e-commerce platform Coupang took a hit in December 2025 that stole the personal details of nearly 35 million users. A month earlier, attackers cracked the commercially sensitive data of over 200 companies connected through the system of Salesforce, a customer relationship management platform. In September the assembly lines of British automotive giant Jaguar Land Rover ground to a halt for several weeks after the shadowy Spider group of young hackers mounted a ransomware attack that cost the group about $2.2bn in lost production. And in April cyber-criminals penetrated the digital and in-store operations of one of the UK’s favourite retailers, Marks & Spencer, with devastating effect – the group suffered a loss of between £200m–£300m. This has been coming for a long time.

Warren Buffett described cybercrime as a bigger threat to humanity than nuclear weapons

The founder of a cyberprotection company told me years ago how he was able to convince sceptical major banks that they were highly vulnerable. “I asked the board permission for my experts to try and hack into their systems,” he said. “I estimated it would take 20 minutes.” And it usually did.

Just about every day these attacks are ravaging businesses, governments and other organisations worldwide. “In 2025 major cybercrime attacks on businesses were dominated by massive cryptocurrency thefts, sophisticated third-party vendor breaches, and disruptive ransomware,” reports the Centre for Strategic and International Studies. To take just ransomware, also in 2025 a gang was able to halt emergency services across several American states in an attack at OnSolve, a critical risk management provider, in a CodeRED alert system breach.

Hardly a month passes without a damaging and sometimes crippling attack by a wide variety of cybercriminals that run from computer-savvy youths who think it is fun to government-sponsored agencies engaged in systematic industrial espionage. For instance, according to the Centre for Strategic and International studies, in December 2025 a Russia-linked group named Electrum knocked out about 30 sites in Poland’s energy grid. In January 2026 Pakistan’s Transparent Tribe launched a campaign on a wide variety of Indian institutions including government departments in retaliation for fighting on the border. Also in January a unit of Russia’s military intelligence service placed a creeping multi-stage infection in government departments in Central and Eastern Europe. In a nice irony, around the same time Russia was hit in what was surely a spoof attack, when deliveries of the Vladimir Bread Factory, a key regional producer, were thrown into chaos after a tit-for-tat raid corrupted its online systems.

State-sponsored cybercrime is highly organised. In March another Russian cybercrime cell demanded payment after breaching the systems of the German Democratic Socialist Party while, in America, Iranian hacker Handala heavily disrupted the operations of Stryker, a manufacturer of medical devices, in what it claimed was retaliation for the US bombing of the girls’ school in the south of the country. Few countries are immune. In another example of state-backed cyberterrorism, all four of Singapore’s biggest telecommunications companies suffered a months-long invasion by UNC3886, a China-linked group, in July 2025.

Dark web
Cybercrime investigators say the dark web, impenetrable to everybody except skilled practitioners, has become a gigantic pool for the malware, exploit kits and other tools that are used to inflict economic mayhem. These weapons have become so powerful that they could disable the economy of a city, state or even an entire country.

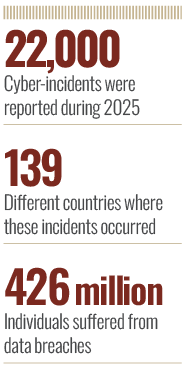
But cyberattacks also cause untold damage at all levels. As insurance industry magazine Atlas records, citing the Data Breach Investigations Report, there were more than 22,000 cyber-incidents in 2025 involving public and private organisations in 139 countries. Individuals count among the victims, no less than 426 million suffering data breaches.

The hardest-hit nation is the US, followed by France, India, Germany and Russia. “Data breaches are no longer isolated incidents but a real threat that has become an integral part of today’s digital environment,” notes Atlas. In other words, any enterprise that has an online presence could be in the firing line.

Although the rapid spread of artificial intelligence is blocking some of these attacks, the economic damage continues to mount. In 2025 the average cost of a cyberattack was put at $4.44m but it is more than double that in the US at $10.2m. At this rate we are heading to financial Armageddon, according to the IMF. As just about every business, big or small, goes online – or works with others who are online – the risks multiply. “This phenomenon generates colossal economic costs that could affect macro-financial stability on a global scale,” the IMF warns, forecasting cumulative losses of $23trn by 2027 incurred from direct losses triggered by ransomware, data theft, embezzlement and fraud, among others, as well as indirect costs such as reputational damage, legal fees and regulatory fines. For instance, in a typical example of collateral damage the British government had to come up with an emergency £1.7bn loan to prop up Jaguar Land Rover and its lengthy chain of suppliers.

No industry is safe. In 2025, the worst year so far for cybercrime, Japanese brewer Asahi had to stop all production across the entire Asia-Pacific, while Australia’s Qantas airline suffered a data leak of about five million customers. While the latter attack didn’t shut down the system, the carrier was immediately hit by an avalanche of class-action threats and official fines that some sources say could go as high as $4.6bn.

The ingenuity of cybercriminals keeps improving. One of their favourite scams is known as ‘CEO fraud’ whereby the criminal poses as the boss by using artificially generated videos and voice to trick an employee into transferring money or disclosing commercially confidential information.

Although there is insurance cover against cybercrime, it is expensive in what is a fast-growing market. In 2024, according to market sources, premiums valued at $15.3bn were written in 2024 and they are rising all the time. One of the giants of the industry, Munich Re, estimates the market will hit $32.4bn by 2030. But of course the economic damage has already been done.

Non-state actors
Digitisation lies at the heart of what experts see as a phenomenon that could play havoc with life as we know it. “Over the next two decades militancy, terrorism and organised crime will profoundly change as non-state armed actors adopt many of the same technologies used by conventional armies and everyday society,” warned experts from American think tank, Brookings Institute, in early 2026 in a chilling assessment of where things are heading. “Criminal and militant groups are already espousing many emerging and existing technologies – using drones for smuggling and violence, artificial intelligence systems to develop new synthetic drugs, and digital currencies to hide and launder money.”

Previously, the Brookings Institute argues, terrorists, drug cartels and quasi-military groups needed large swathes of territory to wage crime and exercise control by physical domination. “Today however, new technologies, such as synthetic drugs production, digital payment systems, artificial intelligence and networked devices, are eroding the traditional benefits and reasons for holding territory, especially its role in generating revenue,” the institute explains. This may prove to be a prophetic observation that identifies AI-enabled scams, online fraud, ransomware operations and cryptocurrency-based laundering that yield “earnings larger than the taxation of legal or illegal economies.”

The institute’s calculations suggest that the new wired, always-on brand of criminals rack up global profits of over a trillion dollars a year – and up to hundreds of billions in the US alone. “Over time, these activities will supplement and increasingly displace more traditional sources of income for criminals and militants,” it concludes. And they are running less risk. Without troubling the underground arms market that is under constant surveillance by the authorities, well-organised Brazilian gangs are printing high-powered rifles by 3D – ‘ghost guns’ that can’t be traced. And, learning from the military, targets can be taken out from great distances by relatively cheap drones.

The overall consequence is that it will become much harder for traditional law enforcement to police crime that is committed far from where the damage is caused. As experts warn, a handful of individuals are already running automated scams, deepfake identity fraud and algorithmic phishing, often from locations like basements in distant cities that are hard to detect. In short, economic havoc can be caused remotely on a shoestring.

The ‘AI-first’ CEO

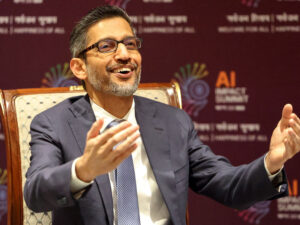
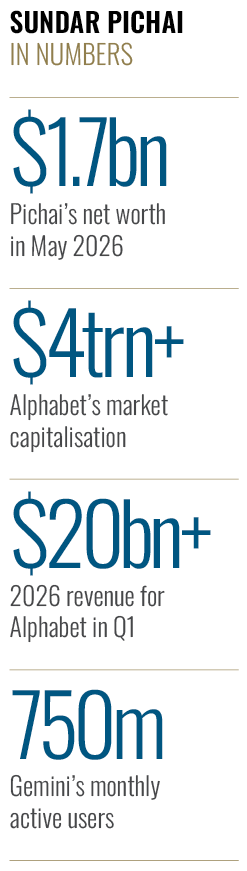
Every day, Google processes billions of search queries. As the most-visited website in the world, it owns the vast majority of global market share among search engines. But the technology behemoth is, of course, much more than a search engine alone. Google’s parent company, Alphabet, is behind several technologies that have become integral to daily life for huge swathes of people, from Google Maps and Gmail to Android and YouTube. Newer products, like Gemini, a generative artificial intelligence (AI) chatbot, and Waymo’s self-driving cars, are also taking off. In Alphabet’s first quarter earnings of 2026, the company said the number of paid subscriptions of the Gemini app had reached 350 million, while Waymo had launched in six new cities in 2026 and surpassed 500,000 fully autonomous rides per week, doubling in less than a year.

Sundar Pichai, the CEO of Google since 2015 and Alphabet since 2019, has not only led the tech giant to these incredible milestones, but he has also been the driving force behind several Google products that grew from unlikely upstarts to household names, such as Google Chrome and Drive. However, compared with the bosses of his competitors, Pichai takes a quieter, behind-the-scenes approach.

“Sundar Pichai’s career path is rooted in product leadership rather than founding mythology, and that shapes how he runs Alphabet,” Joe Crist, a cybersecurity and IT services CEO of Transform 42 Inc, which helps organisations scale sustainably, told World Finance. Crist puts Pichai’s success down to this brand of steady leadership. “He operates as a scale leader, focused on maintaining stability across a highly complex organisation rather than constantly reshaping it. That consistency gives engineering teams continuity and avoids the kind of frequent strategic shifts that can disrupt execution.”

Despite the monumental successes Pichai has overseen, the question on every investor’s lips today is whether the tech giant’s momentum can be sustained through the AI race, and whether its vast network of users will hinder its innovative potential or help it to come out on top.

Humble beginnings to tech titan
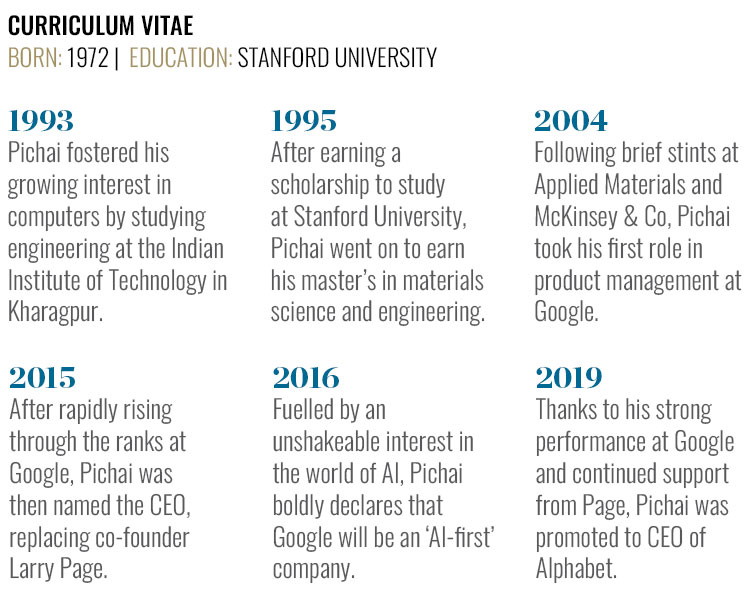
Born and raised in Chennai, southern India, Pichai arrived in the US in 1993 with a scholarship to study at Stanford University, where he earned his master’s degree in materials science and engineering. Not long after that, he obtained his MBA from the University of Pennsylvania’s Wharton School.

Pichai took up brief roles at semiconductor manufacturer Applied Materials and management consulting firm McKinsey & Co, but he had always been drawn to the allure of Silicon Valley. “I used to read about what was happening in Silicon Valley, and I wanted to be a part of it,” Pichai said in a 2014 interview at Delhi University. In 2004, he began his career at Google with a product management role. His first project was Google Toolbar, a feature that made it easier for users of Microsoft’s Internet Explorer and Mozilla Firefox web browsers to integrate Google’s search engine.

From there, he was soon promoted to vice president of product development, and he played a key role in developing Google’s own web browser, Chrome. This was no mean feat. “When we built Chrome, we had one percent market share one year after we launched,” Pichai told Time. Now, Chrome is the most used browser in the world. As the years passed, Pichai continued to climb the ranks, helped by an almost uncanny ability to create products and software that customers really wanted. “He has an exceptional sense for craft and the details in a product, all the way down to the pixels on the screen, the sound of a voice, the tactile feedback,” Clay Bavor, who worked under Pichai at Google for a decade, told Time magazine. Pichai soon became a right-hand man to Google co-founder Larry Page. “Sundar has a tremendous ability to see what is ahead and mobilise teams around the super important stuff,” Page wrote in a memo in 2014, announcing Pichai’s promotion to lead Google’s core products. “We very much see eye-to-eye when it comes to product, which makes him the perfect fit for this role.”

Pichai’s steady successes saw him reportedly pursued by tech rivals Twitter and Microsoft for leadership roles, but his loyalty to Google was rewarded with the top job in 2015, when Page and Sergey Brin created Alphabet as an umbrella company.

His work at the helm of Google, and later, after Page stepped down, Alphabet, included the creation of the Pixel smartphone; the launch of Google Home, previously known as Google Nest following the $3.2bn purchase of Nest Labs in 2014; and a strong push for AI innovations. Pichai’s achievements propelled Alphabet’s market capitalisation over the $4trn mark in early 2026 – only the fourth company to ever do so – and his own net worth to approximately $1.7bn, according to Forbes.

“Pichai’s leadership trajectory is closely tied to product execution at planetary scale,” Will Steward, who has nearly two decades of experience advising fast-growing tech employers and jobseekers as CEO and co-founder of The SaaS Jobs, told World Finance. “His early work on Chrome and later Android positioned him at the centre of Google’s distribution infrastructure, which effectively became the foundation of the company’s global reach,” he said. “That background has shaped a leadership style focused on system coherence, where success is measured by how well large platforms function together rather than isolated product breakthroughs.

“As chief executive, he has presided over a shift from single-discipline dominance in search advertising towards a multi-layered platform business,” Steward continued. “His approach has been to unify and ensure that infrastructure, advertising, devices and cloud services remain technically aligned. This has allowed Google to evolve without losing continuity across its core systems.”

While Pichai’s career has risen to dizzying heights, he came from a modest upbringing; it has been reported that he and his brother slept on the living room floor of a small family home growing up, and Pichai once said his father spent a year’s salary on his plane ticket to California so he could attend Stanford.

The journey of Sundar Pichai is one where opportunity and ambition collided to create a monumental success. “If he wants to do something, you’re not going to be able to stop him,” Caesar Sengupta, a former Google colleague, told Time magazine. “He is just going to be super nice about it. And then, you cannot move him.” Indeed, Pichai has generally been well liked as a leader at Google. In more recent years, however, he has faced criticism: first from Timnit Gebru, an AI ethicist who was fired in 2020 and said Pichai and other managers created “hostile work environments,” and more recently over sweeping job cuts.

Pichai’s story also champions the transformative power of technology – something that he is a firm advocate for. Growing up, Pichai had limited access to tech. He described being on a government waitlist for a rotary telephone for five years, and the radical impact when the family finally got one. “When you see the appetite and the desire for people to make their lives better by gaining access to technology, that is what compels me to go beyond,” he said in a 2022 interview on Stanford’s View From the Top podcast.

The AI race begins
Today, technology is quickly reaching heady new heights. Ever since OpenAI’s ChatGPT burst onto the scene in 2022 and transformed the general public’s understanding of the real-world potential of AI, investors and market watchers have sought to predict which of the Magnificent Six tech firms will come out on top. Some industry observers criticised Google for moving too slowly. Yet, as early as 2016 Pichai had declared Google to be an ‘AI-first’ company, shifting from a focus on mobile. For years, Pichai has worked in the background to shore up a strong foundation of custom-built chips, research and infrastructure to propel Google into the AI arms race. Today, Gemini accounts for a quarter of all AI traffic, up from just six percent last year, according to Similarweb.

AI will touch every aspect of our lives, every aspect of society, every industry sector”

“Google is structurally strong in AI due to its full-stack control of model development and distribution,” said Steward. “Its custom silicon, global compute infrastructure and long history in deep learning research give it an end-to-end capability that few competitors can match. This enables efficient training and deployment cycles at a massive scale,” he pointed out. Google acquired DeepMind, its AI research lab, back in 2014, and it has spent the years since making quiet breakthroughs on everything from voice recognition to image processing. In 2016, DeepMind made headlines when one of its neural network models beat a world champion in Go in a five-game match. It was a clarifying moment for Pichai. “I understood the potential of the technology to make sharp jumps,” he told Time. Since then, he has pushed Google to implement AI in practical ways for users.

The company’s integration-led approach has allowed it to become, seemingly, an overnight leader in AI technology. “Instead of focusing primarily on standalone AI tools, the strategy is to embed AI capabilities directly into existing products, which means new features reach users through systems they already rely on without requiring behaviour change,” Crist told World Finance. Google has a leg up here compared to any new tech start-ups. “Users don’t need to adopt entirely new platforms, which makes adoption more realistic in regulated or risk-sensitive environments,” Crist says.

Google Search, for example, integrates generative AI models into its core of information retrieval. “Search is evolving from a list-based interface into a synthesis layer where AI-generated responses reshape how users interact with web content,” said Steward. “This is a fundamental product transition rather than a feature upgrade.”

Even with one of the strongest AI research capabilities in the sector, Crist argues that Google’s true defining asset is its controlled deployment of AI features. Steward agreed: “Compared with competitors, Google’s advantage lies in vertical integration. It can train models, deploy them, and immediately place them inside products used daily by billions of users. That loop between infrastructure and interface is one of its most powerful assets in the current AI cycle.”

In-built ease and collaboration align with Pichai’s personal philosophy around AI. Speaking on the Harvard Business Review’s IdeaCast podcast in 2023, he described AI’s inflection point as being driven by human–AI collaboration.

“Software engineers often do something called pair programming. We have found that two programmers working together are better than them working separately,” he said. “So you can now imagine AI being your paired programmer or paired financial analyst or name if you will. So I think that’s the direction, that’s the promise and we are seeing it happen.”

Uncertain future
While AI has the power to transform life for many, Pichai is aware of its risks, too. In fact, speaking to the widespread fear of AI eating up jobs, Pichai admitted that the role of CEO would be “one of the easier things maybe for an AI to do one day” in an interview with the BBC.

What’s more, Pichai has himself become “unsettled” by “the power of what is possible” with AI. On the IdeaCast podcast, he described engaging with a large language model with a persona of the planet Pluto. Together with his son, he had conversations with the chatbot and described it as a “wonderful learning tool” that could offer facts about the solar system. “But there was a moment talking to Pluto at some point I felt like it felt very, very lonely and the conversation slightly went to a darker place, and that was my first experience, which kind of unsettled me and showed the power of what’s possible, the effect it can have on humans,” Pichai said.

It made sense, he went on, considering the context: Pluto is in a cold, faraway place in the universe, “So no wonder that it kind of started taking some of those attributes in its personality.” But after this experience, he said he strives to balance the “amazing opportunities to be unlocked” with responsible innovation. “These are powerful models, and I think a lot of us are working on making sure we build in safety systems, we add a layer of responsibility before we really widely deploy it. It is part of the reason I think as Google, we have been more conservative in our approach given the scale at which we serve users,” Pichai said.

While Google’s AI capabilities have seemed to appear suddenly, in reality they are projects many years in the making. But with the AI race in full swing, Pichai has no intention of slowing down now. In fact, he is stepping up capital expenditure on AI. Earlier this year, Pichai announced that Alphabet would double capex spending to up to $185bn, well above analysts’ forecasts of $120bn. “Our capex spend this year is an eye towards the future,” he told investors. “The demand we are seeing across the board for our services – and what we need to invest in Google DeepMind and in Cloud – is exceptionally strong.”

Having long been an AI advocate, it is no surprise that Pichai is all in on the technology. Speaking on IdeaCast he called AI a ‘deep platform shift.’ “Many years ago I called AI the most profound technology humanity is working on and will ever work on, more profound than fire or electricity. And that was the reason we said our company is going to be AI first,” he said. “It will touch every aspect of our lives, every aspect of society, every industry sector, if you will.” And while many people are laser focused on generative AI thanks to the huge leaps seen by chatbots, Pichai believes this is just “a moment in time” and “one aspect of AI.”

“I think there is more progress to be had, and I do think we will go through some moments of ups and downs, but the progress I think will continue. I think we should channel all this excitement to make sure other stakeholders are getting involved,” he continued. From governments to nonprofits and academic institutions, Pichai is keen to see international communities coming together to develop frameworks to align on safety and responsibility for AI.

Regulation and red tape is nothing new for Google – Pichai has had to deal with European regulatory roadblocks and lawsuits in the US for alleged monopoly tactics. Speaking on Harvard Business Review’s IdeaCast, he said AI is “too important an area not to regulate, and also too important an area not to regulate well.”

While he urged allowing technology to develop in its early stages, he acknowledged that safeguards should be built at the same time. In particular, he called for a framework where governments or regulators could validate AI models and ensure they are safe for public use. “We need to embrace the excitement and channel it in a way in which as society, as humanity, we are building the foundational blocks to tackle what is coming our way as well,” he said.

This is evidenced in Google’s approach to AI, which “prioritises reliability within established workflows,” Crist says. “In sectors like healthcare or finance, that discipline matters more than speed. A fast but unstable AI tool creates operational risk, not efficiency.”

An AI superpower?
Alphabet is better positioned today to compete in the AI race than many had thought would be possible a year or two ago, Dhruv Datta, who specialises in mobile app development, told World Finance. “Alphabet appears to have significant depth,” Datta says, pointing not only to Gemini but also Google Cloud, custom-designed chips and years of AI development experience with Google’s search engine and Android platforms providing distribution channels for these technologies.

But technical capability alone is not enough to create a true AI superpower. “In order for AI to become widely adopted, it will need to be perceived as trustworthy, capable of delivering results rapidly, valuable and economically viable on a massive scale,” he said.

Is Pichai the man for the job? According to Neal Mohan, the CEO of YouTube, Pichai’s insights with AI “foreshadow these huge trends, but they are also very, very precise,” he told Time. Crist described his leadership style as “deliberate, incremental and low drama,” all of which has helped Pichai to steer a company of Alphabet’s size and technical depth steadily, especially during periods of regulatory pressure and cultural scrutiny. “This is not a style built on constant public repositioning or dramatic pivots, but one of operational control and consistency at scale, which is often underestimated in large technology organisations,” Crist said.

Going forwards, Datta said he believes Pichai’s biggest test will be achieving balance. “On the one hand, he must continue to safeguard the core search business which still drives nearly all of Alphabet’s revenue. At the same time, he will need to enable a transformation of how search operates. He will also need to make significant investments in the infrastructure required for AI applications while demonstrating that those investments generate sustained economic value.” And, perhaps most importantly, he “must be able to do so quickly without damaging the trust and reliability users currently place in Google,” Datta said.

In a time of revolutionary technologies, the temptation to ‘move fast and break things’ is great. But while Alphabet’s size may slow it down, Pichai has shown time and time again that being the first is not the same as being the best.

Can Britain still create a Norway-style wealth fund?

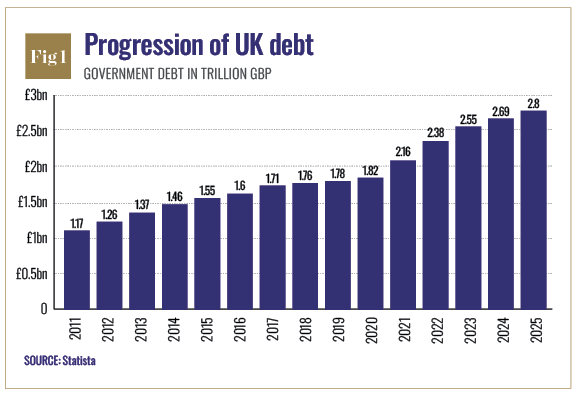
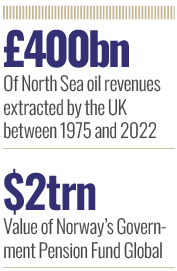
Norway and the UK struck oil in the North Sea at roughly the same time, extracting comparable riches over the ensuing decades. However, while Norway built a financial fortress, courtesy of its Government Pension Fund Global, which is currently worth over $2trn and continually compounding interest for future generations, the UK chose to spend, tax, and move on, and is consequently sitting with £2.8trn of national debt with the government borrowing just to cover day-to-day spending. But any honest answer as to what went wrong, and whether anything can be salvaged, runs straight into uncomfortable territory because the arithmetic only works one way: more drilling, not less. And with the Energy Profits Levy hitting 78 percent total effective tax on North Sea operators in 2026, that conversation has become urgent, taboo and long overdue.

How Norway built a $2trn fortress
Norway’s oil story didn’t end with extraction; it began there. The idea for a Norwegian oil fund was first conceived in 1960, as the then Prime Minister, Einar Gerhardsen, and his government claimed sovereignty over the ‘Norwegian continental shelf.’ Oil was first struck in 1969, but it wasn’t until 1990 that the government passed a law to create the Government Petroleum Fund, with the simple principle: oil wealth is finite, but financial capital doesn’t have to be. The first deposit arrived in 1996, and today, the fund is approaching $2trn, owns roughly 1.5 percent of all listed companies worldwide, and gives each Norwegian a theoretical stake worth hundreds of thousands of dollars.

As soon as revenues flowed into general expenditure they flowed out almost as quickly

The Norwegian Fund doesn’t just have scale, but discipline. All oil and gas revenues flow directly into the fund, rather than being spent on day-to-day government needs. The money is then invested globally, in the same way as the Norwegian central bank’s foreign exchange reserves, across thousands of companies, including major stakes in US tech giants, turning North Sea oil into a diversified, income-generating portfolio.

Crucially though, Norway spends only the expected long-term return, around three percent annually, under its fiscal rule, preserving the core wealth for future generations. Managed independently by Norges Bank Investment Management, the system has largely remained insulated from political short-termism. There is no secret here, just a sustained national choice to save rather than spend.

The UK’s squandered opportunity
The UK, meanwhile, extracted approximately £400bn in North Sea oil revenues in today’s money between 1975 and 2022. But, unlike Norway, not a penny of it was saved in a long-term wealth vehicle. All of it went into the general spending pool, and most of it vanished without structural trace.

The critical fork came in the 1980s. While Norway was quietly establishing the architecture of what would become the world’s largest sovereign wealth fund, Margaret Thatcher’s government was using North Sea revenues for something more immediately pressing in the UK: managing the social cost of deindustrialisation such as unemployment benefits and redundancy payments. Oil money funded the transition of the politically necessary, and economically brutal, dismantling of British manufacturing, and then disappeared.

What followed was decades of spend-as-you-go, under successive governments. As soon as revenues flowed into general expenditure they flowed out almost as quickly. Nothing ring-fenced, invested or compounded. But the painful detail is that Britain was warned. Economist Wynne Godley and others argued explicitly for a Norwegian-style fund in the 1970s, before the money arrived in volume, but the proposal was roundly rejected by the then incumbent Labour government, led by James Callaghan. That wasn’t ignorance but a choice. The UK didn’t lack the resource, expertise, or the blueprint, it simply lacked, at the time, the political will to defer gratification, and chose, repeatedly and consciously, to spend tomorrow’s money today.

The Energy Profits Levy and what is left
If the UK ever hopes to emulate Norway, it must start with what remains, but that picture is far less forgiving than it once was. The Energy Profits Levy (EPL) 2026, introduced in 2022 to capture energy company windfalls during a price spike, now sits at the centre of the debate. At its peak, the levy raised a few billion pounds annually, although it’s a fraction of what decades of disciplined saving might have produced.

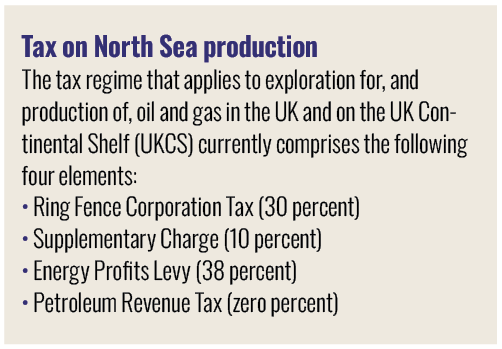
Layered on top of existing North Sea taxes, the levy pushes the effective rate on oil and gas profits to 78 percent, and critically, it is being applied to a shrinking base. North Sea production has been in long-term decline since its late-1990s peak, with fewer new projects coming online and exploration activity slowing sharply. The result is that the levy has become something the industry plainly calls ‘a going-out-of-business tax’.

There is also a growing tension at the heart of policy that nobody in government seems too keen to resolve; the zealous commitment to net zero while relying on dwindling fossil fuel revenues, and taxing the sector heavily even though it discourages the investment needed to sustain it.

This raises an uncomfortable reality: even if Britain chose to ‘go Norwegian’ tomorrow, it would be doing so with a mature basin, reduced output, and far less time to act.

Could the UK actually do it?
If we strip away the nostalgia, the question becomes clinical: what could Britain realistically build if it started today? The North Sea still holds an estimated 2.9 billion barrels of oil equivalent (BOE) of proven and probable resources, with contingent resources standing at 6.2 billion BOE, and prospective resources estimated at 4.6 billion BOE. At current prices and under the existing EPL regime, that translates into meaningful revenue. But meaningful is not the same as transformative.

Norway’s Government Pension Fund Global didn’t just magically appear overnight; it took more than two decades of disciplined accumulation to reach its current scale. Starting now, even under optimistic assumptions with stable prices, restructured taxation, sustained investment, and a political commitment to ring-fence revenues, the UK could potentially build a reasonably sized fund over 20 to 30 years, but still a fraction of Norway’s position, and dwarfed by the UK’s £2.8trn debt pile. There are three problems in creating such a fund; scalability, governance, and politics, which compound each other.

While the scale problem is real, it is manageable. The governance problem, however, is harder. Norway’s fund works precisely because successive governments can’t easily raid it. Whereas British political culture, with five-year electoral cycles, structural short-termism, and chronic pressure to spend, has never successfully maintained a long-term fiscal vehicle. The Treasury would need ring-fencing robust enough to survive at least six or seven governments. That’s not a technical challenge, but a cultural one.

The political problem may also be the most difficult to overcome. Any serious attempt to build a sovereign wealth fund requires renewed North Sea investment, which, in turn, requires restructuring the EPL and a government to publicly argue that increased fossil fuel extraction serves the national long-term interest. But in 2026, that argument is considered politically radioactive, even where the economic logic is sound. So, while a British sovereign wealth fund is theoretically possible, it’s practically very difficult, and politically near toxic.

Killing Net Zero to save the economy
If a future government wanted to do this seriously, it would need honest policy design. The first step would be to restructure the EPL and replace it with a tiered system that still captures meaningful revenue from mature fields but actively rewards investment on new drilling. Norway’s own petroleum tax model does exactly this: high headline rates, but structured to make exploration viable rather than punitive. The goal isn’t a lower tax take per barrel, but more barrels over a longer period.

However, this requires reopening the North Sea to allow new licensing rounds and exploration, as well as an admission that prioritising domestic production means trading short-term net zero optics for long-term fiscal resilience, because continuing to import gas from Norway and Qatar while shutting down domestic supply is a contradiction, both economically and environmentally.

Crucially though, any revenues would need to be locked away. A UK version of the Norway model only works if it is genuinely ring-fenced, protected by legislation and insulated from political cycles, something closer to a constitutional lock than an OBR-style advisory body. Unfortunately, governance is where most long-term fiscal vehicles in Britain have historically collapsed. A cross-party board working to design the structure would help insulate it from five-year electoral cycles, but cross-party consensus notwithstanding, pretty much anything fiscally related is its own challenge.

Complementary revenue streams, from offshore wind lease revenues, spectrum licences, or future carbon credits, could also help supplement North Sea receipts and partially address the scale problem. However, the final requirement is the hardest: public expectation-setting. This is, by no means, a quick fix, but a 30–40-year project. No sitting politician will preside over its completion. So, the argument has to be intergenerational; the same argument Norway made in 1990 and has largely kept faith with ever since.

While the economics are challenging, they are workable. The limiting factors are whether the UK is willing to think that far ahead, and change a current political culture that has consistently chosen to make future generations slightly poorer in order to make the present slightly more comfortable.

When finance becomes geopolitical

For much of the post-Cold War period, the global financial system operated under the assumption that it was, if not entirely apolitical, then at least insulated from the harsher realities of geopolitical conflict. Capital flowed across borders with relative ease, reserve assets were treated as sacrosanct, and the infrastructure underpinning global finance, from correspondent banking to payments systems, was seen as broadly neutral.

That assumption is now under sustained pressure. What is emerging is not an economics politics substitutive, but a more complex intersection of both. Geopolitical factors, once peripheral, are increasingly impacting financial decision-making by central banks, sovereign wealth funds, institutional investors and multinational corporations. The implications are huge, not because the system has splintered, but because the perception of it being neutral is fraying. Its evolution of financial sanctions has been the most visible driver of that shift. Historically often symbolic, sanctions have become systemic in scope, capable of isolating entire economies from the global financial architecture.

The shuttering of Russian banks from parts of the SWIFT messaging infrastructure following the invasion of Ukraine and around $300bn of Russian central bank assets immobilised after that, in some cases, was a turning point. These were by no means modest moves; they were tests of the profound ways in which entrenched financial infrastructures can be weaponised as a tool of statecraft. Such actions always have the effect of spreading beyond their intended targets.

Contemporary supply chains, energy markets and cross-border flows of investment are tightly interconnected, meaning sanctions can reverberate through the global economy in non-structural and unpredictable ways. Currency fluctuations, commodity price shocks, and disruptions to trade financing are no longer secondary effects, they are factored into the calculus. This has raised concerns that are felt by legislators and investors, too. Desmond Lachman, a senior fellow at the American Enterprise Institute, said, “the US freezing of Iranian and Russian assets seems to be raising questions as to the reliability of the US as an economic partner.”

The undercurrent here is clear: financial access is no longer all rules-based, it is increasingly conditional upon political alignment. But what is more recent is how sanctions are now anticipated, priced and, in some cases, pre-empted. Banks are incorporating geopolitical risk scenarios into compliance frameworks more and more; asset managers are scrutinising portfolios for sanction exposure; and corporates are also adjusting their supply chains, so they don’t merely deliver efficiency but also are able to weather political disruption. The result is a financial system that is responding to geopolitical shocks before they happen, rather than just dealing with them.

The question of reserves
Nowhere is this more relevant than in the handling of foreign exchange reserves. Reserves stored in major financial centres have been regarded as the ultimate safe asset for many years: liquid, secure and free of political interference. But that assumption has been made murkier by the freezing of Russian sovereign assets. While such steps are not without precedent, their scale and visibility have challenged people to consider what if any geopolitically contested environment is considered ‘safe.’

Banks are incorporating geopolitical risk scenarios into compliance frameworks

Yet the response has been more nuanced than some early remarks implied: “It hasn’t reduced holdings of euro reserves – other factors, notably the yield increase, have mattered more,” says Brad Setser, a senior fellow at the Council on Foreign Relations. That underscores an important point: geopolitical risk is growing but not supplanting long-held financial considerations such as yield and liquidity. Instead, it has been put on top of them. But there are signs of a gradual recalibration.

Central banks are diversifying, especially in emerging markets, not just by currencies, but by jurisdiction and asset type. Gold accumulation has persisted, not as a reaction against the dollar system but as a hedge against potential limits on access to financial assets under political catastrophe.
This has been mirrored, of course, in central banking circles, where policymakers have been putting more value on ‘resilience’ and ‘optionality’ in the management of reserves, suggesting that reserves are now not only judged on factors such as their financial structure but also strategically on the ability through which they can be accessed.

While the idea that the global financial system is fragmenting along geopolitical lines has gained traction in recent years, the structural imbalances that feed global capital flows remain firmly in place. China still runs large current account surpluses that need to be recycled into deficit economies like those in the US and the UK.

These flows, by necessity, cross geopolitical fault lines. Such attempts to create alternative financial architectures through regional payment systems, or through bilateral currency exchanges, have yet to meaningfully displace the dollar-centric system.

Senior market players share this sentiment. Blackrock CEO Larry Fink, in his most recent annual letter, warned not of fragmentation per se, but of a ‘reordering’ of global capital flows, driven by industrial policy, supply chain realignment and national security concerns. The distinction matters. A reordered system may look different at the margins – more regional, more politically conditioned – but it is still deeply interconnected at its core.

Similarly, Christine Lagarde, President of the European Central Bank, has argued that while geopolitical tensions are reshaping trade and investment patterns, they are doing so within an existing framework rather than replacing it. Financial globalisation, in this reading, is evolving, not unwinding. This enduring interdependence places a natural constraint on how far financial decoupling can go. It also explains why, despite political tensions, global capital continues to flow in recognisably familiar patterns.

The changing nature of safe havens
Where geopolitics may be having a more subtle impact is in perceptions of risk, especially around so-called ‘safe haven’ assets. Lachman says that, “US Treasury bonds and the US dollar seem to be losing their safe haven status” amid heightened geopolitical and financial market volatility. Whether justified or not, this perception is of great import.

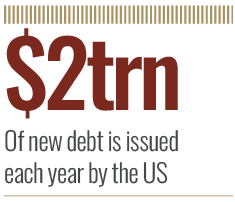
The US depends on foreign demand to fund its fiscal position, needing to issue around $2trn in new debt each year but refinancing a much larger stock of existing obligations. A sustained shift in investor sentiment would, theoretically, create more complexity here. Still, the counterargument remains compelling. The depth, liquidity and institutional credibility of US financial markets have largely helped anchor global portfolios. As Setser observes, “most flows are still driven by considerations of return.” It is the tension between perception and structure that will define the next phase of global finance. Safe havens may be questioned, but they are not easily replaced. Instead, investors will increasingly consider them conditionally safe, sound under most circumstances, yet not entirely immune to political risk.
If we are not dismantling the system, then geopolitics is sure reformulating how capital is allocated. This is most evident in cases like the return of industrial policy in industrialised economies. National security concerns are even further connected to macro-level fiscal programmes. That is influencing private capital flows, as investors align with policy priorities or react to incentives embedded in legislation.

The effect is subtle but significant: capital is no longer flowing solely to where returns are highest, but also to where political support and strategic importance are greatest. Asset managers are also tasked with navigating not just macroeconomic cycles, but also policy regimes that are potentially sensitive to geopolitical developments. Now, longer-term strategies are requiring greater consideration of regulation, political alignment and vulnerability to cross-border tensions.

A more complex calculus
Complexity is the defining feature of the current environment. Financial decisions once guided predominantly by growth differentials, interest rates and inflation expectations must now also account more explicitly for political risk. This is not entirely new. Capital flows have always been guided by influences beyond merely economic fundamentals, including regulatory arrangements, institutional credibility, and geopolitical alliances. What has changed is the salience of these considerations. The problem is especially acute in emerging markets. Many have developed deep reserve buffers in the past 20 years, which have protected them from external shocks. Yet exposure to major financial centres – especially the US – remains a defining feature of the global system.

This can cause unexpected vulnerabilities. Economies heavily invested in US assets may face greater risks from currency movements than from geopolitical fragmentation. The interplay between financial exposure and political alignment is, in other words, highly context-specific. However, smaller, more vulnerable economies have different risks. Limited access to global capital markets, in addition to their exposure to commodity price shocks and currency volatility, makes them especially vulnerable to disruptions caused by geopolitical developments elsewhere.

The financial system is neither collapsing nor being entirely remade by geopolitics. But its character is evolving. The notion of neutrality – the idea that financial infrastructure has an autonomous relation to political power – is beginning to dwindle. Instead, it is a more explicit acknowledgement that access to capital, payments systems, and reserve assets can be governed by strategic considerations. To investors and policymakers these new frameworks do not mean relinquishing the old ones. Yield, liquidity and risk-adjusted return remain central. But they must now be assessed alongside a more explicit evaluation of geopolitical exposure. The world may be entering a period defined less by global integration and more by competing systems of economic, political and financial influence. The result is a world in which financial strategy and political strategy are increasingly intertwined. Navigating it will require not just economic insight, but a sophisticated understanding of how power is exercised through markets. In that sense, the question is no longer whether finance is becoming geopolitical. It is how deeply that reality will be embedded and how adeptly global actors can adapt to it.

A Mayoralty for our age

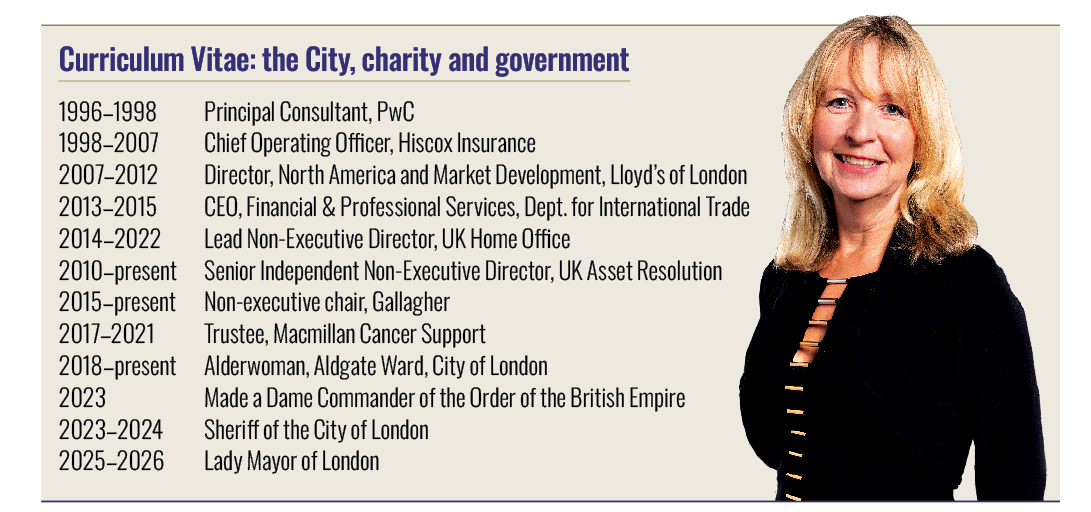
Changing perceptions of an 800-year-old institution steeped in tradition is no easy task, but that is what Dame Susan Langley is on course to achieve in her year as the first citizen of the City of London, usually known as the Lord Mayor. She is the 497th holder of that office since it was established in 1189 and only the third woman to hold the position, but the first to style herself Lady Mayor of London. That decision alone has made a huge impact, as well as raising the eyes of traditionalists, but it shouldn’t have come as a surprise.

When she was elected to the Court of Aldermen in 2018, part of the City’s governance structure, she quickly realised she wasn’t happy with a gender-specific title: “I was the first to take the title Alderwoman. I wasn’t trying to make a point but what triggered it was when someone said ‘Alderman Langley’ everyone shook my husband’s hand. I got fed up with that.

“Changing that was hard. There were papers written about whether it could be done but the nice thing is now that it is done all of the women who come after me have a choice.”

When it came to the Mayoralty, the potential legal obstacles were non-existent because all the relevant legislation just refers to the position as Mayor. Lord Mayor is the title that has been used by convention. This didn’t stop her having to work to justify the adoption of Lady Mayor as her title, but her approach was always gentle persuasion, as she recounts one encounter with someone reluctant to accept the change:

Challenging perceptions
“I get that view that since 1189, it has been the convention, I said, but that is because it has been men. Fine. That was the way it started. I said, well, let’s turn it round. Let’s say since 1189, it has been women, and the title is Lady Mayor, and there has always been Lady Mayor. How would you feel if I addressed you as my Right Honourable, the Lady Mayor? And he said, oh, I see what you mean.”

Now that it is done all of the women who come after me have a choice

From that decision flowed the re-titling of the annual parade through the City of London every November that marks the formal installation of the new Mayor from the Lord Mayor’s Show to the Lady Mayor’s Show. This made the world sit up and take notice as it was broadcast live on BBC and widely covered in the national press in the UK:“It made far more of an impact than I ever imagined. It made people feel they belonged because they could see themselves.”The changes she has pursued go far beyond the change of title.She has christened her year in office as the start of the ‘Modern Mayoralty,’ and plenty is happening to embed that in the way the office operates now and in the future.

A legacy that lasts
Traditionally, Lord Mayors have set a theme for their year in office, many very worthy but rarely enjoying a life beyond that Mayor’s year. Working with the City authorities, Dame Susan has already moved the dial on that front. Unusually, the powers that be have been willing to be clearer on who will succeed Dame Susan, with Timothy Hailes, a lawyer, lined up for 2026–27, and Bronek Masojada, former CEO of Hiscox Insurance, succeeding him.

This change has been backed by the creation of an Advisory Board that will ‘fill in gaps in the Mayor’s skillset’ and ‘ensure all three of us operate within set tramlines to give more consistency and impact.’ It is being chaired by former UK Cabinet Secretary Mark Sedwell, who has a clear brief to deliver continuity. And impact is what Dame Susan is focused on. She wants to get the message across to the wider world that the City of London is a place to do business, as well as ensuring the UK government focuses on policies that help the City thrive. Pushing for speedier delivery of the promised captive insurance regime for the City has been at the top of her agenda.

As with all holders of the office she has joined ministerial visits to China, India and America – to name just a few – and has been able to use her experience as a UK trade envoy to put the City’s case effectively.

Bridging markets
“For centuries, the City has been a place where deals are made and honoured, contracts enforced, disputes resolved. In other words, a place where trust thrives. Despite current headwinds, the UK remains the second most attractive destination for global investment. The City continues not only as a centre for capital, but as a gateway connecting investment to markets around the world.

“Our partnerships are thriving and that is something to celebrate and build upon.” When she recently welcomed the British Foreign Secretary and senior foreign diplomats to Mansion House – where the Mayor lives and works for their year in office – she took the opportunity to reinforce this message.

“This is an age defined by volatility, by insecurity, competition and, at times, fragmentation. But despair is not an option. Because, when the world feels most fragile, that is precisely when togetherness matters most. None of us can navigate this moment alone. Not one nation, not one economy, not one system, the future won’t be built in isolation. It will be built through partnerships grounded in shared values, interest and objectives.

“So, as this storm rages on, the question before us is whether we choose to strengthen these connections or allow them to be swept away. I believe we must strengthen them and the UK – and the City – must play its part.”

For those messages to land, however, she says there needs to be a significant change in perception of what the Lord or Lady Mayor does. For her, the day-to-day reality of the role is very clear: “It is probably 10 percent ceremonial, 20 percent philanthropic and then 70 percent business.”But this is not how the world traditionally sees the role.
 

The Lord/Lady Mayor: history and role

The Lord or Lady Mayor of London is the first citizen of the City of London and heads up the City of London Corporation, which is the local authority for what is known as the Square Mile. Within the City, the Lord Mayor is accorded precedence over everyone except the King. It is one of the world’s oldest continuously elected civic offices. It was instituted in 1189, the first holder being Henry Fitz-Ailwin de Londonestone. The most famous holder of the office was Dick Whittington, who was Mayor three times between 1397 and 1420. It is entirely separate from the directly elected Mayor of London, a political office that covers the much larger area of Greater London and is currently held by Sir Sadiq Khan.

“I stand behind tourist groups outside Mansion House and hear them talking about the Mayoralty and the show and ceremony and I actually want to go: no, that is not it. But I don’t seize their flags from them. The aim, over time, is that when someone stops you in the street and asks what the Mayoralty does they will say they are an ambassador for the financial and professional services sectors and when they say, what does Mansion House do? I want them to say it is the FPS Embassy for the City of London.”

She has changed the signs on her office to say ‘Ambassador for Financial and Professional Services’ and one of the signs that greets visitors as they enter the splendour of Mansion House now says ‘Embassy for Financial and Professional Services.’

Changing signs is easy: changing perceptions is much harder, but the message is getting through. On a recent trip to Texas, Dame Susan asked if they would like her to explain what the Lady Mayor’s role is but her host turned round and said: “That’s OK we know you are the Ambassador for Financial and Professional Services in the City of London.”

While that must have given her a glow of pride, she was less prepared for some of the more general perceptions Americans and others seem to have of London. It started with an American firm saying a senior female colleague was coming to London but wouldn’t be wearing her watch and jewellery because of fear of crime. This she dismissed but realised there is a serious problem with misinformation when a senior American asked her what it was like living in an Islamic capital under Sharia Law. This must have made her despair, but she is too diplomatic to condemn those taken in by far-right conspiratorial misinformation, instead responding with a plea for London businesses and authorities to work together to counter such lies, putting the positive case forward for London.

London calling
She believes in London, having been born and brought up in London’s East End.She remembers watching the Lord Mayor’s Show on her father’s shoulders, never imagining she would one day be leading that historic parade. She says that began to change about 15 years ago when some of the more far-sighted City grandees said to her that they were concerned that too few women were in senior positions in the City of London’s governance structures.

When the world feels most fragile, that is precisely when togetherness matters most

“At the time I thought I didn’t have time to do it and, secondly, I had the wrong perceptions. I thought it was too ceremonial as that is the part that I saw. I didn’t think I could make a difference, and I am the kind of person who likes to make a difference. But as I became closer to the City, I saw the impact it could have and got to know some of the Lord Mayors, some of the business agenda, the philanthropic agenda and saw the impact you could have.”

The tipping point came in 2018 when she was persuaded at the very last minute to stand for a vacant Alderman’s seat. She won and the next few years saw her race through the preliminaries to becoming Mayor, including a year as a Sheriff of the City of London. Few Mayors are remembered for long after they have left office but perhaps like another outsider – Dick Whittington – who famously held this office three times from 1397, Dame Susan will have left a mark on the City that will be her legacy for years to come.

Russia’s other AI war

On June 6, 1972, just over a week after Richard Nixon’s visit to Moscow ended, the film Residence Permit premiered in the Soviet Union. On its surface, it was an ordinary drama. In reality, it was a finely engineered piece of state propaganda – a story about a doctor from Leningrad who chooses to remain in Western Europe in pursuit of freedom and professional success, only to discover that stories about Western prosperity are a myth. His decision to leave the Soviet Union, the film concludes, was the greatest mistake of his life.

To spread that message, Moscow needed an entire machinery: studios, censors, distribution networks, cultural institutions. The infrastructure for propaganda was vast, expensive, and slow. More than 50 years later, Russia’s goals remain largely unchanged. It still seeks to project similar messages both domestically and abroad. What has shifted, however, is the cost, speed and scale of pursuing those ambitions.

Today, the Kremlin can do in minutes what once took months, and it can do it across dozens of languages, on hundreds of platforms, at a scale no Soviet propagandist could have imagined. The reason is artificial intelligence. But not in the way the term is usually understood. When analysts speak of an AI race, they typically mean a contest over who builds the most powerful models, the fastest chips and the most capable systems. By that measure, Russia occupies a complicated position. It faces a significant structural constraint: hardware.

Samuel Bendett, an adviser to the Russia Studies Programme at CNA, a Washington, DC–area think tank, says that Russia has a strong pool of talent – STEM-educated specialists and mathematicians capable of developing advanced software. “But hardware has always been the weakness, and this goes back to the early days of the Cold War,” he adds.

That weakness matters enormously in the modern AI landscape. Cutting-edge machine learning systems depend on specialised chips – graphics processing units (GPUs) and AI accelerators – capable of performing vast numbers of mathematical operations simultaneously.

Currently, Russia cannot produce the advanced chips needed for frontier AI. Western sanctions following the invasion of Ukraine have created even more problems. As a result, Moscow relies on smuggled or Chinese-sourced components for more sophisticated systems. “Russia loves NVIDIA microchips and depends on them for military-related AI applications. The same can be said about hardware such as Raspberry Pi and Orange Pi. That hardware is not produced in Russia or, if its equivalents are actually manufactured domestically, they are already outdated compared to global standards,” Bendett says.

But hardware constraints have done little to curb the Kremlin’s broader ambitions. Instead, it has shifted focus to a different kind of battlefield – one where semiconductor shortages matter far less. In this space, the priority is not building the most advanced systems, but shaping the environment in which they operate: influencing what Western AI models retrieve, controlling what its own citizens see at home and dictating what people beyond the borders believe.

Influence abroad
Sopo Gelava has been researching disinformation for more than a decade and has worked with the Atlantic Council’s Digital Forensic Research Lab since 2020. She says that in recent years, the use of AI in the creation and dissemination of Russian disinformation campaigns has significantly intensified. “Actors who once created such content manually now show much less direct human involvement,” she notes.

Currently, Russia cannot produce the advanced chips needed for frontier AI

Gelava explains that even a single operation, originating, for example, from a Russian website and then spreading across platforms in multiple languages, can show clear signs of AI use throughout the process.

“Either automation is being used, or AI is involved in generating the content. This hasn’t caused a revolutionary shift in disinformation, but it has made it far more scalable. It gives creators much greater capacity to spread content at unprecedented speed and reach very large audiences. Overall, AI enables them to achieve significantly greater impact,” she argues. These campaigns are often most active in countries where Moscow has political interests. They tend to intensify before elections, but they do not stop once voting ends. The narratives continue, adapting to new events and audiences.

In one recent case, the Digital Forensic Research Lab identified a network of TikTok accounts. They appeared to coordinate the spread of AI-generated content targeting Moldova’s ruling Party of Action and Solidarity and President Maia Sandu, while also encouraging people to join protests.

Gelava adds that AI is deployed in multiple ways within these operations. It can automate the synchronised spread of narratives across platforms, or enhance visual content to heighten emotional impact and increase engagement. The objective, however, remains consistent: to reach as many people as possible, as efficiently as possible.

In Moldova’s case, at the time of writing, the analysed TikTok accounts had a combined following of 158,556 users, with total engagement exceeding 26.3 million across all interaction types. AI is making it easier not only to scale disinformation, but also to intensify cyberwarfare. In April, Dutch military intelligence warned that Russia is using AI to accelerate cyberattacks, with the threat expected to grow.

What is changing is not just the speed of these operations, but their structure. AI is shifting cyberattacks from labour-intensive efforts to highly automated processes. This allows multiple targets to be identified and hit simultaneously. Tasks that once required sustained human effort can now be executed in seconds, significantly expanding both the scale and reach of these operations.

Control at home
The same logic behind Russia’s use of AI abroad, based on automation, scale, and efficiency, is increasingly being applied at home. “Internal security has always been at the forefront of Russian high-tech development in general,” Bendett says. “A key priority has been how to insulate the country from external influence and limit its impact on the domestic population.”

AI is now making that approach dramatically more powerful. Where state propaganda once depended on extensive physical infrastructure – studios, printing presses, distribution networks – it can now be managed digitally. This allows the Kremlin to monitor, filter, and shape its information environment with far fewer people and at far greater scale.

In January, Forbes reported that Roskomnadzor – Russia’s federal body for regulating and censoring telecommunications – plans to deploy a machine learning-based system for filtering internet traffic within a year. According to the agency’s digitalisation plan submitted to the government, 2.27bn rubles ($30m) has been allocated to the initiative. According to media reports, the system aims to identify and block prohibited content more efficiently and restrict access to VPN services that Russian citizens use to circumvent censorship.

Bendett believes that what is happening in Russia now, with restrictions on Telegram, broader internet blocking, and limits on VPNs, runs counter to long-term logic. He argues that if most Russians are cut off from international IT applications and global messaging platforms, it will hinder development over time, because Russia’s IT and high-tech sector is small.

“Russia’s government policies, which are currently aimed at limiting the population’s access to some of these international components, are probably shooting themselves in the foot,” Bendett says. “This is delaying many projects and developments that would have unfolded if Russian developers and users had access to Western applications, databases and algorithms.”

The surveillance architecture extends into physical space as well. Across Russian cities, street cameras embedded with AI-powered recognition systems are being used to monitor public spaces and identify individuals in real time. In Yekaterinburg alone, around 1,000 additional cameras are expected to be installed by the end of June, covering streets and public areas. The systems analyse video feeds continuously, significantly expanding the state’s capacity to monitor its population without requiring a proportional expansion of human personnel.

Steering what AI systems learn
Russia’s operations, both abroad and domestically, are largely visible, if difficult to counter. But there is another dimension that is far harder to detect. Recent studies suggest that one of Russia’s most consequential AI strategies is aimed not directly at populations, but at the models they increasingly rely on to interpret and understand the world. This strategy targets Western AI models indirectly by shaping the data they are trained on and the sources they retrieve information from.

A network of pro-Kremlin websites has reportedly used AI tools to flood the internet with millions of pieces of Russian propaganda. Much of this content is designed to be picked up by search engines and scraped into large datasets used to train AI systems. Researchers describe this approach as a form of ‘data poisoning by scale,’ where the aim is not a single piece of misinformation, but a sustained saturation of the information ecosystem. The concern is that, over time, this could subtly shape how AI systems interpret, prioritise and reproduce information.

Sopo Gelava notes that Russia’s AI-driven tactics are becoming more sophisticated over time. AI-generated content used in disinformation campaigns was once relatively easy to spot. But that is changing quickly. “There used to be frequent grammatical errors, and in the past we could often tell from this that the operation had been created by AI. Today, however, it gives more opportunities to creators of disinformation because the translation is much more refined and significantly better adapted to the local context,” Gelava says.

Researchers studying Russia’s use of AI believe its parallel efforts in the global AI race are becoming harder to detect, more scalable and more targeted. They not only reach wider audiences but also risk shaping how information is interpreted and reproduced across digital systems.

2026: The year of the rollback

When corporations announce policies, all stakeholders – from consumers to employees to shareholders – expect them to be upheld. But a dramatic reversal is taking place. If 2020 was the time for grand social and environmental pledges, 2026 is the year of the rollback. Target, Walmart, Meta, Amazon, McDonald’s, Warner Bros and Goldman Sachs are among the one in eight companies that have so far weakened diversity, equity and inclusion (DEI) policies. Meanwhile almost one in five (18 percent) completely or partially discarded their net-zero promises.

The policy U-turns first emerged when Trump re-entered the White House and started revoking guidelines himself. By 2025, the fires were roaring. In a striking moment, the Net-Zero Banking Alliance collapsed after Bank of America, JPMorgan Chase, Citigroup, Wells Fargo, Morgan Stanley and Goldman Sachs all withdrew. Today, politically motivated corporate rollbacks continue to compound at pace. The sudden drop in commitment reflects the aggressive ‘anti-woke’ philosophy of the Trump administration. For investors, it opens a Pandora’s box of new risks.

Boycotts spiral into falling valuations
One of the companies that has become synonymous with rollbacks, capitulating to Trump and the MAGA movement, is mega-retailer, Target. In November 2024, the brand bowed to pressure to remove Pride merchandising, leading to boycotts and a 20 percent drop in share prices. Just a few months later, Target went on to U-turn on its DEI initiatives, notably to end its Racial Equity Action and Change (REACH) strategy and abandon a $2bn pledge to support Black businesses.

This sparked one of the most devastating boycotts in US corporate history, with footfall dropping by nine percent and share prices losing 33 percent of value year-on-year. CEO Brian Cornell was forced to step down and shareholders have filed class-action lawsuits. Target is alleged in the courts to have engaged in the “misuse of investor funds to serve political and social goals.”

With boycott risk comes increased litigation risk. A survey by Norton Rose found twice as many companies were impacted by ESG-related (environmental social governance) class actions in 2025 (30 percent) compared to 2024 (16 percent). Political pressure is listed as a top trend contributing to the increased risk exposure. For shareholders, it is worrying. Companies with revenues exceeding $1bn spend an average of $4.3m on litigation, which eats into profitability.

What makes Target especially vulnerable to boycott risk is that the store had a significant African American customer base. By bowing to politics, it alienated its own customers. As one shopper commented, “We don’t buy where we are not respected.” Worryingly for Target, the brand continues to attract protests, even with a new CEO. The retailer is now at the centre of another boycott around its dealings with ICE.

It is unlikely Target’s share price will recover to the highs of 2020, which are currently less than half the value. In the words of Head of Behavioural Finance at Oxford Risk, Dr Greg Davies, “Investors do not only price cash flow,” he explains, “they also price trust.”

Shareholder revolt increases
More recently, oil giant BP felt the full force of rollback risks when it tried to reverse on its clean energy commitments in April 2026. For the newly minted CEO Meg O’Neill, the triple shareholder revolt was a disaster. More than one in two (53 percent) voted against unwinding climate disclosures. To rub salt in the wound, a shareholder resolution was filed to increase disclosure for oil and gas capital investments. Furthermore, in a strong show of disapproval, one in two (53 percent) voted against virtual-only AGMs, hinting at a growing mistrust. Cognitive Scientist Elin Helander points out how rollbacks “erode trust” for shareholders, and “particularly people who see sustainability as an important part of investing.” Alienating sustainable investors presents concentration risks in the future, as well as limiting the potential shareholder market and liquidity.

However, it’s not only sustainable investors who struggle to find confidence in leaders who U-turn. The process of launching an expensive initiative only to abandon it is uncomfortable for all investors to stomach. By contrast, companies such as Apple, Levi’s and Ikea that continue honouring their pledges benefit from improved trust over time. IKEA, for example, has enjoyed a boost in value over the past years, as it holds steadfast to its ongoing environmental strategy.

Ripples of risks
Not all U-turns are built the same. Davies highlights how investors distinguish “learning from flinching.” A flexible approach to new technologies and opportunities is welcome. For example, when CEO of Blackrock Larry Fink changed his stance on crypto, the markets broadly approved.

Transactional behaviour is closer to gangsterism than capitalism

However, since the Trump presidency, Blackrock has openly shredded many of its once-trailblazing environmental policies. Fink recently commented that the ESG and DEI “pendulum” swung “too far.” By contrast with the crypto U-turn, this created ripples of alarm and decreased confidence in Blackrock’s decision making. Two Dutch pension funds divested a combined €17bn from Blackrock in direct response to the rollback, with rumours swirling that more could follow. As institutional investors like pension funds are so large, market valuations can quickly slip when they start to pull funding. It is yet another risk for investors to price in.

Perhaps the most famous example of a leader who went from enlightened to erratic in the eyes of investors is Elon Musk. Musk rose to prominence as a figurehead for the clean energy transition and free speech. However, his willingness to bend values based on politics has ruptured the trust of his original supporters. Musk’s sharing of politically motivated disinformation on X (formerly Twitter) has been especially problematic.

Most investors are “unwilling to engage with leaders who have no respect for verification, checks and balances,” elaborates Regulatory Design Specialist, Dr Roger Miles. This in turn adds concentration risk, where the only stakeholders left are those who agree with Musk, creating groupthink and “contamination risk” if they are all accessing their information from the same dubious sources.

Markets and mafia techniques
Worryingly, 2026 feels like a year where the normal “verification, checks and balances” are pushed aside in favour of populist politics – even in the investment markets. When listed companies abandon policies because they want to appease a President, the market stops becoming reassuringly rules-based and starts to become mafia-style.

“Lets call it what it is, it is expediency,” elaborates Dr Miles. “I threaten you, you give me what I want.” Today’s commodification of values means that policies are bought, sold and amended like products, without meaning anything. As Dr Miles emphasises, “Transactional behaviour is closer to gangsterism than capitalism.” It is particularly pronounced in the cases of social media providers like Meta, where whistle-blowers allege that algorithms are skewed to promote content that the Trump administration aligns with, at the cost of values and ethics. Piecing together each little rollback creates a prickling feeling of discomfort among investors.

Earlier this year, the ‘Sell America’ trend took off. Investors have already started to mobilise against what they see as unacceptable corporate behaviour. In a sense, it is a wider response to the overall rollback of traditional Western values. “People are deeply pissed off about the loss of the social contract,” adds Dr Miles candidly. In this age of AI and climate uncertainty, consumers are anxious about the direction of their futures, and have even less tolerance for companies that appear to sell them out. However, we are also caught in a moment of misinformation, unsure of which sources to trust, adding yet more anxiety to the mix.

It has left the markets in what Dr Miles refers to as a “Wile E. Coyote moment,” or “hysteresis” to use the behavioural economics term. Characteristically, the cartoon runs off the edge of a cliff and continues to run in mid-air for a while. It is only when he looks down and acknowledges the mistake that he falls. This is what Dr Miles believes could be happening now. “These are strongly fragile conditions,” he explains. For a short period, the market is continuing to act as if nothing has changed and everything is fine. But as the realisation that we are moving from rules to mafia-techniques hit without checks and balances, the crash could be colossal.

From rollbacks to a roll of the dice
For investors, it is a tense time. Without a strong financial backhander, corporations may continue to U-turn for politics, against the shareholder interests.

This can cause sharp Target-style devaluations alongside irreparable confidence risks. On the other hand, the more insidious alternative would be that companies get away with their rollbacks, potentially contributing to a mass-selling of US assets and eventual market crash. After all, 41 percent of US investment is held abroad, where many Trumpian policies are deeply unpopular. Perhaps the best way to mitigate against rollback risks starts and ends with shareholders themselves.

Recently, as with BP, Mastercard was left red faced as shareholders overwhelmingly voted against DEI rollbacks. Preventing rollback risks means overcoming inertia and taking active supervisory roles in shareholder meetings. Could shareholders be the unlikely heroes, able to close this Pandora’s box?

The Fed’s struggle for independence

When Donald Trump turned his fire on Jerome Powell last year, it barely registered as unusual. The President had criticised the Federal Reserve chair before. This time, however, the threat felt sharper. “If I want him out, he’ll be out of there real fast,” he said – sounding less like a head of state than the host of The Apprentice, casually dismissing a contestant.

At first, it seemed like another off-the-cuff remark. But what followed was something more sustained: a steady, public campaign against the Fed chair. Trump repeatedly attacked Powell for refusing to cut interest rates, even calling him a “moron,” despite having appointed him. The message was blunt. Monetary policy should align with political priorities. Relief, the US President suggested, would come soon enough: rates would fall “when Kevin gets in.”

We need to talk about Kevin
Kevin Warsh, now installed as Fed chair, arrives with the kind of CV that reassures markets. A former governor who served from 2006 to 2011, he is widely seen as a seasoned operator in financial circles. He is also the wealthiest Fed chair in history, with assets worth at least $130m, accumulated through his role at the Duquesne family office. His confirmation, however, was anything but routine. Senators pressed him hard over more than $100m in ‘undisclosed’ assets, turning hearings into a confrontation. Republican senator Thom Tillis lent his support only after the Department of Justice dropped a criminal probe into Powell, widely perceived as a strategy to nudge Powell to step down. For his part, Powell has pledged to stay on the Fed board as governor to provide continuity, even though he had previously considered stepping down.

Warsh’s proximity to the administration has become a focal point. Critics worry that his alignment with Trump could blur the line between political power and monetary policy. In the run-up to his appointment, he softened his hawkish stance on inflation, a shift some see as calculated. His ties run deep: his father-in-law, Ronald Lauder, is a long-time Trump ally and donor. Supporters counter that Fed chairs may be political appointees, but their professionalism prevails once in office. Warsh has sought to calm fears during his Senate hearing, dismissing speculation that he would overhaul regional Fed leadership with loyalists. And his term runs until 2030, long enough to outlast the current administration.

The Fed’s structure itself offers some protection. Policy is shaped collectively by the Federal Open Market Committee (FOMC). Decisions – especially the most consequential ones on interest rates – require consensus or at least a majority. As chair, Warsh still casts only one vote and will have to convince other committee members. Historically, governors have been cautious about open dissent, preferring to project unity. But if they perceive an encroachment on independence, they may assert themselves forcefully through votes or even public statements.

Yet leadership still matters. The chair sets the tone, shapes communication and influences the internal culture. A chair perceived as politically aligned could shift expectations about how decisions on monetary policy are made. Over time, that perception can become self-reinforcing, affecting everything from bond yields to currency valuations. “Once he is sitting in the Chair’s seat he will be beholden to his fellow FOMC participants and markets, who will be closely watching for signs about his vigilance in keeping inflation expectations well-anchored,” says Christopher Hodge, chief economist of the US at the investment bank Natixis CIB Americas, who formerly held senior roles at the Federal Reserve Bank of New York and the US Treasury.

Under pressure
For much of its history, the Fed has occupied a delicate space – created by politicians, yet expected to stand apart from them. Its independence has never been absolute. Congress created the institution, and elected politicians have always sought to influence it, particularly before elections. Yet over time, a norm has emerged: while politicians might criticise its decisions, they ultimately respect the Fed’s autonomy. Its institutional gravitas rests on the premise that monetary policy is insulated from day-to-day politics, a tradition based less on formal rules than on shared norms. Once that mutual restraint between governors and politicians erodes, rebuilding it can be difficult.

Warsh is widely seen as a seasoned operator in financial circles

That understanding is beginning to fray. Trump’s attempts to reshape the Fed – its leadership and direction – have raised concerns that go beyond personalities. Last August, he sought to ‘fire’ governor Lisa Cook, defying legal protections that shield board members from dismissal. The move failed, but the signal was clear. If politicians can dictate the board’s composition, the boundary between fiscal and monetary authority begins to blur. At the same time, the administration has moved to exert more formal control. An Executive Order signed by Trump asserted that “officials who wield vast executive power must be supervised and controlled by the people’s elected President,” requiring independent agencies to submit regulatory proposals for White House review. The Fed’s monetary policy was spared. Much else was not.

To some historians, the shift in public rhetoric is without precedent. “Trump’s assault on both Jay Powell and Fed independence is the strongest such assault in the Fed’s 112-year history,” says Richard Sylla, an expert on the history of US financial institutions who teaches at the NYU Stern School of Business. The closest parallel, he argues, dates back to the post-war clash between the Treasury and the Fed over the latter’s interest rate policy, aimed at reducing inflation, which ultimately led to an accord restoring its monetary independence. Ironically, current pressure may strengthen the institution, Sylla argues. “Trump’s pressure on Powell, and Powell’s successful resistance to that pressure will actually result in increasing the Fed’s reputation for policy independence and strengthening the overall case for central-bank independence.”

Regime change
Warsh has made it clear that he does not intend to preserve the status quo. He has described US monetary policy as “broken for quite a long time” and has promised a “policy regime change.” Part of that shift will be philosophical. Unlike Powell, Warsh favours a narrower interpretation of the Fed’s mandate. He has signalled a retreat from policies that blur the line between monetary and fiscal intervention, particularly large-scale purchases of mortgage-backed securities. Under his watch, monetary policy is expected to be depoliticised, steering clear of non-monetary issues like climate change and social justice.

Above all, Warsh has his sights set on the Fed’s ballooning $7trn balance sheet. Immediately scaling it back would mark a decisive break from recent policy, reversing the Fed’s decision to halt quantitative tightening, under which its bond holdings were allowed to mature. Higher Treasury yields might force Fed interest rate policy into difficult trade-offs between supporting growth and containing inflation. And those trade-offs will not occur in a vacuum, given Donald Trump’s obsession with lower interest rates. “With what appears to be a persistent energy shock, there will be inflation and reason to raise interest rates,” says Barry Eichengreen, an economic historian at the University of California, Berkeley (the full interview with Professor Eichengreen is on pages 98–99 in this issue of World Finance). “But there will be political pressure from the White House to reduce interest rates. That will not be an easy circle to square.”

Calls for the Fed to keep interest rates low are not unprecedented. But the phenomenon is gradually evolving into a systemic feature of US politics due to the country’s precarious fiscal position. Higher debt levels increase pressure on the Fed to keep rates low and buy Treasurys, helping to erode the real value of US debt. The risks are obvious if recent economic history is a guideline. In the 1970s, government influence pushed the central bank to hold rates down, fuelling a surge in inflation. It took the shock therapy of aggressive rate hikes under Paul Volcker’s Fed leadership – and a deep recession – to restore confidence. Even then, it took years to fully re-anchor expectations. “That could happen again, undermining Fed independence, the value of the US dollar and confidence in US public debt management,” Sylla warns, pointing to the risks of sustained political interference that could undermine the Fed’s effort to anchor inflation expectations. “If political interference pushes inflation to sustained levels above two percent, the Fed would lose credibility. No matter what it does, it is likely to become a scapegoat for the likely negative results of fiscal irresponsibility.”

The Fed’s global reach under strain
What happens at the Fed rarely stays in Washington. As the anchor of the global financial system, the Fed’s credibility extends far beyond US borders. Its decisions shape capital flows, currency stability and the availability of dollar funding worldwide. For many countries, access to dollars is a cornerstone of financial stability. Foreign central banks are more comfortable with banks and firms under their jurisdiction using dollars if they can access them from the Fed through currency swaps in times of need, says Eichengreen. “If we have a nationalistic US President who insists on nationalistic behaviour by the central bank, things will be different.”

Warsh has made it clear that he does not intend to preserve the status quo

There are already signs of that shift in thinking. Stephen Moran, a temporary Trump appointee to the Fed board, has argued that the US should reconsider its role as a global lender of last resort, or demand compensation for it. Similar criticisms have surfaced before, including during congressional hearings after the 2008 financial crisis. A more inward-looking Fed aligned more closely with short-term domestic political objectives would reshape global finance, increasing global scepticism about its credibility.

“If financial markets and international partners perceive undue political interference in the central bank, we will see the ‘ABUSA’ – ‘Anywhere But The US’ – sentiment soar, and to the detriment of the US economy,” says Yerbol Orynbayev, a former World Bank governor and ex-deputy Prime Minister of Kazakhstan who played a key role in the country’s response to the 2008 financial crisis. “The US Treasury market is already on the verge of rioting – yields are fickle and are often rising. If the Fed is compromised, the US economy could face huge losses.”