EBC director: How the future of trade may be less efficient but more resilient

After discussing the recent movements in the oil markets and their ramifications in the broader economy, EBC Financial Group’s Christopher Stiegeler suggests that the ongoing and increasing geopolitical uncertainty may be causing a fundamental transformation in globalisation – and that the global economy may become less efficient, but more resilient.

World Finance: Christopher Stiegeler from brokerage EBC Financial Group is with me in the studio, and we’re talking about the geopolitical uncertainty that is right now best exemplified by the US and Iran, but before that it was Israel, tariffs, Ukraine… and, Chris, you think that this might represent a fundamental shift in the global economy.

Christopher Stiegeler: Potentially. I mean, for years, sort of, globalisation in its most basic form, means moving goods that are cheap in one part of the world, and moving them several thousand miles to another part of the world, and selling them more expensive. It’s the classic arbitrage, right?

We’re now looking at that not necessarily being the most commercially viable option, and now a supplier, when they’re looking at where to source goods from, they will start having to think about factoring in larger inventories, increased insurance costs, and those costs are ultimately going to get factored into the final price, which is again going to feed through to consumers.

So I think in terms of the global economy, what we could be potentially seeing is a global economy that becomes fundamentally less efficient, but potentially more resilient.

World Finance: Are we seeing companies respond in this, longer-term, systemic way yet? Accepting that this might be a real paradigm shift? Or does it seem like people are hoping that the next status quo is the same as the old status quo, just with a little less shipping traffic in the Middle East?

Christopher Stiegeler: I think the markets are actually already giving us evidence of that, Paul.

When we see – as we are seeing, and continue to see in the Middle East – a major shipping route come under threat. That’s almost immediately reflected in the markets in the form of currency volatility, increased insurance costs, increased freight costs and so on. So I think the market and suppliers are already pricing in that geopolitical risk in what they’re doing.

And I think that’s important. Because for a long time, the received wisdom on all of this was that geopolitical events were treated as sort of a temporary shock, and something that would sort of pass, and then we’d all get back to normal. But I’m not sure that we’re still in that space anymore.

Companies are increasingly having to ask themselves: ‘Do I want the cheapest supplier per se, or do I want a supplier or a route that I know I can rely on if something goes wrong?’ And I think that’s a really sort of fundamental way that companies and the economy is changing the way they think about efficiency, and indeed how they price it.

Watch more from this interview with Chris Stiegeler:
Iran, oil, and the world economy: are we seeing history repeat itself?
Could the oil shock bring back inflation? EBC director on trading peace vs disruption
Safe haven gold: what are investors and central banks seeking protection from?

Safe haven gold: what are investors and central banks seeking protection from?

In the face of market turmoil – such as what we’re seeing as a consequence of Trump’s war on Iran – gold is often spoken about and used as a safe haven. Christopher Stiegeler, Director of EBC Financial Group, asks: what are investors seeking protection from? He explores the various reasons why investors – and central banks – may choose gold over any other asset, and suggests what gold traders should be asking themselves about its future.

World Finance: Chris, moving on from black gold and the source of all of this market turmoil, let’s look at actual gold – traditionally the hedge against this kind of disruption.

Christopher Stiegeler: Exactly. Gold’s often sort of mentioned, or used, as a safe haven, but the question is: what are investors seeking protection from?

And there’s several reasons that investors buy gold. One would be as a, if you like, a geopolitical hedge against geopolitical uncertainty. Another could be concern about the state of a particular government’s finances, or indeed a government. Another reason would simply be because it’s the most attractive among a basket of asset classes, none of which are particularly attractive at the moment.

Another question that’s important to mention here is that when EBC’s gold trading clients – and indeed, the gold market is rallying, and they’re buying aggressively – it’s not necessarily giving us the message that they think the economy’s collapsing, or anything like that. Gold investors might simply be saying that I want an asset, or I want to trade in an asset, that doesn’t depend on one currency, one company, or indeed one country.

World Finance: They may also be saying, well, central banks are consistently buying gold, so there’s essentially a buyer at whatever price it gets to.

Christopher Stiegeler: Yeah, I mean we’ve seen in the last quarter, the World Bank reported that central banks had bought about 290 tonnes of gold in the last quarter, something like that. And close to 50 percent of central banks surveyed said that they continued to be adding to their gold stocks over the coming year.

But even with that continued holding of gold as an asset by central banks, that’s not the central banks necessarily saying that they believe that the market’s going to go higher. A lot of this is about diversification.

World Finance: So in the context of this Iran-specific peak in gold, what should traders be asking themselves?

Christopher Stiegeler: I think what traders should be asking themselves, is, is what we’re seeing now a temporary reaction to the conflict in Iran, or is it part of a much larger change in the way that investors and traders are looking at risk?

If geopolitical tensions remain high, and we see associated increases in interest rates and so on, then gold could remain attractive.

If, on the other hand, things start to, let’s say, de-escalate, and we see a reduction in the price of crude, we start to look at lower interest rates – then gold becomes less attractive as an asset class, because it doesn’t pay interest.

It’s a trade between fear and opportunity cost, that’s the trade.

Watch more from this interview with Chris Stiegeler:
Iran, oil, and the world economy: are we seeing history repeat itself?
Could the oil shock bring back inflation? EBC director on trading peace vs disruption
EBC director: How the future of trade may be less efficient but more resilient

Could the oil shock bring back inflation? EBC director on trading peace vs disruption

Following on from our conversation with EBC’s Christopher Stiegeler about the war on Iran and its impact on the oil market, we zoom out to look at the ripple effects throughout the economy; what it means for inflation, consumer spending, and interest rates; and the importance of trading with a well-regulated broker when faced with such volatility.

World Finance: Chris, we’ve been talking about Iran and the impact on the oil market, but a crisis in oil has shockwaves throughout the economy.

Christopher Stiegeler: Exactly so Paul, I mean – the question is not simply what happens if oil becomes more expensive; it’s what expensive oil does to everything else.

As we know, I mean, oil is effectively an input into every modern economy. So if our oil prices rise, we see that in transportation costs, we see that on the supermarket shelves, we see that ultimately with inflation.

And that’s a big question that sort of, central banks are having to grapple with at the moment.

If the oil price stays higher for longer, central banks have to make a decision on whether to keep interest rates higher for longer, and wear, if you will, the associated inflationary spectre that’s going to come with that. Or if they accept that this is a temporary shock. And that’s a question we’ll just have to wait and see about.

World Finance: But as you were saying, the shock from oil isn’t just down to the supply drop, but traders’ reaction to that, and their fears or maybe hopes about the future.

Christopher Stiegeler: Yeah no, exactly that. At the end of last month, brent was trading around about sort of $90 a barrel, because there were hints at that time of possibilities of some de-escalation and so forth.

We now know that that optimism was seemingly unfounded, and we’re seeing brent currently trading north of $100 a barrel. So what’s happening here is that traders are effectively – they’re trading expectations of peace, versus expectations of disruption.

And that’s really interesting, because what it means is that, if this disruption continues, and the price of oil remains elevated for long enough, we’re looking at issues of inflation, consumer spending, interest rates, and economic shock. And that’s what the market’s grappling with today.

World Finance: In the context of such market-wide volatility, I suppose it’s more important than ever that traders are partnering with a broker that is trustworthy and well-regulated.

Christopher Stiegeler: Yeah, absolutely. In EBC’s case, the reason that clients choose to trade and execute through EBC in London, and use London as an execution venue, is our access to deep liquidity in London, almost institutional grade pricing, and a mature, developed regulatory umbrella, where our clients can trade in an environment that they’re comfortable and confident with.

Watch more from this interview with Chris Stiegeler:
Iran, oil, and the world economy: are we seeing history repeat itself?
Safe haven gold: what are investors and central banks seeking protection from?
EBC director: How the future of trade may be less efficient but more resilient

Iran, oil, and the world economy: are we seeing history repeat itself?

The International Energy Agency says that Trump’s Iran war has created the “largest supply disruption in the history of the global oil market.” But that history is full of these sorts of crises; so what lessons, if any, can we learn? Christopher Stiegeler from award-winning brokerage EBC Financial Group discusses the parallels between today and the 1978-79 Iranian Revolution, and how fear became as strong a market force as the drop in oil supply.

World Finance: Let’s start with the impact that this disruption has had on the markets, and what historical parallels you can draw.

Christopher Stiegeler: Well that’s an interesting question. I mean, current estimates suggest that around 10m barrels a day are being lost – and that compares with about 20m barrels a day that we were looking at pre-conflict levels.

And that’s why Iran matters so much in financial markets. It’s not just the barrels that Iran produces – or in this case, is struggling to get out to the markets. It’s the geographical situation of Iran and the Strait of Hormuz, which is now again front and centre stage of the oil market, and its position as one of shipping’s major global chokepoints.

And that creates a really sort of interesting historical parallel, actually. In the 1978-79 Iranian revolution, strikes and political instability caused barrels to disappear, if you want to say that. But it wasn’t just the barrels that disappeared that was the issue. It was that fear itself became an economic force. And that’s sort of, very interesting and relevant for traders today, with the oil market.

World Finance: Well, tell me more – how can traders learn from that historical parallel?

Christopher Stiegeler: So, for EBC’s clients that trade oil, they’re not necessarily just asking themselves the question of, ‘How much oil is out there today?’ They’re asking what supply’s going to look like next week, or next month, or the month after that. And that’s really interesting, because it’s sort of where geopolitics merges and morphs into economics.

If crude oil stays expensive, we’re going to pay more in petrol and diesel prices; manufacturing costs are going to increase; airlines are going to pay more for their jet fuel, as we know. And eventually, unfortunately, that will feed through to the end consumer in the form of higher prices.

So I think the question that oil traders should be asking themselves today, is: is this a temporary geopolitical risk premium? Or is this more of a cultural shock that we’re looking at, that would have parallels with the late 1970s?

And I think that’s the key question, probably, that EBC’s oil trading clients, and the wider market, is grappling with today.

Watch more from this interview with Chris Stiegeler:
Could the oil shock bring back inflation? EBC director on trading peace vs disruption
Safe haven gold: what are investors and central banks seeking protection from?
EBC director: How the future of trade may be less efficient but more resilient

Innovation built to scale: Luigi Marciano on the future of financial services

The financial services industry has entered a new phase of technological change. Artificial intelligence is moving rapidly from experimentation towards implementation, expectations are becoming more sophisticated, and consolidation is reshaping the operating landscape. Yet the central question for financial institutions is no longer whether they should innovate. It is whether they can turn innovation into sustainable, scalable business value.

For Luigi Marciano, Founder and Group CEO of Objectway and recipient of the European CEO Award for CEO of the Year in Wealth Technology, this distinction is critical. Having spent more than three decades building Objectway as a WealthTech partner for the financial services industry, he has seen successive waves of transformation change what institutions expect from their technology partners. The latest, driven by AI, may be one of the most significant yet, but only if firms approach it as part of a broader transformation.

“AI should not be treated as a standalone technology,” Marciano argues. “Its greatest potential lies in acting as an amplification layer on top of a trusted operational foundation: validated data, secure and orchestrated processes and governed workflows. In an industry where decisions are closely tied to trust, regulation and long-term client relationships, this foundation is particularly important.”The challenge is therefore less about simply introducing AI than creating the conditions in which innovation can scale.

For years, financial institutions have had to bridge ambition with execution: building for the future while continuing to perform today. That tension surely remains, but the stakes have changed. Innovation that cannot scale leaves potential stranded; performance that cannot evolve eventually reaches its limits. Scalability has become as important as the innovation itself: the ability to make new capabilities work consistently across the organisation and turn them into lasting value.

That means addressing a problem that has been building beneath the surface of digital transformation for years: operational complexity. The convergence of fragmented systems, manual processes, regulatory demands and increasingly personalised client expectations makes profitable growth harder rather than easier. Technology that simply adds another layer of functionality risks amplifying that complexity. Technology that standardises, connects and simplifies it can do the opposite.

This is where the next competitive distinction is likely to emerge, among those that have tackled the harder, less visible foundational work first, leveraging operating models capable of combining automation and efficiency with the flexibility to adapt as markets, regulations and client expectations evolve. Strong data foundations, modular architectures and embedded governance are becoming less of a technology choice and more of a prerequisite for sustainable growth.

This is reshaping the role of technology partnerships. Financial institutions increasingly have to distinguish between capabilities that truly differentiate their business and those that can be delivered more effectively through specialised partners. The emerging model is not about outsourcing innovation, but about externalising complexity while preserving differentiation: using as-a-service capabilities where scale and continuous evolution are difficult to achieve internally, while keeping focus on the areas that create distinctive value.

“The strategy is in the sequence”, highlights Marciano, “Foundations first. Externalisation as accelerator. AI as amplifier. Firms do not all need to start from the same place, but they do need clarity about what enables their desired outcomes: knowing what has to happen before the next layer of innovation can deliver value at scale.”

For Marciano, that sequence is ultimately part of a much longer lesson about building a business in an industry defined by change. A vision may provide the direction, but scalable growth depends on the ability to keep evolving the path towards it, without losing sight of the foundations that make growth possible. The strongest institutions will not be those that simply move fastest towards the next technology, but those that build the resilience, adaptability and partnerships needed to turn each new wave of change into lasting progress.

That is Innovation Built to Scale.

A defining moment for Central Asia

The recent IPO of Uzbekistan’s National Investment Fund (UzNIF) marks a turning point for Central Asia. With $2.4bn in assets and a valuation of $1.95bn – implying a discount of roughly 20 percent – the offering is intended to do more than raise capital. Uzbekistan wants to establish its credibility as an investment destination. But the IPO also represents a regional milestone. For the first time, a Central Asian country is offering international investors a diversified basket of strategic assets through a London Stock Exchange listing overseen by a major global asset manager. At its core, the UzNIF IPO will test whether international investors are willing to view Central Asia not just as a risky frontier market, but as a region with real growth potential and reliable governance frameworks.

The IPO’s structure reflects a sophisticated understanding of investor concerns. The valuation discount compensates for perceived country risk, and the choice to place the fund under the management of Franklin Templeton alleviates fears of political interference and lack of transparency. Meanwhile, an initial $300m commitment from anchor investors, including BlackRock and Franklin Resources, provides a stable base for secondary-market activity. Taken together, these measures directly address many of the longstanding barriers to investment in Central Asia. Yet the significance of this IPO extends well beyond the mechanics of the deal itself. The interest it generated highlights Central Asia’s transformation over the past three decades. What was once a peripheral region has become one of the world’s most remarkable emerging-market growth stories.

Architects of growth
The numbers speak for themselves: over the past 25 years, Central Asian economies have grown at an average annual rate of 4.8 percent, far outpacing the global average of roughly 3.4 percent. Over the same period, the region’s economy has roughly tripled in real terms. The past five years have underscored the region’s resilience. Despite the Covid-19 pandemic, supply-chain disruptions, and escalating geopolitical tensions, Central Asian economies have continued to deliver solid growth. Uzbekistan, for example, has maintained annual growth rates above five percent, supported by strong domestic demand and structural reforms, including gradual liberalisation. Kazakhstan, though more exposed to commodity-price fluctuations, has relied on its resource wealth and institutional reforms to maintain macroeconomic stability. Kyrgyzstan and Tajikistan, for their part, have benefited from remittance inflows, infrastructure investment, and greater regional integration.

Geography is another major advantage. Long viewed as a constraint, Central Asia’s location is increasingly viewed as a strategic asset. As geopolitical instability and conflicts such as the Iran war force governments and businesses to seek alternatives to traditional maritime chokepoints, the region is emerging as a critical overland corridor connecting East and West. The so-called ‘Middle Corridor,’ which links China to Europe through Central Asia and the Caucasus, is rapidly becoming a major commercial artery, accelerating investment in rail, road, and port infrastructure. Against this backdrop, Uzbekistan’s integration into global capital markets is a defining moment for the region. The UzNIF IPO is not an isolated deal, but an early step toward building a regional equity-market ecosystem.

By consolidating minority stakes in 13 state-owned enterprises across sectors such as transport, energy, telecommunications, utilities, and banking, the fund gives investors an opportunity to invest in the Uzbek economy through a single market vehicle. More importantly, it introduces a market-based valuation benchmark – something the region has historically lacked. Over time, this could generate positive spillover effects, reducing the informational asymmetries that have long limited inflows of foreign investment.

Emergence accelerated
The financial implications could be significant. If successful, the UzNIF model could pave the way for a wave of IPOs by individual companies, both in Uzbekistan and across Central Asia. It may also accelerate the emergence of hybrid financing structures that combine public assets, private capital, and international management expertise to fund large-scale infrastructure and energy projects. In a region where limited access to financing has prevented strategically important investments, such mechanisms could unlock opportunities that have remained out of reach for decades. For example, capital mobilised through vehicles like UzNIF could be directed toward large-scale, cross-border projects such as Kyrgyzstan’s Kambarata-1 Hydropower Project or the Rogun Dam in Tajikistan. Crucially, the credibility of the UzNIF project rests on governance. By entrusting the fund’s management to Franklin Templeton, Uzbekistan has effectively signalled its willingness to subject state assets to international standards of transparency, accountability, and fiduciary discipline.

This also highlights a major risk. The IPO’s success will not be judged solely by initial demand or short-term price performance. Investors will watch closely for any indication of political interference, policy inconsistency, or erosion of minority shareholder protections. In that sense, UzNIF’s IPO is as much a political test as it is a financial one. What is at stake is not simply the success of a single fund, but the potential repositioning of an entire region.

If the IPO succeeds, it could help establish a new narrative in which Central Asia is defined less by risk and more by economic opportunity and financial returns. The question now is whether Uzbekistan can translate its current economic momentum into a new regional reality.

A new economic model for the 21st century

In the run-up to this year’s International Monetary Fund and World Bank Spring Meetings, the one story that cut through the noise was that the World Bank had embraced industrial policy after decades of advising against it. But while much of the ensuing debate focused on whether this ‘U-turn’ is good or bad, overdue or dangerous, few pondered the fundamental question: What has actually changed?

The World Bank has merely affirmed what many of us have long argued: the framework it has promoted since 1993 – when its East Asian Miracle report cautioned against industrial-policy tools – has not served developing countries well. Such advice, World Bank Chief Economist Indermit Gill recently observed, “has the practical value of a floppy disk today.” Yet in his defence of the report, he also made clear how limited the shift remains. Industrial policy, he argued, should be “targeted and temporary,” an exception to a market-led model, rather than a tool for driving broader economic transformations.

The World Bank’s latest work confirms that industrial policy is more replicable across income levels and institutional contexts than the old consensus admitted, with a toolkit that extends beyond tariffs and subsidies. Public support for private actors, the bank now argues, should come with carrots and sticks, including withdrawal of finance from firms that underperform. This new position aligns with arguments we made in the ‘Entrepreneurial State’ and through more recent work on the role of missions and conditionalities.

But new conclusions do not automatically produce new economics. The World Bank still treats the state as a mere fixer of market failures, rather than as a market creator and shaper. The question is not whether governments should intervene after markets have failed. It is what kind of economy we want to build in the first place. Which public purposes should guide investment, and how can institutions govern the public–private bargain so that value is created collectively and shared fairly?

Viewed in these terms, the bank still falls short, because it treats fiscal-policy space as a fixed constraint within which to optimise, rather than as a set of institutional capacities that can be developed. As a result, the bank would still organise industrial policy only around specific sectors and considerations of comparative advantage. But the energy transition, water and food security, public health, and economic resilience are not sectoral issues. They call for economy-wide missions.

From market fixer to market shaper
Nor is the World Bank an isolated case. The IMF’s own economists have similarly documented how austerity and liberalisation fail to deliver. Yet these findings have yet to translate consistently into new operational practices. That needs to change. The IMF and the World Bank sit at the centre of an international order whose default advice still reflects an economics not supported by real-world evidence. What they model, measure and recommend shapes how development and macroeconomic policy are done around the world. They help determine who has access to liquidity, and on what terms; whose debt is treated as sustainable; whose public investment is seen as credible; and whose policy autonomy is constrained.

The wealthy countries that fund and control these institutions are not exempt from the consequences of the same economics. For decades, the same flawed assumptions shaped policy in Europe and the US, suppressing public investment, weakening public services, treating wages as costs rather than as fuel for aggregate demand and leaving households exposed to shocks that markets failed to manage. The resulting affordability crisis has now become a political one. The economics that constrained development policy abroad – hollowing out public capacity and narrowing what governments can do – helped fuel the far right at home.
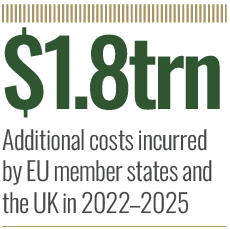
Europe’s response to the 2022 energy shock shows what is at stake. From 2022 to 2025, EU member states and the UK incurred $1.8trn in additional costs, much of it absorbed by households and public budgets, while the shareholders of firms charging higher prices benefited. Spain points to an alternative. Having invested in energy security as a mission, rather than as a subsidy category, it now generates more than half of its electricity from renewables, leaving it more insulated than its neighbours from the latest energy shock.

Consistent framework required
Making such resilience the default, rather than the exception, requires an economic framework that governments can apply consistently. The Global Progressive Mobilisation, convened by Spanish Prime Minister Pedro Sánchez, recently brought together progressive governments from around the world to start shaping a new economic consensus.

Its foundations are clear. We need public institutions with the capacity to invest, coordinate, and govern markets in the public interest. We need finance designed around missions, not leverage ratios, and policy frameworks that treat fiscal space not as a market-determined ceiling, but as something built by productive investment. And we need measures of value orientated around the common good. The argument for a new economics is being won. Now we must show what comes next.

The economic path to climate finance

As the world pursues decarbonisation, the concept of a ‘just transition’ has become ubiquitous, particularly when describing the shift away from fossil fuels in emerging and developing economies. Emissions targets at the global and national levels are viewed as the main drivers of the energy transition, and the climate policies developed to meet those targets must balance environmental and social objectives. But decarbonisation is not always the product of a planned emissions-reduction pathway. In fact, with the cost of renewables continuing to fall, many emerging and developing countries now see phasing out fossil fuels as a matter of economic survival and energy security. For example, in January 2024, Ethiopia banned the import of petrol and diesel vehicles with immediate effect. The move was striking precisely because it was framed not as a climate commitment, but as a way to reduce its annual fossil-fuel import bill of more than $5bn, which consumed a huge share of the country’s scarce foreign-currency reserves.

With the country constructing Africa’s largest hydroelectric dam, it made little economic sense to remain dependent on expensive fuel imports to power transport. Chinese electric vehicles (EVs) quickly filled the market gap created by the ban; the streets of Addis Ababa are now teeming with BYD cars. Tax exemptions and import duty waivers for EVs, coupled with the rising costs of second-hand internal-combustion-engine vehicles, have accelerated this shift in consumer behaviour. The Grand Ethiopian Renaissance Dam, which was officially opened in September 2025, produces enough surplus hydropower to run these EVs cheaply.

Swift update of solar power
Crucially, economic and energy-security concerns, not a formal emissions-reduction framework, were responsible for such rapid decarbonisation. A similar pattern seems to hold in Pakistan.

The country’s swift uptake of solar power reflected factors that created an opportunity for disruptive change, not green advocacy or a national climate plan. In 2022, a massive flood left roughly one-third of the country under water and caused more than $30bn in economic damage, straining government budgets, reducing household incomes, and undermining the state’s ability to operate public utilities. With energy costs rising, there was a clear need for an alternative to diesel generation.

Meanwhile, China had surplus solar-panel production, and the US had imposed import restrictions. Pakistan took advantage of China’s discounted solar panels to adopt renewable generation at a rapid clip. Between December 2021 and December 2025, the share of Pakistan’s electricity generated by solar increased five-fold. A late mover confronting unique energy-security challenges, Pakistan benefited from cost advantages created by global trade dynamics.

While South Africa has been following an emissions-reduction pathway for decades, an affordability crisis ultimately drove widespread decarbonisation. These countries are moving away from fossil fuels largely because of mounting economic and energy pressures, rather than a narrow focus on emissions reductions. But this does not mean that the question of justice disappears. Lower-income households account for a smaller share of the roughly eight gigawatts of rooftop solar installed in South Africa, reflecting high upfront costs. Crisis-driven decarbonisation still requires efforts to improve affordability and ensure that people from all walks of life can participate in the energy transition.

Systemic change is required
Policymakers have used the concept of a ‘just transition’ to make a morally and emotionally compelling case for decarbonisation. But they should be focusing on how to foster systemic change. Understanding that the primary drivers of solar uptake in South Africa and Pakistan or EV adoption in Ethiopia are structural and economic could help policymakers develop better tools and systems. This also has direct implications for how philanthropists and governments allocate resources. Channelling funding toward grid capacity, storage infrastructure, and affordable financing mechanisms will likely produce more durable results than funding for climate education and communication.

Investing in efforts that aim to improve people’s lives, from lower energy bills to unfettered electricity access, will do more to accelerate decarbonisation – and to change hearts and minds. To be sure, the world must reduce emissions to prevent the planet from overheating. To achieve that goal, it should focus on expanding energy access and ensuring affordability. That means recognising and adequately responding to the external pressures that can support decarbonisation pathways in emerging and developing economies. Ethiopia, Pakistan, and South Africa have shown that economic factors can provide better entry points for scaling green solutions and catalysing systemic change than top-down, morally driven transition plans.

Europe’s moment of supreme confidence

If there is one key takeaway from the recent Munich Security Conference, it is a message of trust and confidence in Europe. The EU is a technology, trade and industry powerhouse. Around Europe, the signs of this strength abound: off the northern coast of Poland, just beyond the horizon, 233 giant turbines – each almost as tall as the Eiffel Tower – are about to rise from the sea floor. With German rotors, foundations designed in Denmark, and cables from Poland and Greece, they will be towering symbols of European manufacturing excellence and industrial might. As the latest additions to an already vast Baltic fleet, they are creating thousands of jobs across the supply chain; and when they are operational, they will supply an additional 5.5 million households with clean energy.

Producing energy made in Europe, by Europe, for Europe, Poland’s offshore wind farms are as important strategically as they are economically. They add to a buildout of clean power that is happening across the continent from Italy in the South to Ireland and Lithuania in the North. Cables and interconnectors – enough to wrap the Earth many times over – are being laid to link the windy northern seas with the sunlit Mediterranean coastline, creating a superhighway for the age of electrons.

An investment revolution is underway
Meanwhile, cutting-edge fibre-optic sensors pioneered by Dutch innovators will be watching over the seabed to protect Europe’s critical infrastructure. New constellations of satellites developed in Belgium will offer enhanced surveillance capabilities from space, alongside cutting-edge radar systems from France and Spain. And all these systems will be connected by AI-powered 6G networks developed in Finland.

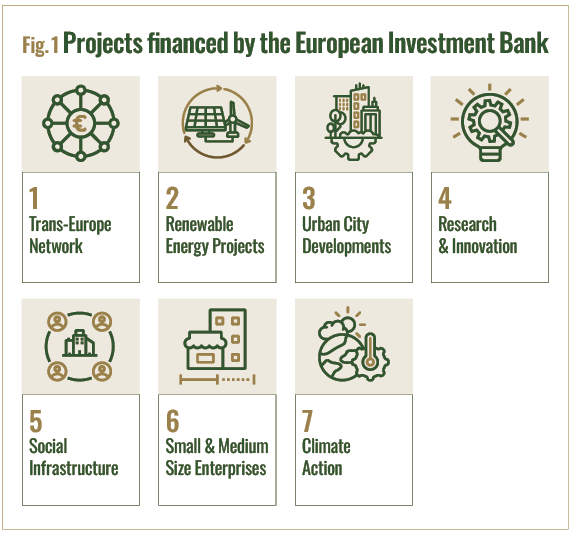
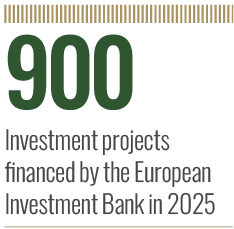
These are just a few of the nearly 900 investment projects financed by the European Investment Bank Group last year alone (see Fig 1). By leveraging EU budget guarantees to mobilise private investment, the EIB Group is powering the unfolding energy and technological revolutions. The transition into tomorrow’s world is already in full swing in Europe – a major development that remains overlooked amid rapid geopolitical change.
In fact, the overall investment in the EU’s energy transition reached a new record in 2025, approaching €400bn – from hydropower in Austria to new railways in Czechia, and from energy efficiency upgrades by small businesses in Croatia to clean technologies deployed by heavy industries in Portugal. Just in the past year, the combined market capitalisation of European renewables companies has risen by over 50 percent. Something that many thought impossible in the near term is already happening – Europe is irreversibly weaning itself off Russian gas.

European investments in defence are increasing even more rapidly. European defence stocks have tripled in value in the past three years. Europe’s industrial production capacity now exceeds even that of the US in critical areas, including artillery shells. Europe is moving by leaps and bounds into strategic sectors and technologies such as drones.

A new venture-capital ecosystem geared toward pioneering security and defence enterprises has emerged almost overnight and essentially from scratch.

A continent reshaped by disruption
We have seen a similar mobilisation before. In 2020, no one expected that a European biotech company would pioneer a vaccine against an unknown virus in a matter of months, helping the world defeat a once-in-a-century pandemic. Nor did anyone think that European leaders would launch a massive recovery and resilience programme financed by joint debt – an unprecedented show of solidarity and unity. When Russia’s full-scale invasion of Ukraine caused a massive spike in energy prices, everyone assumed that the European economy would buckle. Instead, the eurozone’s GDP grew faster than China and the US that year.

In the face of trade warfare, intense market volatility, and shifting traditional partnerships and alliances, European companies have proven resilient, not only diversifying their trade flows but also maintaining strong growth and investment. European stock markets ended up outperforming US exchanges in 2025, rewarding investors who put their trust in our economy. Unemployment is hovering near record lows, and growth is picking up – thanks to high-performing countries such as Spain and Poland. Europe has emerged as a beacon of stability in an uncertain world.

Time and again, the EU has adapted and reinvented itself in the face of crises, leaving it well prepared to navigate a tempestuous geopolitical environment. An export powerhouse, the EU is home to world-class universities and research centres, as well as a vibrant start-up ecosystem. Opinion polls show record levels of public support for the EU and the euro, and global surveys indicate that majorities around the world see the EU as a great power on an equal footing with the US and China.

European stock markets ended up outperforming US exchanges in 2025

They are right to do so. With a $22trn economy, a vast single market of nearly a half-billion people, and plans for another wave of enlargement, Europe’s weight in the world is undeniable. It may be a different kind of superpower, one that prizes values, rules, and multilateralism over sheer might. But its power lies in its commitment to principles and willingness to back its partners and allies, as demonstrated by its status as the biggest source of financial and military assistance to Ukraine.

Europe continues to build bridges in a world of walls. It is the world’s leading trade power, residing at the centre of a vast, ever-expanding network of free-trade agreements. It is also an investment superpower that promotes shared prosperity around the world. As the biggest source of humanitarian aid and development finance, Europe funds everything from global vaccination campaigns to projects to improve water supplies in Amman and Karachi.
We do so because we remain committed to the same values that brought us this far. European unification started nearly eight decades ago from the ashes of two world wars. Our parents and grandparents learned from the tragedies and mistakes of that dark era, and we can draw inspiration from their example to shape a better future for ourselves and others around the world. Ours is a society based on inclusion, equality of opportunity, intellectual freedom, peace, and the rule of law.

We know what needs to be done to preserve this way of life. We need even deeper integration, including our capital markets. We need even more large-scale investment in critical infrastructure and strategic capabilities. We need simplification to make the EU more agile and efficient. And we need more win-win partnerships and alliances to diversify our supply chains and open new markets for our goods. Momentum is building in all these areas. European leaders’ minds are focused, and we are determined to capitalise on Europe’s strengths as the world’s underappreciated superpower.
Saudi Air Navigation Services: Financial resilience through operational excellence

Saudi Air Navigation Services, or SANS, is the Kingdom of Saudi Arabia’s national air navigation provider, guiding over a million flights a year safely and efficiently. It manages over two million square kilometres of airspace from 19 towers, nine approach centres, and two area control centres; delivering air traffic control, airspace management, and aeronautical information services.

In our third and final video with Saudi Air Navigation Services, CFO Bandar Alyafie and members of SANS’ finance division discuss the operational reforms and improvements that have improved its financial resilience, enabling long-term sustainability for the operator and Saudi Arabia’s skies.

Watch the rest of this video series with Saudi Air Navigation Services:
Creating sustainable skies for Vision 2030
Investing in growth, resilience, and sustainability

Bandar Alyafie: Saudi Air Navigation Services has sustainability as our sixth corporate pillar.

From a finance perspective, the way we plan, allocate resources, and manage risks, forms the foundation of our long term financial resilience.

The three biggest enhancements we have made have been to our finance and accounts operation, procurement and supply chain, and digital finance transformation.

Zain Abdulmannan: At SANS, in our accounts operations, we enhanced our financial practices through stronger controls, automated processes, and improved collections: driving efficiency, reducing risk and supporting long-term sustainability.

We wanted stronger cash discipline and reliable reporting; improving collections and billing efficiency, while tightening controls to reduce risk.

To achieve this we moved to recurring invoice-track billing, ran proactive customer visits, refined our credit-loss methodology, and reduced the invoice review cycle.

These delivered record-level collections and recovered long-overdue balances, strengthening cash flow and reducing our reliance on external financing.

Bandar Alyafie: Efficient supply chain practices contribute to our sustainability through controlling costs, supporting local businesses, and advancing Vision 2030.

We have strengthened our supplier management and expanded our local supplier base: improving our resilience, developing the local economy, and earning us the global CIPS Procurement Excellence Award.

Sultan Mujallid: Since we started digitally transforming our finance function, we have adopted EPM planning, Power BI dashboards, automated IFRS 16 leasing solutions, and financial governance applications; in addition to multiple automations and advanced modules.

These initiatives have reduced manual processing and errors, enabled real time insights, and accelerated reporting by up to 150 percent – leading to faster and better analysis and decision making.

Bandar Alyafie: These financial, operational and digital improvements make SANS more productive, steadier, and more self-reliant: freeing resources to invest in continuous growth and future-ready infrastructure.

Going forward, we aim to expand AI-enabled processing and analysis, broaden our investment scope, and further strengthen our governance.

These priorities will help improve efficiency, enhance decision-making, and reinforce SANS’ long-term sustainability and resilience.

Saudi Air Navigation Services: Investing in growth, resilience, and sustainability

Saudi Air Navigation Services, or SANS, is the Kingdom of Saudi Arabia’s national air navigation provider, guiding over a million flights a year safely and efficiently. It manages over two million square kilometres of airspace from 19 towers, nine approach centres, and two area control centres; delivering air traffic control, airspace management, and aeronautical information services.

In the second of our series of three videos with Saudi Air Navigation Services, CFO Bandar Alyafie and people from the finance and sustainability divisions discuss aligning SANS’ financial planning, corporate governance, and investment strategy with its sustainability agenda; and their dedication to making Saudi Arabia’s skies safer and greener for generations to come.

Watch the rest of this video series with Saudi Air Navigation Services:
Creating sustainable skies for Vision 2030
Financial resilience through operational excellence

Bandar Alyafie: Saudi Air Navigation Services looks after the Kingdom of Saudi Arabia’s airspace, guiding over a million flights a year through our skies.

For us, sustainability means creating long-term value by investing today in the capabilities, infrastructure, and systems to enable the future; balancing safety, growth, and environmental responsibility in every decision.

Sultan Mujallid: Long-term financial planning in SANS is crucial to our strategy, because it allows us to align investments with growth, resilience and sustainability priorities.

It ensures long-term value creation, responsible growth, and the ability to invest in future-ready, environmentally conscious infrastructure.

We built our five-year plan around disciplined budgeting and capital allocation that prioritises digital transformation, modernisation, and sustainable growth initiatives.

Our results show discipline in action: meaningful budget savings, and above-target KPIs.

When evaluating investment opportunities, we focus on long-term value, resilience, and balanced returns; prioritising projects that improve capacity and make our operations more sustainable.

This investment strategy has delivered a significant increase in low-risk investment returns with funding the modernisation and digital tools that power our efficiency gains.

Ahmed Alzahrani: Strong corporate governance gives sustainability structure and accountability: ensuring commitments are tracked, risks are managed, and decisions stay transparent and consistent.

We apply international frameworks – ISO 31000 for risk management, and GRI for reporting – supported by strong SLAs, internal controls, and a clear code of conduct.

Thanks to these measures we achieved strong audit outcomes, and earned ISO 9001 and 45001 certifications, reflecting genuine governance maturity.

Bandar Alyafie: Our finance division will keep Saudi Air Navigation Services’ sustainability efforts funded, measured, and accountable; through disciplined capital allocation, strong governance, and transparent, data-driven reporting.

We are all dedicated and proud to be helping SANS develop into a world-leading air navigation services provider – and to be making the Kingdom’s skies safer and greener for generations to come.

Saudi Air Navigation Services: Creating sustainable skies for Vision 2030

Saudi Air Navigation Services, or SANS, is the Kingdom of Saudi Arabia’s national air navigation provider, guiding over a million flights a year safely and efficiently. It manages over two million square kilometres of airspace from 19 towers, nine approach centres, and two area control centres; delivering air traffic control, airspace management, and aeronautical information services.

In the first or our series of three videos with Saudi Air Navigation Services, Ahmed Alzahrani, its Chief Strategy and Sustainability Officer, explains all the ways SANS has been reducing its environmental footprint in line with the Kingdom’s Vision 2030: positioning Saudi Arabia as a global hub, while advancing the environmental stewardship at the heart of the national strategy.

Watch the rest of this video series with Saudi Air Navigation Services:
Investing in growth, resilience, and sustainability
Financial resilience through operational excellence

Ahmed Alzahrani: Saudi Air Navigation Services, or SANS, is the Kingdom of Saudi Arabia’s national air navigation service provider, guiding over a million flights a year safely and efficiently.

We provide our services from 19 towers, nine approach centres, and two area control centres, to manage more than two million square kilometres of airspace.

We deliver air traffic control, airspace management, and aeronautical information services, supported by engineering and maintenance; keeping our skies safe, efficient, and reliable around the clock.

Ahmed Alzahrani: When we started looking at ways to reduce our environmental footprint, we found the greatest opportunity was in airspace and flight efficiency: shorter routes, fewer holding patterns, and reduced taxi times – where small gains multiply across a million flights.

Through the Saudi Future Airspace Concept, or SFAC, we are fully restructuring our airspace: optimising sectors and enabling direct routes, while designing for growth and a smaller carbon footprint.

We have adopted Intelligent Approach Technology so we can safely land more planes while cutting holding times and emissions – by moving from fixed-distance to time-based separation, and adapting to wind and wake conditions dynamically using real-time data.

These changes have already increased runway throughput and reduced delays. Parallel runway operations alone cut takeoff and landing times by up to 60 percent, directly lowering fuel use and emissions.

Our ambition at Saudi Air Navigation Services is to be a globally leading sustainable air navigation service provider, supporting the national target of a 30 percent flight-emissions reduction, and net zero by 2060.

We have embedded sustainability across our operations and achieved measurable efficiency gains. Next, we will formalise it further, pursuing ISO 14001 certification and CANSO GreenATM accreditation by 2026.

Vision 2030 is the Kingdom’s roadmap for sustainability growth. For aviation, it means expanding capacity and connectivity while building a resilient, environmentally responsible sector for generations to come.

Our work directly serves Vision 2030’s aviation goals: positioning the Kingdom as a global hub, while advancing the environmental stewardship at the heart of the national strategy.

The mispricing of war

In the space of just a few weeks, the throttling of shipping traffic through the Strait of Hormuz has revealed the true nature of the US-Israeli war with Iran. This is no regional conflict, because the entire world is being invoiced. While the size of the bill remains to be determined, it is already obvious that the belligerents won’t be the only ones paying the tab. War is typically framed in terms of national security, territorial integrity, humanitarianism, or even civilisational struggle. But such rationales obscure an unsettling truth: war is one of the most mispriced of human activities. Those who initiate it rarely bear the full costs, which tend to be displaced across borders, markets and time. Beyond the physical destruction, war generates massive negative externalities. The price paid by the perpetrator reflects only a small fraction of the social cost.

Of course, the intuition that war imposes downstream costs on others is deeply embedded in the political-economy literature, running from Adam Smith and David Ricardo to John Maynard Keynes and Karl Polanyi. But globalisation has transformed the effect into a structural feature of the modern economy.

Economic growth diminishing
Consider the arithmetic of the current Iran conflict. Beyond the loss of life, direct US military spending may run into the tens or even hundreds of billions of dollars. Yet the broader economic cost – transmitted through energy, food and financial markets – runs far higher. The International Monetary Fund warns that the war is already diminishing many economies’ growth prospects, as energy shocks ripple outward and inflationary pressures intensify.

The transmission mechanism is brutally simple. When oil and gas prices rise, transportation and electricity become more expensive. When fertiliser costs increase, so do food prices. Central banks may respond by assuming a tighter monetary-policy stance. Ultimately, growth slows. Yet this domino effect is missing from the actual war ledger. Efforts to measure the true costs of war have consistently found that they lie beyond the battlefield. In their work on the Iraq war, Joseph Stiglitz and Linda Bilmes tallied a catalogue of costs in the trillions of dollars once macroeconomic effects were included. Similarly, both the IMF and the World Bank have found that violent conflict depresses growth in economies far removed from it.

Even under conservative assumptions, the US may bear only a modest share of the total global economic damage (much as the negative spillovers of the war in Ukraine far exceed the direct cost to Russia). As European Central Bank President Christine Lagarde recently cautioned, the rest is diffused across the system, absorbed by energy importers, emerging markets and households worldwide. War, in this sense, is globally subsidised.

Three mechanisms make this possible. The first is spatial. Modern economies are deeply interconnected. When war disrupts one node (particularly an energy chokepoint), the effects cascade outward. The Strait of Hormuz is not simply a geographic passage but a structural vulnerability in the global economy.
The second mechanism is temporal. War typically requires the present to borrow from the future. Governments finance conflict through debt, deferring its cost to generations not yet politically represented. The fiscal consequences of past wars continue to unfold decades later, showing up in public debt, constrained policy options, and obligations that outlast the politics that created them.

The third mechanism is distributive. War concentrates decision-making while dispersing the costs. Those who decide are not the ones who pay. This last insight lies at the heart of modern conflict economics. The Oxford University economist Paul Collier has shown that wars persist not because they are collectively rational, but because they are privately beneficial. Small groups capture the gains as the broader population absorbs the losses. Today’s networked economy amplifies this asymmetry.

When the world pays the price
As Edward Fishman of the Centre on Global Energy Policy argues in his book Chokepoints, power today flows through global systems such as energy routes, financial networks and supply chains. But conflict turns these into channels for economic contagion. The result is a peculiar inversion. War appears expensive in theory but affordable in practice, because much of the bill is paid by others. This mispricing has predictable consequences. When goods are subsidised, we get more of them. When their price is too low, we get oversupply: too much pollution, too much risk and too much war.

The policy challenge is therefore familiar, even if the politics are not: to discourage war, its costs must be internalised. Those who initiate conflict must bear a greater share (or, even better, the entirety) of its true costs. Ensuring that outcome requires an effective global institution that can align the private and social costs of conflict more effectively than global markets can. Until the world can come up with such an institution, the incentives will remain perverse, because one of the most destructive activities imaginable seems so affordable to those who undertake it.

Toronto’s condo crisis and the failure of economic forecasting

Those familiar with the British sit-com The IT Crowd, which was about workers in the IT department of a firm, and premiered in 2006, will remember the catchphrase “Have you tried turning it off and on again?” which was their go-to response for any technical computing problem. A similar technique is currently being applied to the real estate sector in Canadian cities such as Toronto, especially for the market for new condominiums (or condos).

For the last decade and more, Toronto has been the construction hub of North America, its skyline studded with more cranes than any other city. Underlying all this activity was the unquestioned belief among investors that real estate was a safe investment. This was the case even during the Great Financial Crisis (GFC), which the Canadian economy endured quite well, in part because banks did not resort to the same complex financial derivatives as did their counterparts in the US. After the briefest of dips, house prices showed explosive growth, doubling over the next 12 years and almost tripling by the time they reached their glorious peak in 2022.

Usually this growth was attributed to demand from an expanding population, which fits with the traditional view that price rises are typically driven by excess demand. In reality, the number of houses being sold was fairly static. The only kind of property that was selling like hot cakes was the kind that didn’t actually exist: pre-construction condos.

Boxes in the sky
Often these were ‘shoebox’ apartments that were intended more as an investment than a place to live, and represented a kind of futures bet on the market. The majority were purchased by investors, who could put down a small deposit before construction began, and expect to sell at a profit just before completion to an end-user or another investor. Mainstream economists saw no problem with this because on the surface it seemed the economy was doing well. The central bank cut interest rates to the bone, since according to their metrics, which didn’t account for house prices, inflation was quiescent.

The deterministic models of the past are giving way to new approaches that embrace uncertainty

When official inflation jumped in the post-Covid years, interest rates bounced off their lows. Mortgages suddenly became more expensive. Population growth, which was almost entirely due to immigration, which peaked at around 3.2 percent in 2022, compared to an average 0.5 percent for G7 countries, was suddenly thrown into reverse, with Canada actually reporting a small decline in 2025 for the first time on record. The real estate market on the whole adjusted to these contortions with a decline in both sales and prices. But the market for pre-construction condos didn’t adjust – it just stopped.

In December 2025, only 87 pre-construction units were sold across the entire Greater Toronto Area, which has a population of about 7.8 million. That is the lowest single-month total in the 45 years that data has been tracked. Developer activity also ground to a halt, with just 10 new condo projects launching throughout the entire year, compared to the dozens typical in a healthy market. Remaining new home inventory hit a record high equivalent to over two years of sales. And in the first quarter of 2026, things really iced up, as zero new projects were launched. There is a sense though that this reset is about more than just pre-construction condos – it is about how we think about the economy.

Tail events
The GFC was a crisis not just for the economy, but also for the field of economics. Not in the sense that economists actually lost their jobs, but because their models failed. Economists had long assumed that probabilities could be described by a so-called normal distribution, or bell curve as it is sometimes known.

However, risk models based on this assumption quickly broke down when it turned out that so-called tail events had a much higher chance of occurring than the model suggested. And mainstream economics, which was based on the idea that the economy is a rational, efficient, self-stabilising system – which is immune to things like booms and busts – was thrown into a state of complete crisis along with the economy.

While the field of economics is famously resistant to change and new ideas, a couple of decades later, things do show signs of moving on, at least in some corners of the profession. In their recent book Adaptive Finance: Embracing Uncertainty and Complexity, economists Frank Fabozzi and Sergio Focardi write that “The need for models predicting tail events and market anomalies has become increasingly apparent after the GFC.

“Traditional models, which often rely on normal distributions and the assumption of efficient markets, could not predict the extreme events that characterised the crisis, such as the collapse of major financial institutions and the sudden freeze in credit markets.”

It is no surprise that in the “new paradigm in economics and finance” described by Fabozzi and Focardi, “the deterministic models of the past are giving way to new approaches that embrace uncertainty.” As another market freezes up in front of us, it is past time for economists to embrace these new insights. Instead of just saying, “Let’s try turning it off…”

A new blueprint for real estate investment

As the global real estate market enters a long-awaited inflection point in 2026, institutional players and private capital are finally returning to the field, signalling a shift from stagnation towards a new cycle of valuation and growth, according to the latest market outlook from Morgan Stanley. Yet, as commercial real estate investment activity is forecast to rise significantly this year, investors are being forced to rethink how they deploy capital in an environment still marked by dislocation and selectivity, as noted in the US Real Estate Market Outlook 2026 report by CBRE. For those looking beyond the headline-grabbing institutional deals, the most compelling opportunities are increasingly found in the middle market, where the inherent complexity of the asset often serve as a natural, protective barrier to entry for larger, more rigid competitors.

Middle market advantage
The middle market remains the largest segment of the investment landscape, structurally resembling a pyramid in which the vast majority of opportunities lie at the smaller end. It is also where inefficiency persists, and where opportunity follows. Our strategy is intentionally contrarian, focusing on deals under $50m, a segment where access to capital, particularly at this stage of the recovery cycle, is more limited. As a result, pricing dislocations tend to be more pronounced. In this space, we often find great properties with complicated histories, capital stack challenges, leasing gaps, or simple management fatigue. Unlike large institutions that must wait out long market cycles, many sellers here are driven by urgent liquidity needs or personal circumstances rather than strategic timing.

Compelling value is emerging in overlooked or dislocated asset classes

They typically cannot wait out market cycles, which further contributes to attractive entry points. This creates a fertile opportunity to acquire high-quality assets well below replacement cost, allowing us to address specific operational issues and create substantial value that is fundamentally independent of broader macro conditions. At the same time, middle-market activity is increasingly led by well-capitalised local operators who have a deep understanding of their submarkets. That local expertise, combined with disciplined capital, is a powerful advantage in identifying and executing opportunities others may overlook.

Alongside these market dynamics, family offices are undergoing a significant structural shift. Many are moving away from traditional stock-and-bond allocations to increase exposure to real assets. Driven by the need for income stability, inflation protection, and tax efficiency, families are moving beyond fragmented, indirect fund structures to build direct, intentional real estate portfolios.

Historically, access to real estate has been constrained by institutional fund structures or by fragmented direct investment opportunities that were difficult to scale. Today, more families are seeking direct, intentional exposure to the asset class. The appeal is clear: durable income streams, depreciation benefits, and the ability to exert more control over outcomes in an increasingly uncertain environment. In this landscape, relationship-first investing has become a critical differentiator and ensuring that capital is aligned with the family’s specific tax, income, and legacy-building objectives.

Beyond traditional core markets, compelling value is emerging in overlooked or dislocated asset classes. At the same time, we are seeing significant opportunities in the office sector, an area many investors have prematurely written off. In primary hubs like New York, Northern California, Houston, and San Diego, high-quality assets are trading at steep discounts, sometimes near land value. By targeting these dislocated areas, investors can capitalise on mispricing that others either lack the local expertise to identify or the operational discipline to execute upon effectively.

Navigating a bifurcated market
Today’s market can sometimes be a ‘feast-or-famine’ environment. Assets that align with modern tenant demand continue to perform, while those that do not struggle regardless of price. This makes underwriting more nuanced than ever; a 30–50 percent discount is often insufficient to offset functional or locational obsolescence. When that distinction is made correctly, today’s environment offers a rare opportunity to acquire quality assets at historically attractive bases. Conversion and repositioning strategies are also gaining traction, particularly in large, dense markets where supply-demand imbalances are most acute. These markets benefit from higher land values and stronger tenant demand, both of which support redevelopment economics.

Opportunity in real estate has not disappeared; it has simply shifted. Success in this cycle will depend on a blend of discipline, creativity and conviction. Investors who can navigate complexity, lean into long-term relationships, and act decisively in inefficient parts of the market will be best positioned to generate durable, risk-adjusted returns.